Topics (282k) Articles (291k) Users (352) Discussions (237) Comments (383) Files (6k) New article

Life expectancy is a statistical measure that estimates the average number of years a person can expect to live, based on demographic factors such as current age and sex, as well as historical mortality rates. It is commonly used to assess the overall health and longevity of populations and can vary significantly between different countries, regions, and demographic groups due to factors like healthcare access, lifestyle, economic conditions, and environmental influences.
A life annuity is a financial product that provides regular payments to an individual for the duration of their life. It is often used as a way to ensure a stable income stream during retirement. Here are some key features of life annuities: 1. **Payment Structure**: Upon purchase, the individual typically makes a lump sum payment (the premium) to an insurance company or financial institution. In return, they receive periodic payments, which can be monthly, quarterly, or annually.
A Liability-Driven Investment (LDI) strategy is an investment approach typically employed by institutional investors, such as pension funds and insurance companies, to align their investment portfolios with their future liabilities. The primary goal of LDI is to ensure that the assets will be sufficient to meet the future obligations of the institution (such as pension payouts or insurance claims) as they come due.
A Lexis diagram is a graphical representation used in demography and epidemiology to visualize the relationship between age, period, and cohort. It helps researchers analyze how different cohorts (groups of individuals born in the same time period) experience various life events, such as births, deaths, or illnesses, over time. The diagram typically consists of: - **Horizontal axis:** Represents time or calendar years (the period). - **Vertical axis:** Represents age.
The Lee–Carter model is a widely used statistical model for forecasting mortality rates and modeling demographic trends. Developed by economist Richard Lee and statistician Lawrence Carter in 1992, the model provides a framework for analyzing and projecting mortality rates for a population, typically focusing on age-specific death rates. ### Key Features of the Lee–Carter Model: 1. **Functional Form**: The model expresses the logarithm of age-specific mortality rates as a function of time and age.
Late-life mortality deceleration refers to the phenomenon where the rate of mortality slows down or decreases among older individuals as they approach the extremes of life, particularly in the context of aging populations. This concept suggests that as people reach advanced ages, their likelihood of dying may not increase as steadily as one might expect. In other words, rather than experiencing a constant increase in the risk of death as individuals age, there may be a leveling off or even a slight decrease in mortality rates among the oldest old.
The Kaplan–Meier estimator is a statistical tool used to estimate the survival function from lifetime data. It is particularly useful in medical research for analyzing time-to-event data, such as the time until an event of interest occurs (like death, relapse, or failure) when some subjects are censored, meaning they leave the study or do not experience the event during the observation period.
The Joint Board for the Enrollment of Actuaries (JBEA) is a U.S. federal agency that oversees the enrollment of actuaries to practice before the federal government, primarily in the context of pension plans and other employee benefit programs. Established under the Employee Retirement Income Security Act of 1974 (ERISA), the JBEA is responsible for certifying actuaries who meet specific qualifications and adhere to regulatory requirements.
The International Congress of Actuaries (ICA) is a significant global event for professionals in the actuarial field, organized to address advancements, challenges, and innovations in actuarial science, insurance, pensions, and risk management. It typically brings together actuaries and experts from around the world to exchange knowledge, share research, and discuss the latest trends and developments in the industry.
An insurance score is a numerical representation used by insurance companies to help assess the risk associated with providing coverage to an individual or entity. This score is typically derived from various factors, including credit history, payment patterns, and other financial behaviors. Although it may vary by insurer, the insurance score is often a key component in determining premiums for auto, home, and other types of insurance.
The insurance cycle refers to the recurring pattern of fluctuations in the insurance market, particularly the pricing and availability of insurance coverage. It typically consists of two main phases: the hard market and the soft market. 1. **Hard Market:** - In a hard market, insurance premiums increase, and underwriting standards become stricter. Insurers may reduce their coverage options, exclude certain risks, or require higher deductibles.
The Insider investment strategy refers to a trading approach that involves purchasing stocks based on the buying patterns of company insiders—executives, directors, and other individuals with access to non-public, material information about the company. Insiders often have a better understanding of the company's business prospects and financial health than the average investor, so their trading activity can signal confidence (or lack thereof) in the company's future performance. ### Key Elements of the Insider Investment Strategy: 1. **Insider Buying vs.
An influential observation in statistics refers to a data point that significantly affects the results of a statistical analysis, particularly in regression models. These observations can have a disproportionate impact on the estimates of parameters (such as regression coefficients), the overall fit of the model, and predictions made by the model.
Incurred but not reported (IBNR) refers to insurance claims that have occurred but have not yet been reported to the insurer. This concept is particularly important in the context of insurance reserves and actuarial science, as it represents a liability for the insurance company. IBNR is significant for several reasons: 1. **Claims Development**: Insurance claims can take time to be reported, especially in certain lines of insurance like health, workers' compensation, or auto insurance.
The term "Increased Limit Factor" (ILF) may refer to different concepts depending on the context in which it is used. In general, it is most commonly associated with insurance and risk management industries, particularly in relation to policy limits and coverage. 1. **Insurance Context**: In the context of insurance, the Increased Limit Factor is used to calculate additional premiums for policyholders who wish to raise their coverage limits beyond the standard amount offered by an insurance policy.
IFRS 4, titled "Insurance Contracts," is an International Financial Reporting Standard established by the International Accounting Standards Board (IASB). It was introduced in 2004 and is primarily focused on the accounting for insurance contracts by insurance companies. Here are some key points about IFRS 4: 1. **Scope**: IFRS 4 applies to all insurance contracts as defined within the standard, including reinsurance contracts.
IFRS 17, or International Financial Reporting Standards 17, is a standard issued by the International Accounting Standards Board (IASB) that establishes principles for the recognition, measurement, presentation, and disclosure of insurance contracts. It came into effect on January 1, 2023, replacing the previous standard, IFRS 4, which allowed a wide variety of approaches to insurance contract accounting.
A heavy-tailed distribution is a type of probability distribution that has a tail, which is the part of the distribution that represents extreme values, that is significantly heavier or more significant than that of the exponential distribution. This means that it has a higher probability of producing values far from the mean compared to lighter-tailed distributions, such as the normal distribution. In practical terms, this implies that heavy-tailed distributions can model phenomena where extreme events have a considerable chance of occurring.
Hattendorff's theorem is a result in queuing theory that pertains to the analysis of single-server queues, particularly those that follow a Markovian arrival process and service time distribution. The theorem deals with the expected waiting time in the queue and helps to determine both the average number of customers in the queue and the average time a customer spends in the system.
The Gompertz–Makeham law of mortality is a mathematical model used to describe the age-specific mortality rates, particularly in humans and other organisms. It combines two components: the Gompertz function, which accounts for the increasing mortality risk due to aging, and a constant term that represents the background or external risk of death that does not depend on age.
Pinned article: Introduction to the OurBigBook Project
Welcome to the OurBigBook Project! Our goal is to create the perfect publishing platform for STEM subjects, and get university-level students to write the best free STEM tutorials ever.
Everyone is welcome to create an account and play with the site: ourbigbook.com/go/register. We belive that students themselves can write amazing tutorials, but teachers are welcome too. You can write about anything you want, it doesn't have to be STEM or even educational. Silly test content is very welcome and you won't be penalized in any way. Just keep it legal!
Intro to OurBigBook
. Source. We have two killer features:
- topics: topics group articles by different users with the same title, e.g. here is the topic for the "Fundamental Theorem of Calculus" ourbigbook.com/go/topic/fundamental-theorem-of-calculusArticles of different users are sorted by upvote within each article page. This feature is a bit like:
- a Wikipedia where each user can have their own version of each article
- a Q&A website like Stack Overflow, where multiple people can give their views on a given topic, and the best ones are sorted by upvote. Except you don't need to wait for someone to ask first, and any topic goes, no matter how narrow or broad
This feature makes it possible for readers to find better explanations of any topic created by other writers. And it allows writers to create an explanation in a place that readers might actually find it.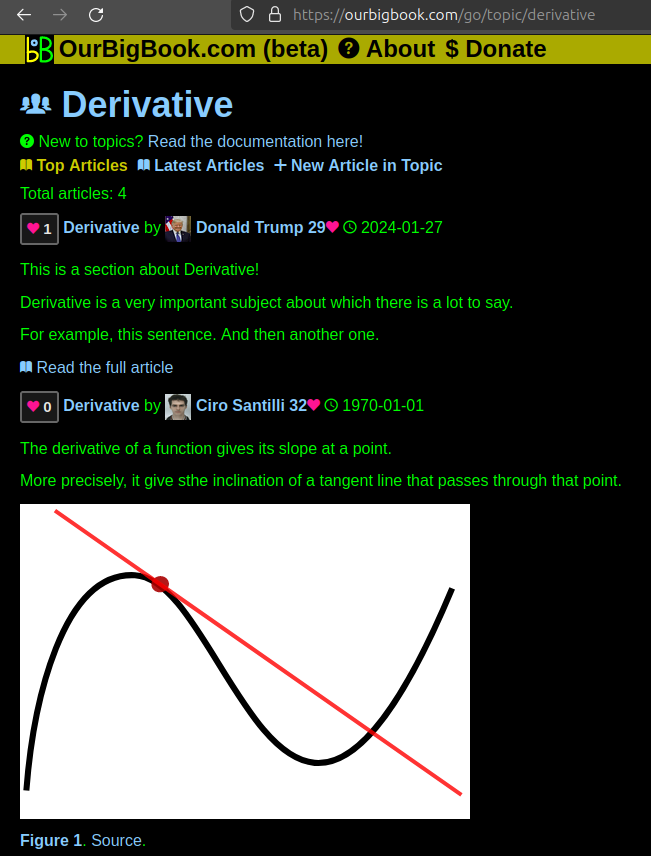
Figure 1. Screenshot of the "Derivative" topic page. View it live at: ourbigbook.com/go/topic/derivativeVideo 2. OurBigBook Web topics demo. Source. - local editing: you can store all your personal knowledge base content locally in a plaintext markup format that can be edited locally and published either:This way you can be sure that even if OurBigBook.com were to go down one day (which we have no plans to do as it is quite cheap to host!), your content will still be perfectly readable as a static site.
- to OurBigBook.com to get awesome multi-user features like topics and likes
- as HTML files to a static website, which you can host yourself for free on many external providers like GitHub Pages, and remain in full control

Figure 2. You can publish local OurBigBook lightweight markup files to either OurBigBook.com or as a static website.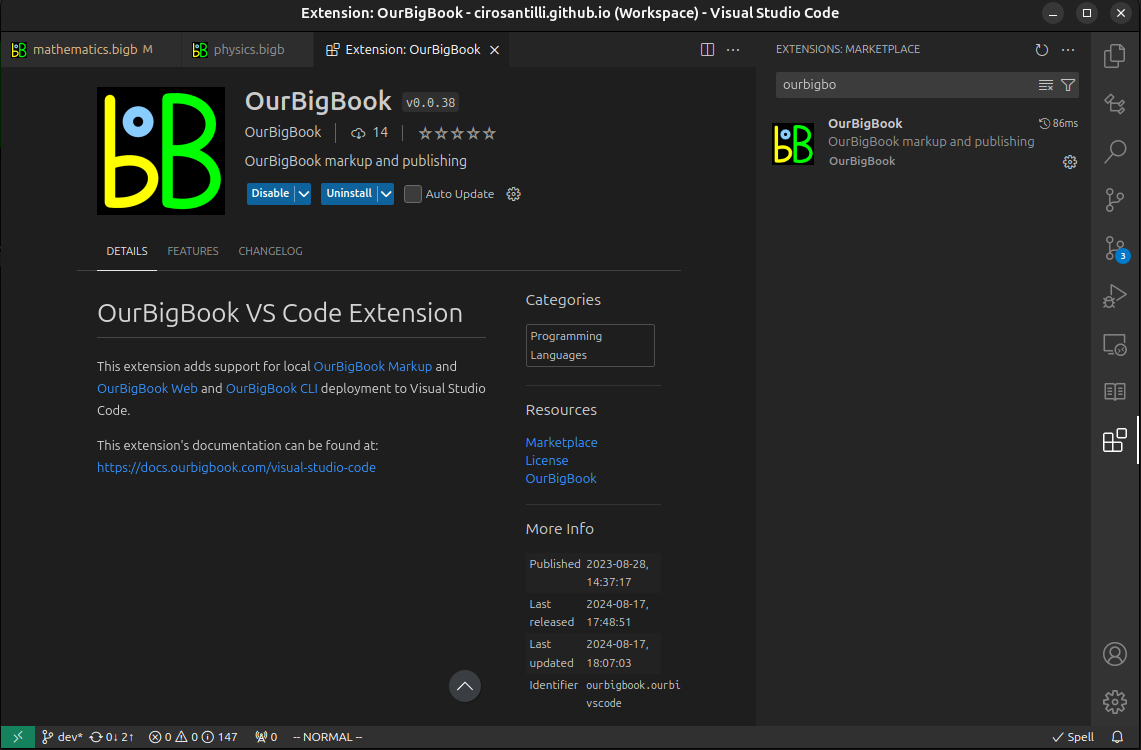
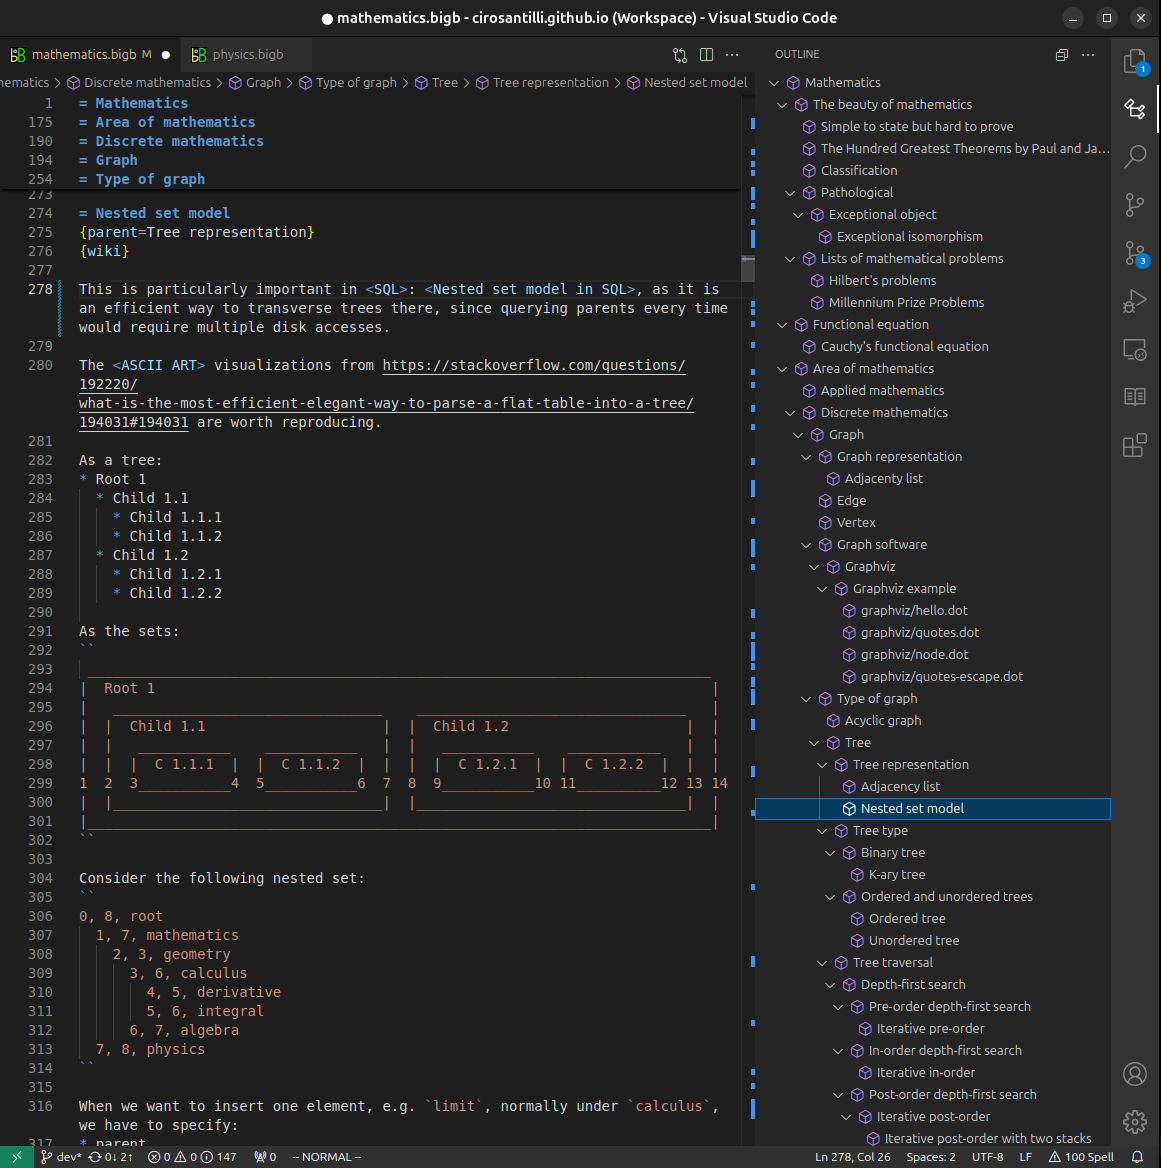
Figure 3. Visual Studio Code extension installation.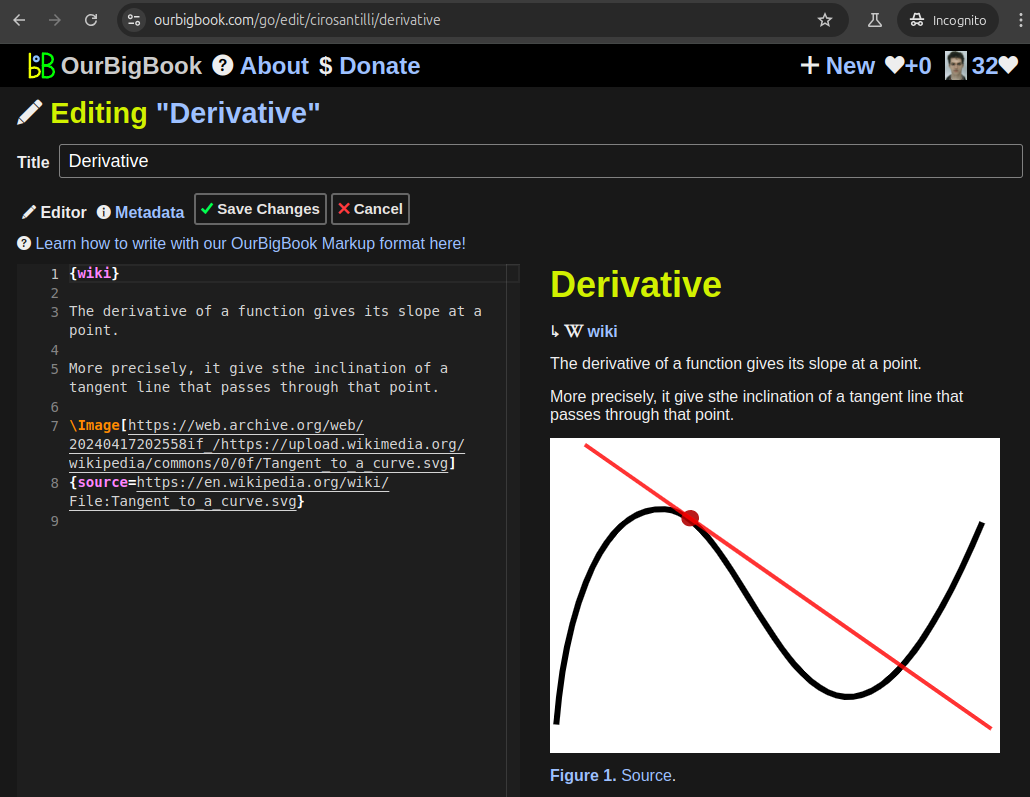
Figure 5. . You can also edit articles on the Web editor without installing anything locally. Video 3. Edit locally and publish demo. Source. This shows editing OurBigBook Markup and publishing it using the Visual Studio Code extension. 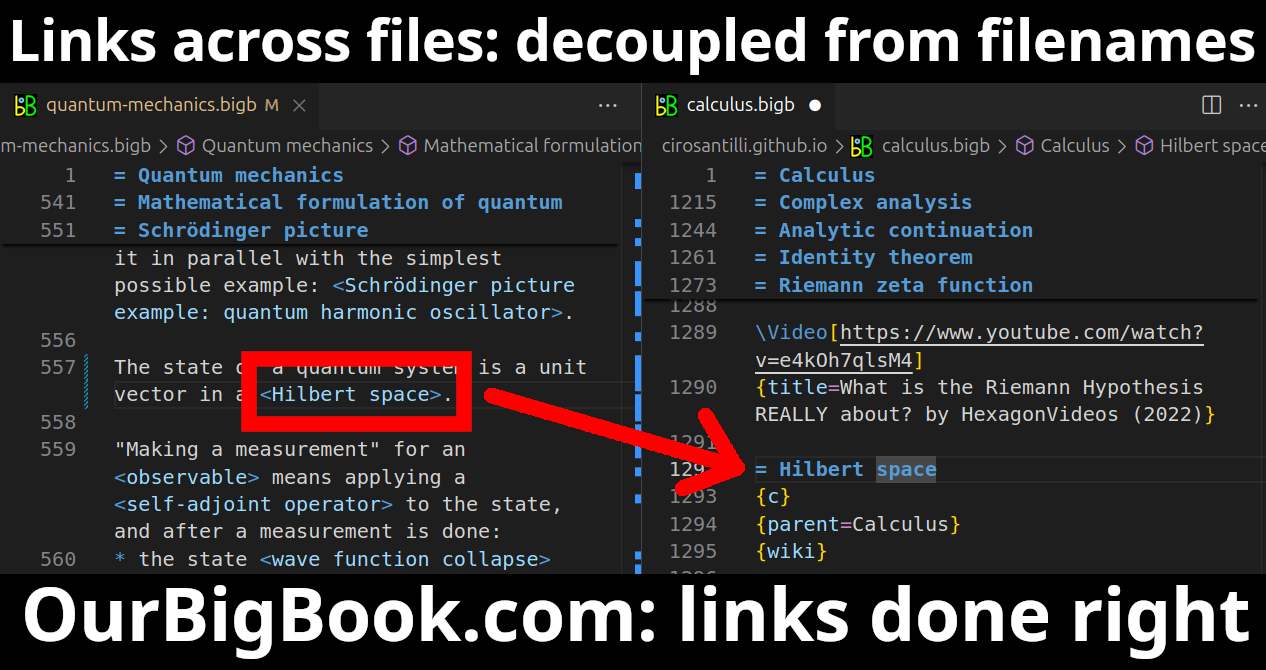
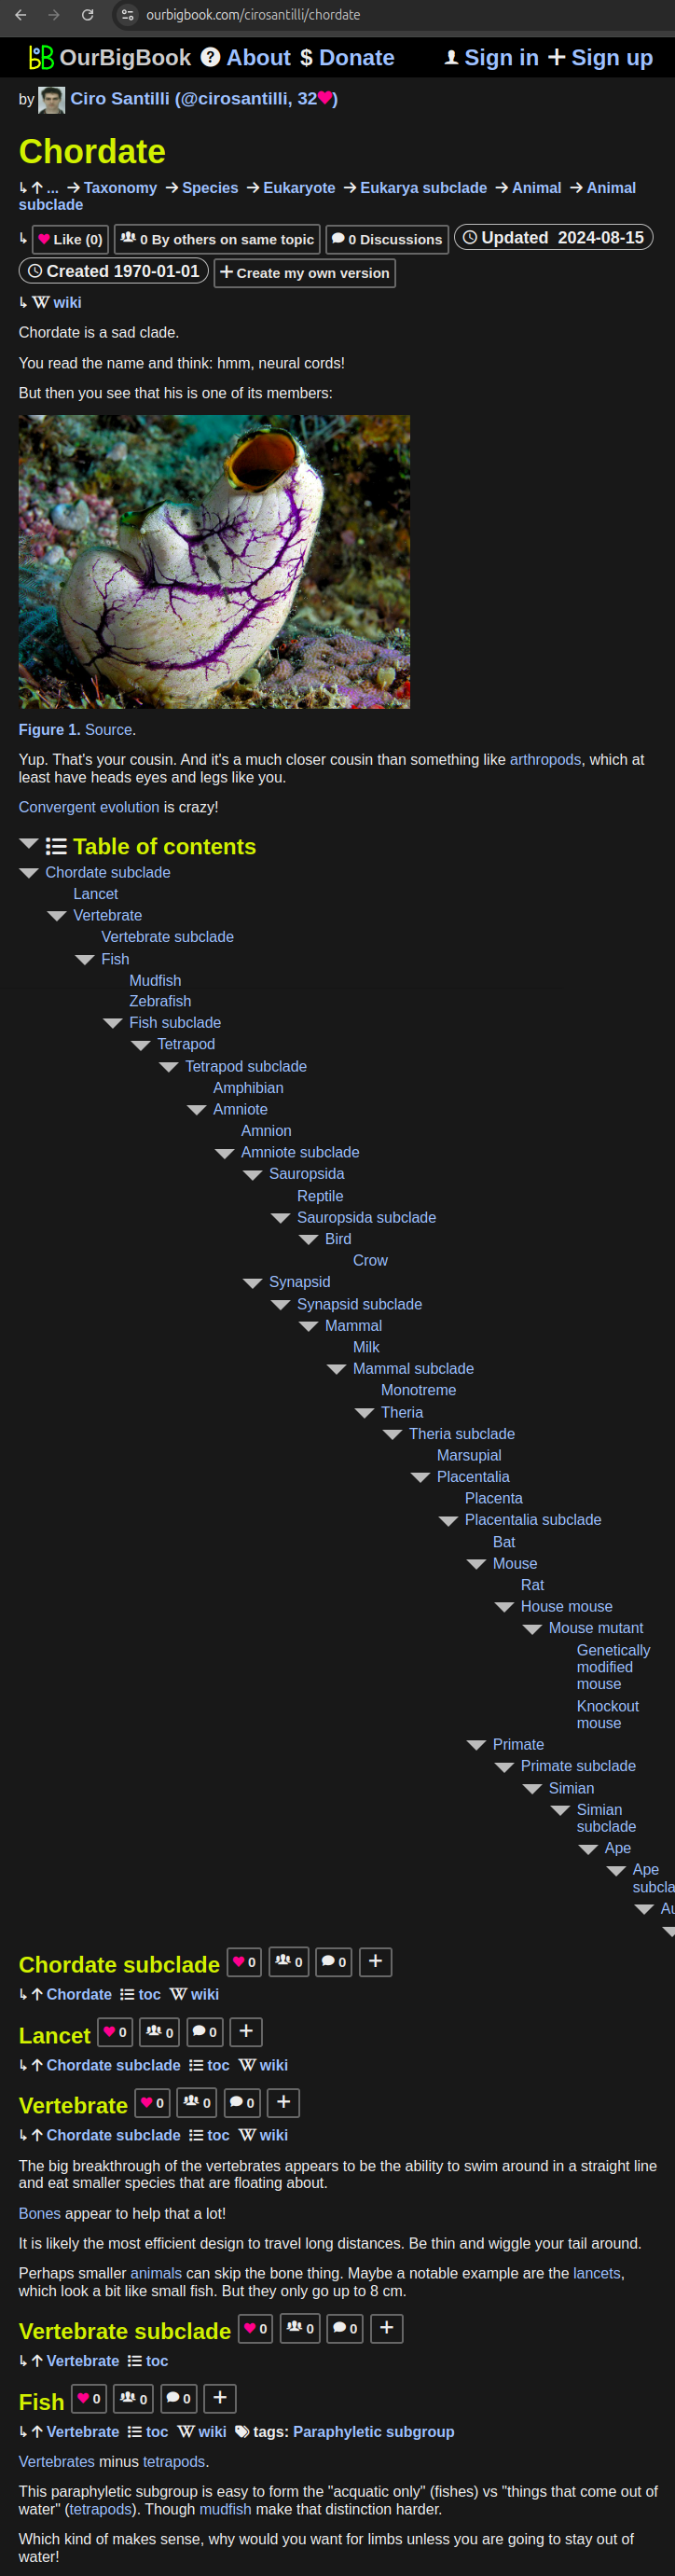
- Infinitely deep tables of contents:
All our software is open source and hosted at: github.com/ourbigbook/ourbigbook
Further documentation can be found at: docs.ourbigbook.com
Feel free to reach our to us for any help or suggestions: docs.ourbigbook.com/#contact