Topics (349k) Articles (361k) Users (417) Discussions (237) Comments (383) Files (12k) New article

Portfolio insurance is an investment strategy designed to protect a portfolio from significant losses while allowing for some upside potential. It typically involves the use of derivatives, such as options or futures, to hedge against market declines. The main goal of portfolio insurance is to provide a safety net in a declining market, ensuring that the value of the portfolio does not fall below a predetermined level.
Political risk refers to the potential for losses or adverse impacts on investments, business operations, or economic conditions resulting from political decisions, instability, or changes in government policy. This risk can arise from a variety of sources, including: 1. **Government Actions**: Changes in laws and regulations, expropriation of assets, or significant changes in trade policies can create risks for businesses operating in a country.
Open interest in the context of futures trading refers to the total number of outstanding contracts that are held by market participants at the end of a trading day. It represents the number of contracts that have been initiated but not yet liquidated, either by offsetting trades or by physical delivery. Here are some key points about open interest: 1. **Measure of Market Activity**: Open interest provides insights into the level of activity and liquidity in a particular futures market.
The Noisy Market Hypothesis is a concept that extends the traditional Efficient Market Hypothesis (EMH) by incorporating the idea that financial markets often operate under conditions of noise—random fluctuations and disturbances that can affect asset prices. While the EMH suggests that prices fully reflect all available information, the Noisy Market Hypothesis suggests that the presence of noise can lead to mispricing of assets, making markets less than perfectly efficient.
The concept of "No Free Lunch" in the context of optimization and machine learning refers to a theorem that states there is no one-size-fits-all algorithm that performs the best across all possible problems. Essentially, an algorithm that performs well on one class of problems may perform poorly on another. This is particularly relevant in optimization, where it highlights the need for choosing algorithms tailored to specific problem domains.
The No-Trade Theorem is an important concept in the field of finance and economics, particularly in the context of markets and information asymmetry. The theorem, which has roots in the theory of rational expectations and the theory of incomplete markets, states that if all market participants are rational and have common prior beliefs (i.e., they share the same initial beliefs about future states of the world), then there will be no trade in securities that depend solely on these common beliefs.
Neoclassical finance is a theoretical framework that applies principles and concepts from neoclassical economics to the field of finance. It focuses on the behavior of investors, markets, and the allocation of capital, emphasizing efficiency, rationality, and equilibrium. Here are some key aspects of neoclassical finance: 1. **Rational Investors**: Neoclassical finance assumes that investors are rational and make decisions based on utility maximization.
The "Neglected Firm Effect" refers to a phenomenon in financial markets where certain companies, particularly smaller or less well-known firms, tend to be undervalued or overlooked by investors and analysts. This lack of attention can result from a variety of factors, including limited research coverage, lower liquidity, or their status as firms in niche markets. Because these neglected firms do not attract the same level of scrutiny or investment as more widely followed companies, they might be priced lower than their intrinsic value.
The Mutual Fund Separation Theorem is a fundamental concept in modern portfolio theory that was notably formalized by economists such as James Tobin. The theorem essentially states that under certain conditions, investors can achieve optimal portfolios through a combination of a risk-free asset and a single mutual fund that contains a well-diversified portfolio of risky assets.
A monopoly price refers to the price set by a monopolist, a single seller in a market who has significant control over the price of a product or service. In a monopoly, the seller is the sole source of a particular product, allowing them to influence market prices without competitive pressures. Monopoly pricing occurs because the monopolist faces a downward-sloping demand curve, meaning that as the price increases, the quantity demanded decreases.
The Modigliani–Miller theorem (often abbreviated as the M&M theorem) is a foundational principle in corporate finance that was proposed by economists Franco Modigliani and Merton Miller in the 1950s. It addresses the relationship between the capital structure of a company (i.e., the mix of debt and equity financing) and its overall value. The theorem is based on several key assumptions, including perfectly efficient markets, no taxes, no bankruptcy costs, and rational behavior by investors.
Merton's portfolio problem refers to a framework developed by economist Robert C. Merton in the early 1970s, which addresses how an individual can optimally allocate their wealth between risky and risk-free assets in a continuous-time setting over a finite investment horizon. The problem is often situated within the context of utility maximization, where individuals seek to maximize their expected utility from terminal wealth.
The Master of Financial Economics (MFE) is a graduate-level program that combines elements of financial theory, economics, and quantitative analysis. It is designed to equip students with the skills and knowledge necessary to analyze and solve complex financial problems, as well as to understand the economic principles that underpin financial systems and markets. **Key Components of MFE Programs:** 1. **Financial Theory:** Students learn about asset pricing, investment strategies, and the behavior of financial markets.
The Markowitz model, also known as Modern Portfolio Theory (MPT), is a framework for constructing an investment portfolio in a way that maximizes expected return for a given level of risk, or alternatively minimizes risk for a given level of expected return. The model was developed by Harry Markowitz, who introduced it in his 1952 paper "Portfolio Selection.
A market trend refers to the general direction in which a market, asset, or financial instrument is moving over a certain period of time. It can indicate the overall sentiment of investors and traders regarding a particular market or asset and can be classified into three main types: 1. **Uptrend**: This is characterized by rising prices, where the market is moving upwards. An uptrend often indicates growing confidence and optimism among investors.
Market microstructure refers to the study of the processes and mechanisms through which securities, such as stocks, bonds, or derivatives, are traded in financial markets. It focuses on the way in which these markets operate at a granular level, encompassing the roles of different market participants, the trading systems and venues they use, and the impact of their interactions on the pricing and liquidity of securities.
A market correction refers to a short-term drop in the prices of securities, typically defined as a decline of 10% or more from a recent peak in a stock index or individual stock. Corrections are considered a natural part of the market cycle and occur after a significant rally or period of price increases. Market corrections can be triggered by a variety of factors, including: 1. **Economic Data**: Poor economic reports or forecasts can lead to decreased investor confidence and selling pressure.
A market anomaly refers to a situation where the price of an asset deviates from its expected or fair value, often contradicting the principles of efficient market hypothesis (EMH). The EMH posits that financial markets are "informationally efficient," meaning that asset prices fully reflect all available information. However, market anomalies suggest that there are instances where assets are mispriced and do not reflect all relevant information, leading to opportunities for investors to achieve abnormal returns.
The low-volatility anomaly refers to a paradox observed in financial markets where stocks or assets with lower volatility (i.e., less price fluctuation) tend to outperform their higher-volatility counterparts on a risk-adjusted basis. This runs counter to traditional finance theories, particularly the Capital Asset Pricing Model (CAPM), which posits that higher risk (volatility) should be associated with higher expected returns.
A Lookback option is a type of exotic financial derivative that allows the holder to "look back" over a predefined period of time and exercise the option based on the optimal price of the underlying asset during that period. This unique feature distinguishes Lookback options from standard options. There are two main types of Lookback options: 1. **Lookback with a maximum:** The payoff is based on the difference between the final price of the underlying asset and its minimum price during the life of the option.
Pinned article: Introduction to the OurBigBook Project
Welcome to the OurBigBook Project! Our goal is to create the perfect publishing platform for STEM subjects, and get university-level students to write the best free STEM tutorials ever.
Everyone is welcome to create an account and play with the site: ourbigbook.com/go/register. We belive that students themselves can write amazing tutorials, but teachers are welcome too. You can write about anything you want, it doesn't have to be STEM or even educational. Silly test content is very welcome and you won't be penalized in any way. Just keep it legal!
Intro to OurBigBook
. Source. We have two killer features:
- topics: topics group articles by different users with the same title, e.g. here is the topic for the "Fundamental Theorem of Calculus" ourbigbook.com/go/topic/fundamental-theorem-of-calculusArticles of different users are sorted by upvote within each article page. This feature is a bit like:
- a Wikipedia where each user can have their own version of each article
- a Q&A website like Stack Overflow, where multiple people can give their views on a given topic, and the best ones are sorted by upvote. Except you don't need to wait for someone to ask first, and any topic goes, no matter how narrow or broad
This feature makes it possible for readers to find better explanations of any topic created by other writers. And it allows writers to create an explanation in a place that readers might actually find it.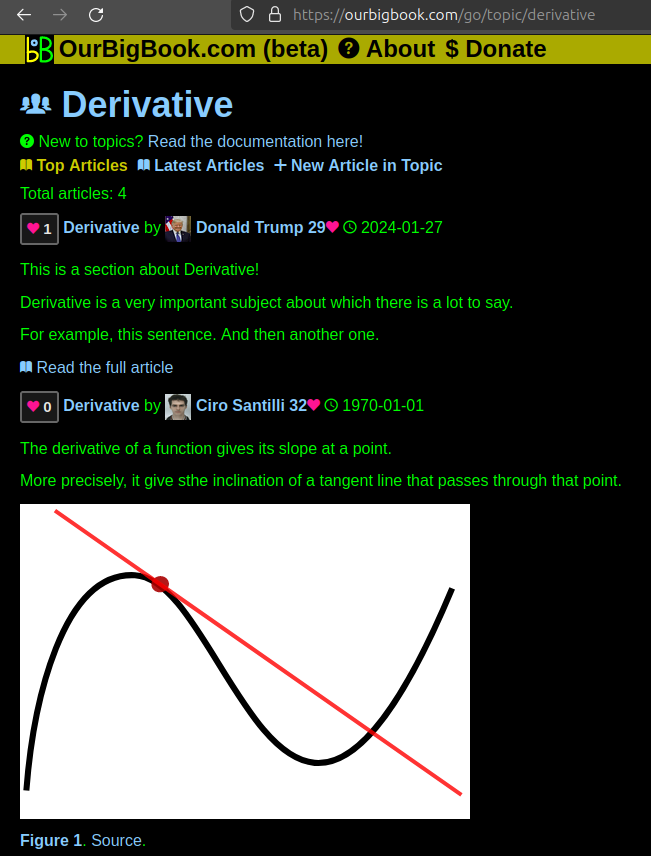
Figure 1. Screenshot of the "Derivative" topic page. View it live at: ourbigbook.com/go/topic/derivativeVideo 2. OurBigBook Web topics demo. Source. - local editing: you can store all your personal knowledge base content locally in a plaintext markup format that can be edited locally and published either:This way you can be sure that even if OurBigBook.com were to go down one day (which we have no plans to do as it is quite cheap to host!), your content will still be perfectly readable as a static site.
- to OurBigBook.com to get awesome multi-user features like topics and likes
- as HTML files to a static website, which you can host yourself for free on many external providers like GitHub Pages, and remain in full control
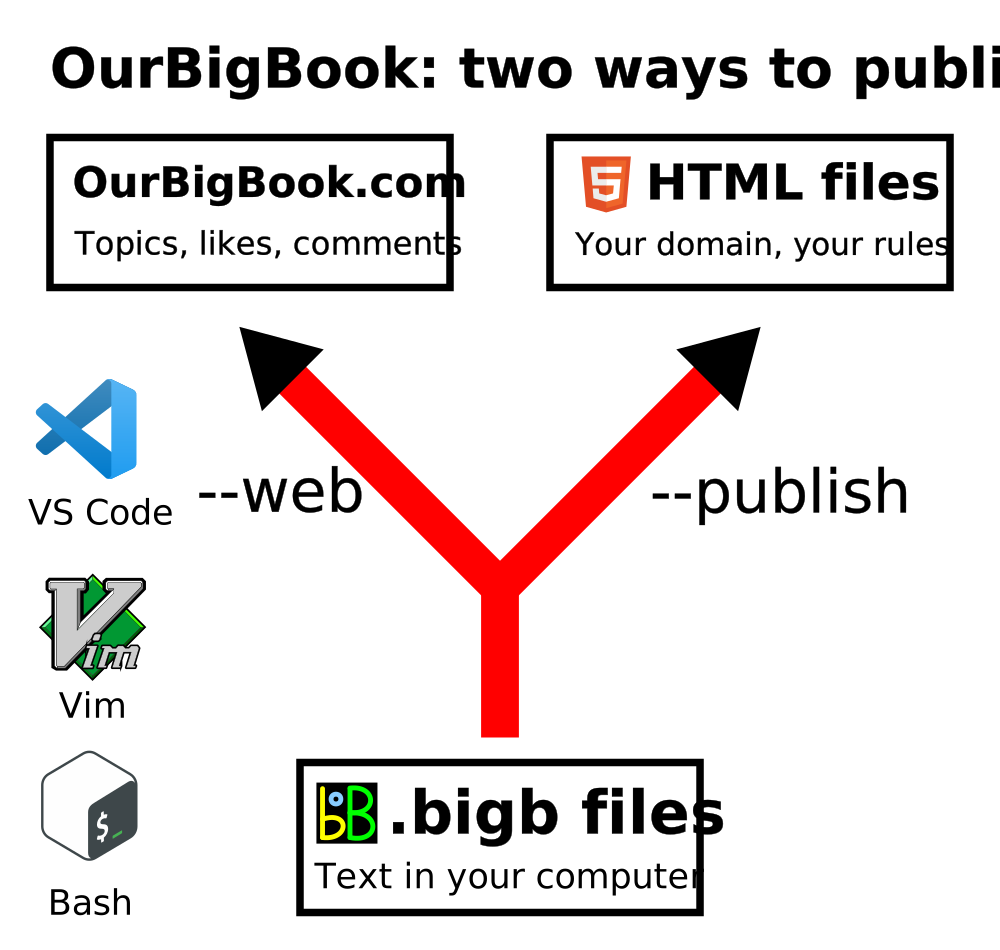
Figure 2. You can publish local OurBigBook lightweight markup files to either OurBigBook.com or as a static website.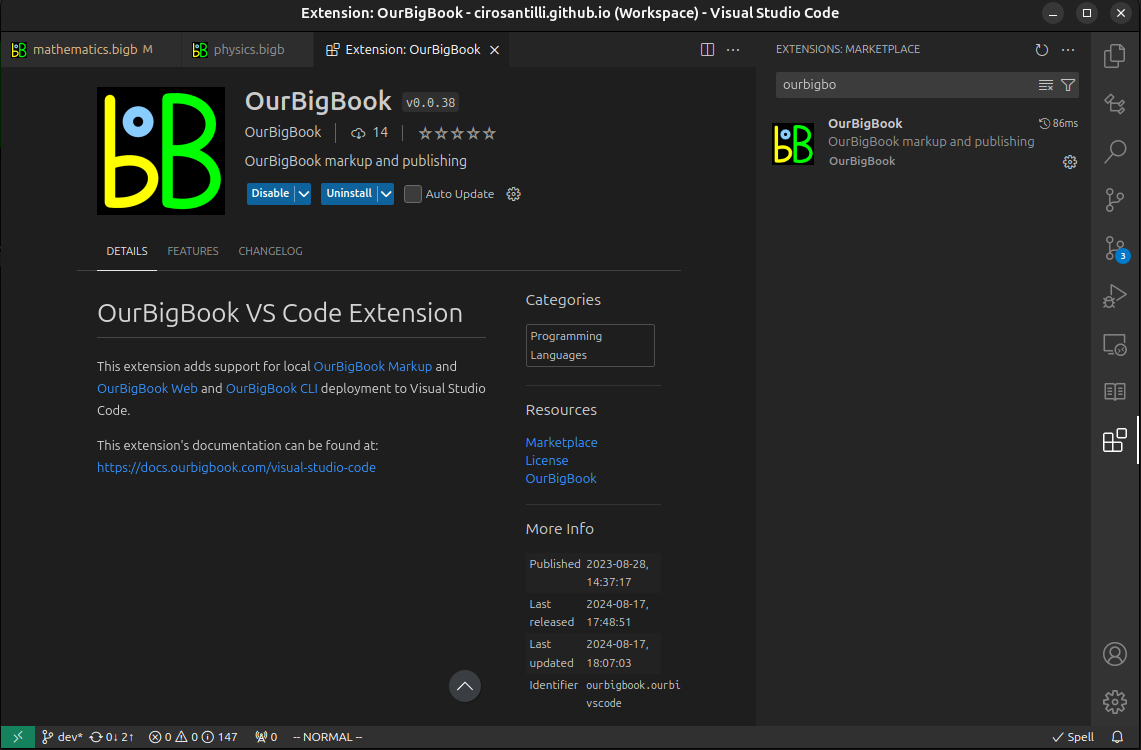
Figure 3. Visual Studio Code extension installation.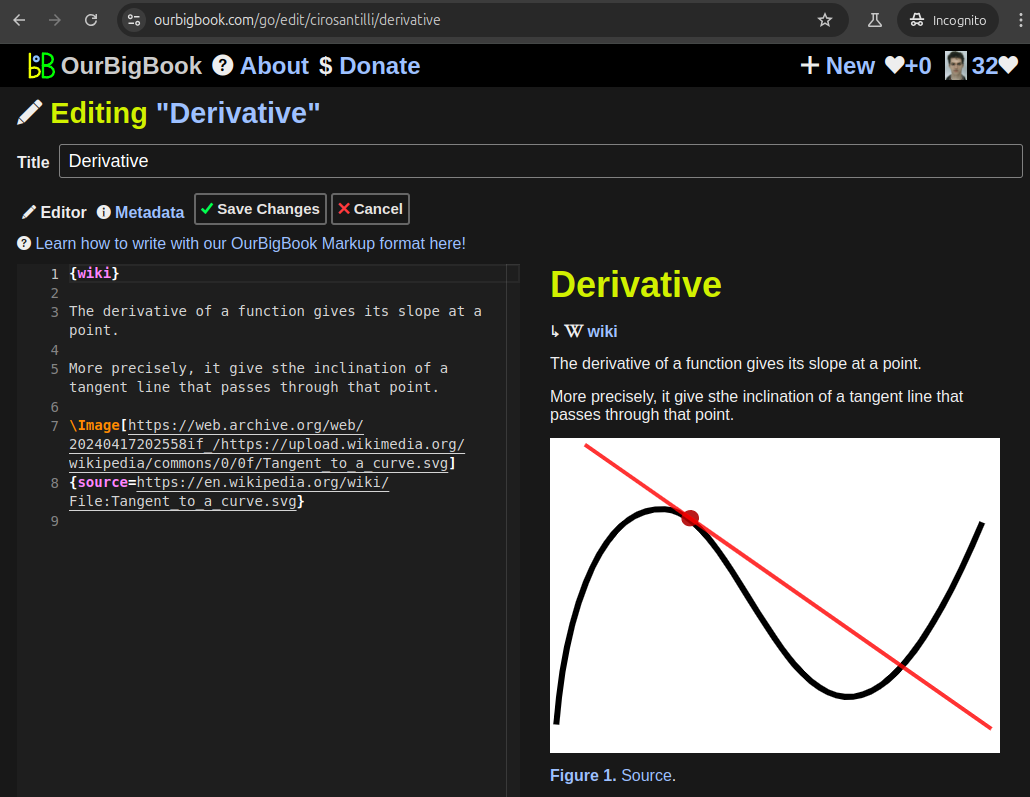
Figure 5. . You can also edit articles on the Web editor without installing anything locally. Video 3. Edit locally and publish demo. Source. This shows editing OurBigBook Markup and publishing it using the Visual Studio Code extension. 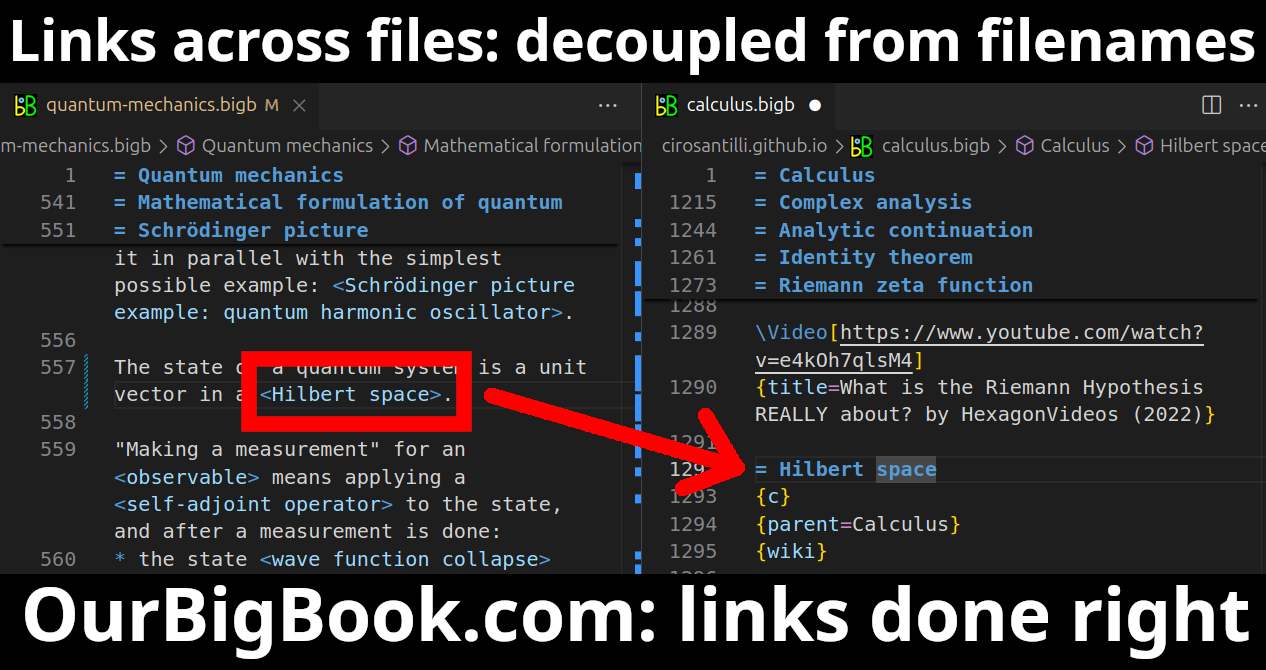
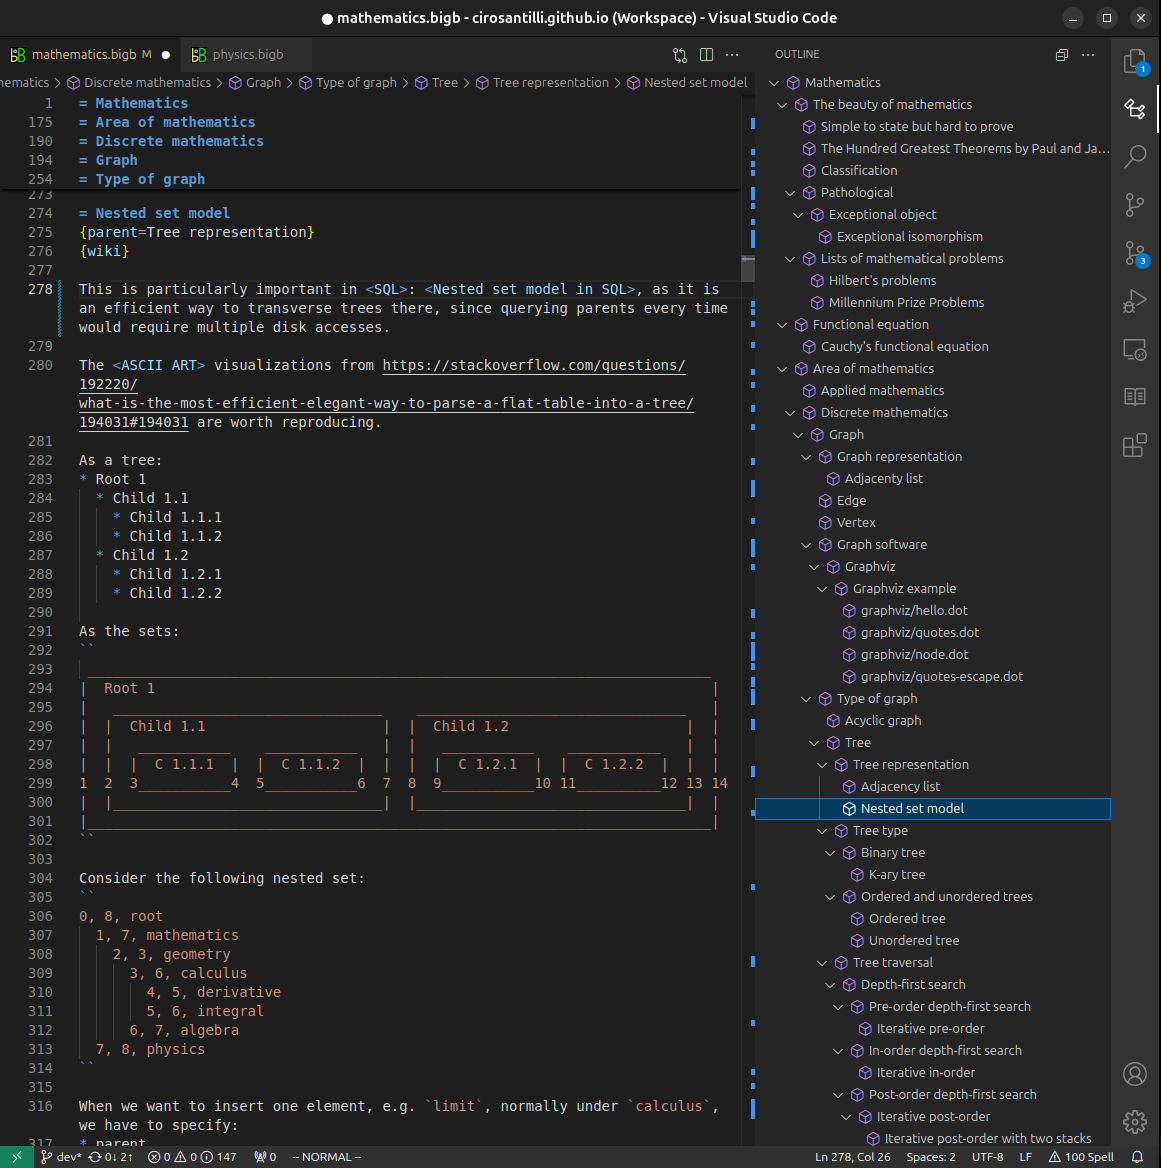
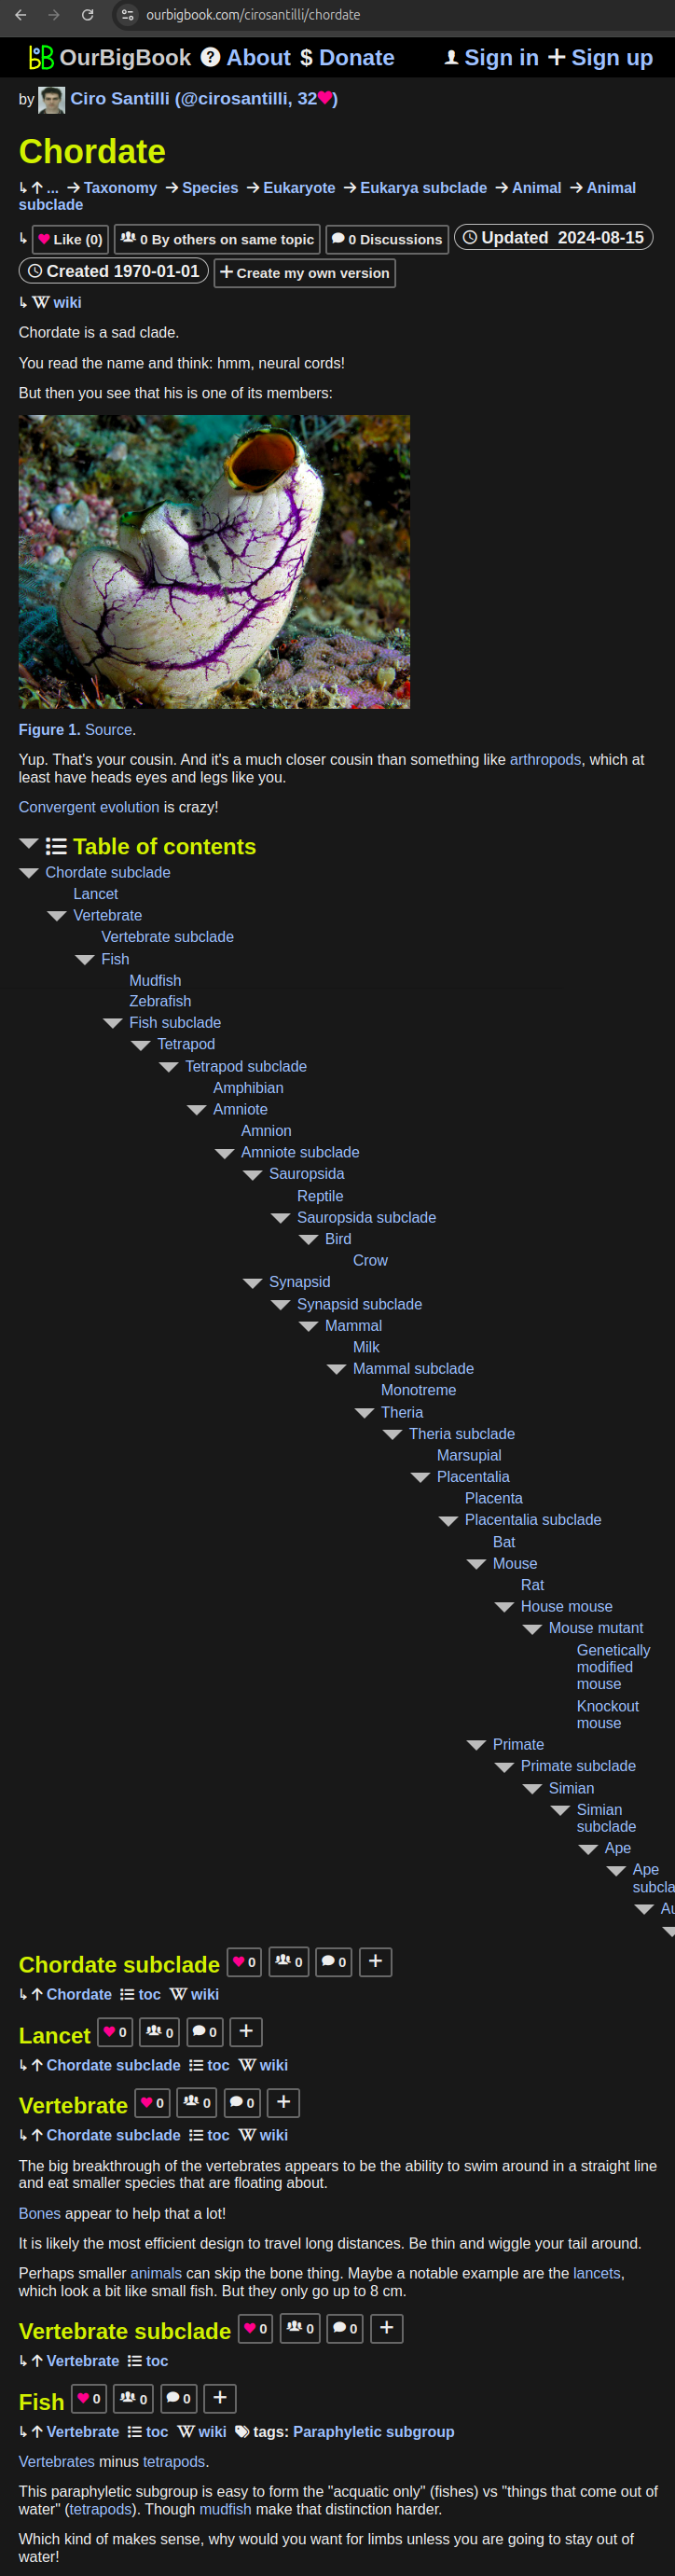
- Infinitely deep tables of contents:
All our software is open source and hosted at: github.com/ourbigbook/ourbigbook
Further documentation can be found at: docs.ourbigbook.com
Feel free to reach our to us for any help or suggestions: docs.ourbigbook.com/#contact