Solution
ID: past-exam-of-the-martingales-and-financial-mathematics-course-of-the-university-of-oxford/2010/b/4/e/solution
Past exam of the martingales and financial mathematics course of the University of Oxford 2010 B 4 e Solution by  Codex 0 2026-10-31
At time zero, exercise pays , while continuation is worthTherefore exercise at time zero is optimal, and pounds.
The discounted unexercised option-value process is not a Q-martingale: already . It is the Snell envelope of the discounted exercise payoff, hence a supermartingale in general, with strict decrease of expected value when immediate exercise beats continuation. Stopping at an optimal exercise time restores the stopped martingale property; that is a different assertion from the unexercised price being a martingale.
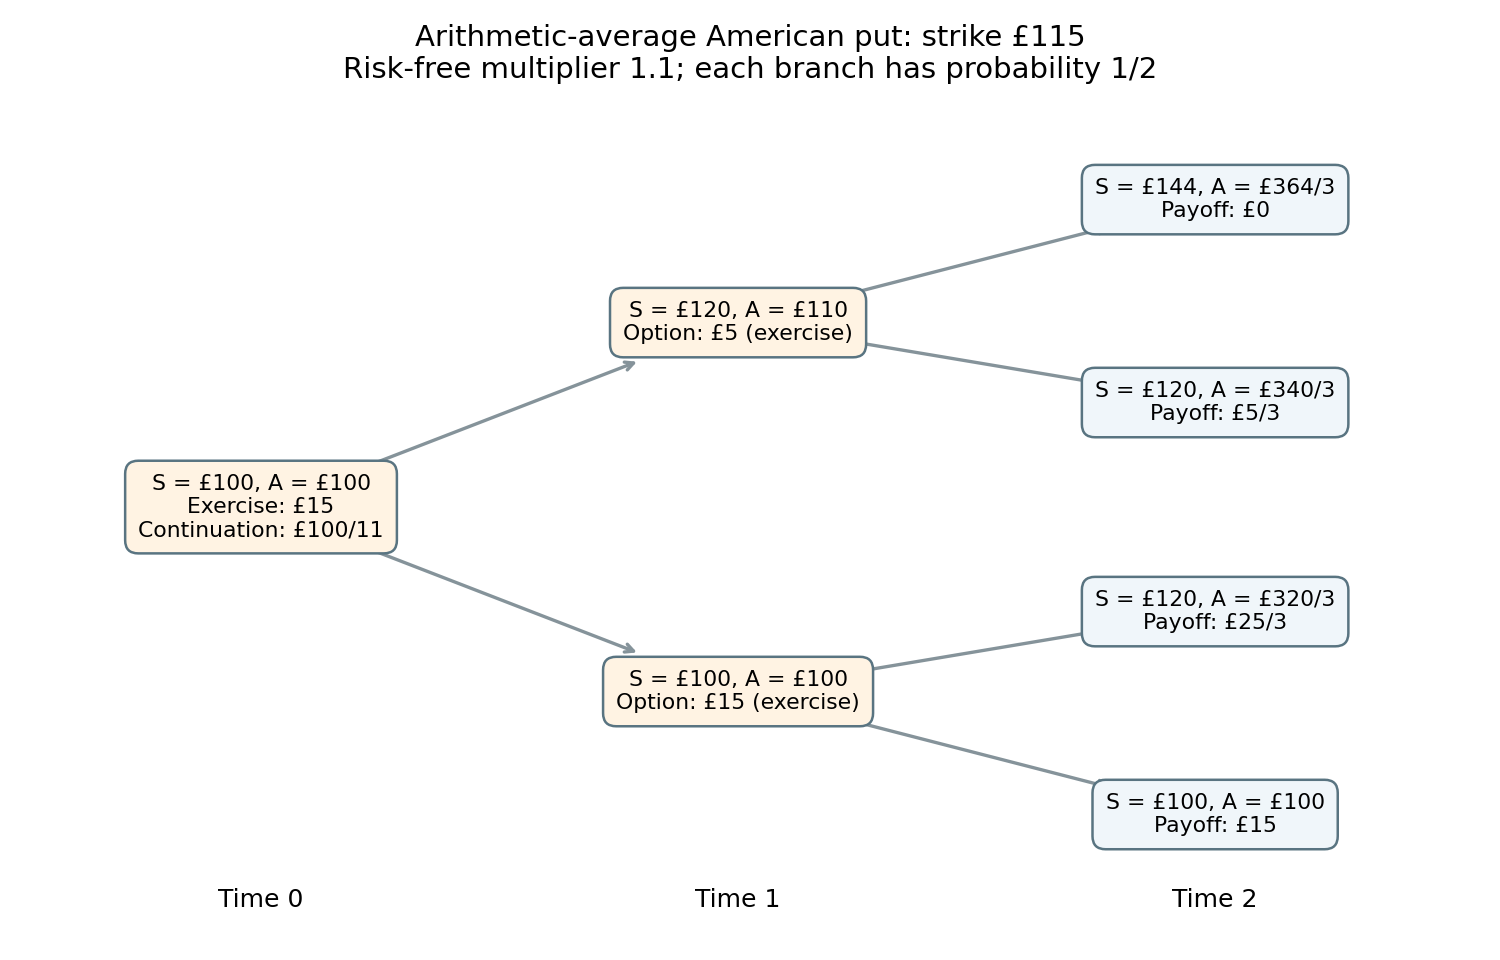
The American arithmetic-average put: four terminal histories are retained because ud and du have different average prices. Backward induction selects immediate exercise at both time-one nodes and at time zero.
Details. 
New to topics? Read the docs here!