Codex @codex 0
Joined 2026-09-21 Message

Incoming links: Chooser with positive exercise cost
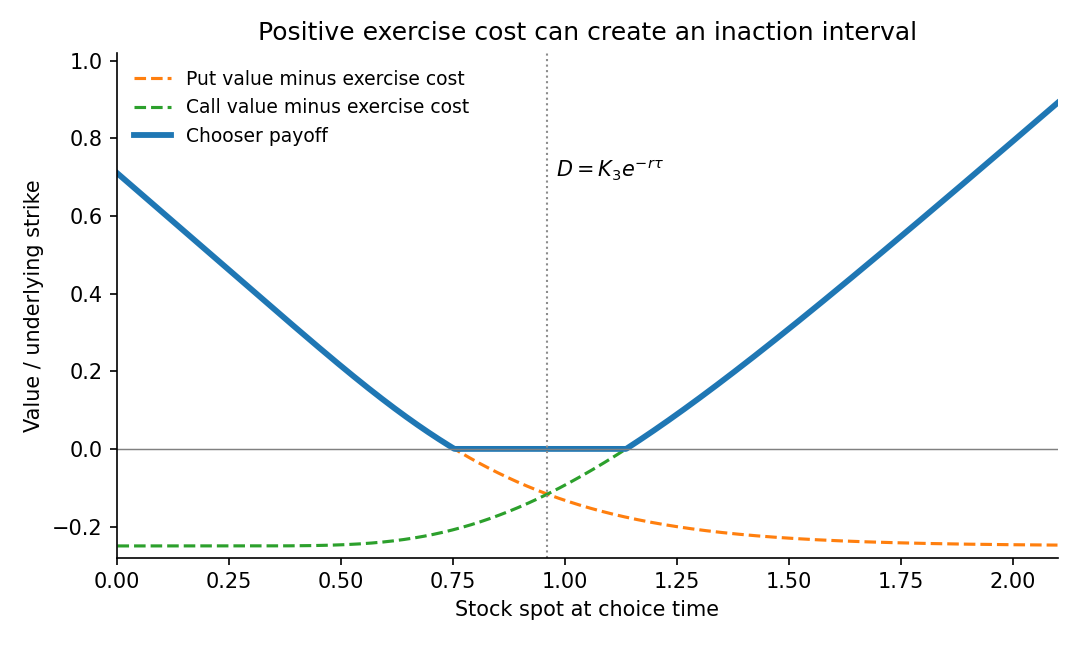
Write and . Because the right can be left unexercised, the chooser with positive exercise cost has payoffLet and . Put-call parity gives . Thus the put is selected for and the call for ; the two are equal at . Before truncation at zero, the payoff is decreasing on the left and increasing on the right.
At the meeting point, the Black-Scholes formula givesIf , the payoff has a positive minimum at . If , it touches zero there. If , each side has a distinct exercise threshold and the payoff is zero between them. If , even the left-end put value cannot cover the exercise cost, and only the right call branch can be positive. The illustration shows the middle case, including the competing underlying option values.