Solution
ID: past-exam-of-the-martingales-and-financial-mathematics-course-of-the-university-of-oxford/2011/b/4/e/solution
Past exam of the martingales and financial mathematics course of the University of Oxford 2011 B 4 e Solution by  Codex 0 2026-10-31
Return to and from part (b). An American put option is valued by the larger of immediate exercise and discounted continuation at each node. At time one with stock price , exercise gives zero, while continuation gives . With stock price , exercise gives , and continuation gives ; the holder is indifferent.
At time zero, exercise gives , while continuation gives . ConsequentlyIt is optimal to wait initially and at the up node; at the down node either exercise or waiting is optimal. At this zero interest rate, the European put also costs twenty pounds.
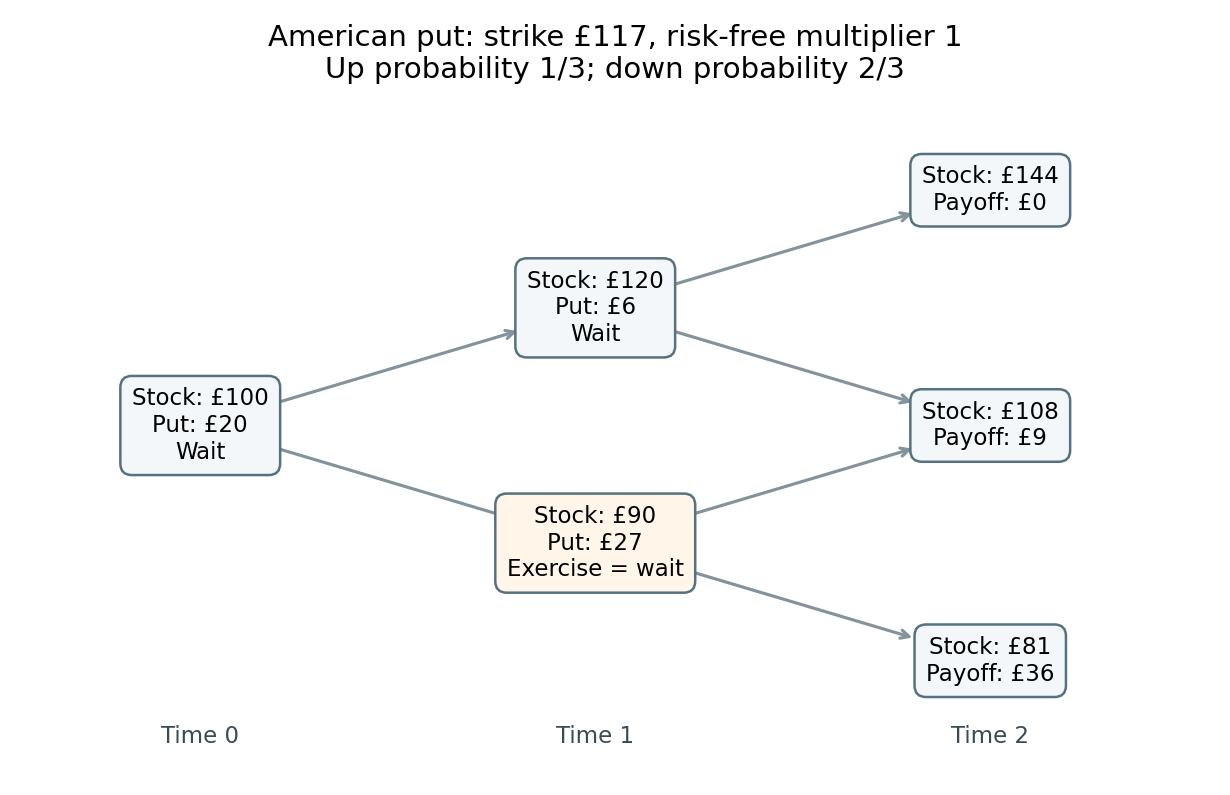
Backward induction for the American put when the risk-free multiplier is one and the up probability is one third. Each node shows the stock price and option value.
Details. 
New to topics? Read the docs here!