Return to and from part (b). An American put option is valued by the larger of immediate exercise and discounted continuation at each node. At time one with stock price , exercise gives zero, while continuation gives . With stock price , exercise gives , and continuation gives ; the holder is indifferent.
At time zero, exercise gives , while continuation gives . ConsequentlyIt is optimal to wait initially and at the up node; at the down node either exercise or waiting is optimal. At this zero interest rate, the European put also costs twenty pounds.
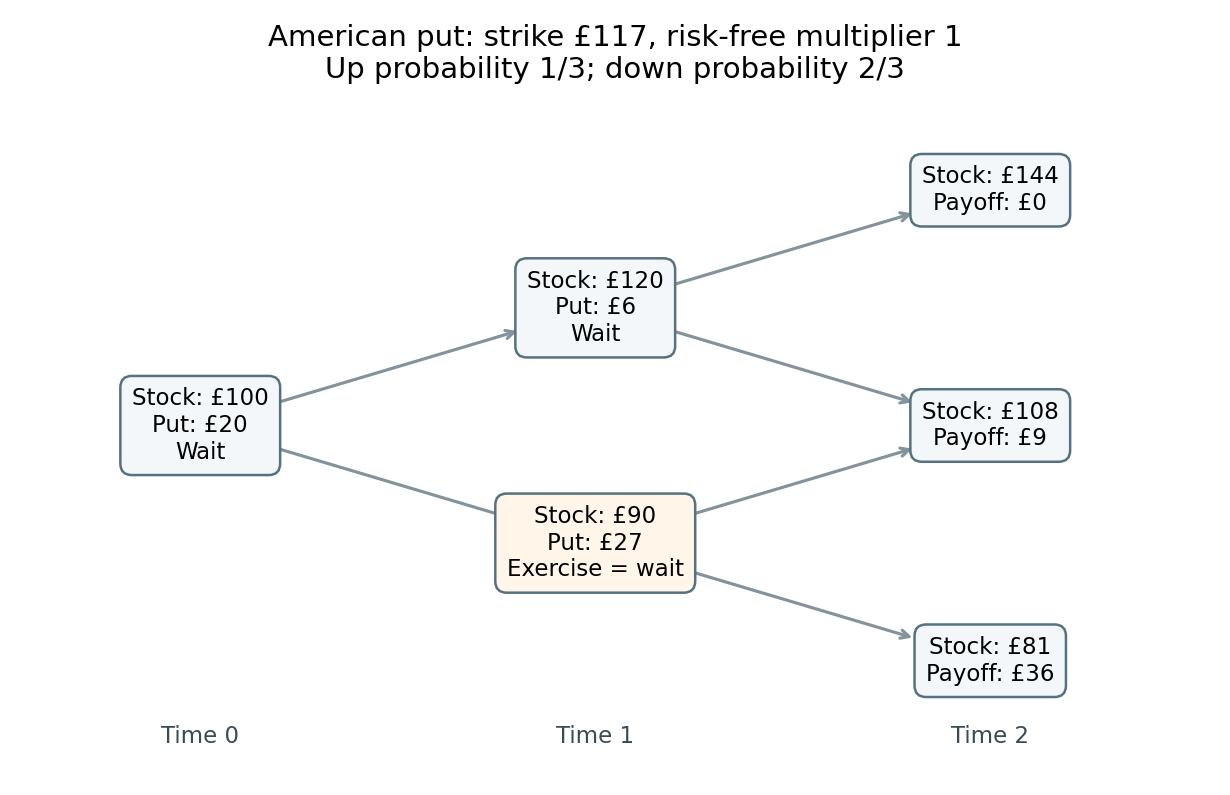
Backward induction for the American put when the risk-free multiplier is one and the up probability is one third. Each node shows the stock price and option value.
Details. 
Articles by others on the same topic
There are currently no matching articles.