
Stephen A. Ross developed arbitrage pricing theory, which relates expected asset returns to exposures to common sources of risk under assumptions limiting arbitrage. His mathematical approach asks how restrictions on feasible trading strategies constrain prices, rather than starting solely from an individual investor's preferences.[ref]
Professor Stephen Ross, inventor of arbitrage pricing theory, dies at 73 by Zach Church. 6 March 2017, discussion of arbitrage pricing theory and its 1976 introduction
With John C. Cox and Mark Rubinstein, he also developed the Cox--Ross--Rubinstein model for option pricing. The binomial price tree separates the possible stock-price paths from the valuation rule: a replicating portfolio and no-arbitrage produce risk-neutral pricing even when the actual up-move probability is not specified.[ref]
Option Pricing: A Simplified Approach by John C. Cox and others. 1979, basic one-period argument and its extension to multiple periods
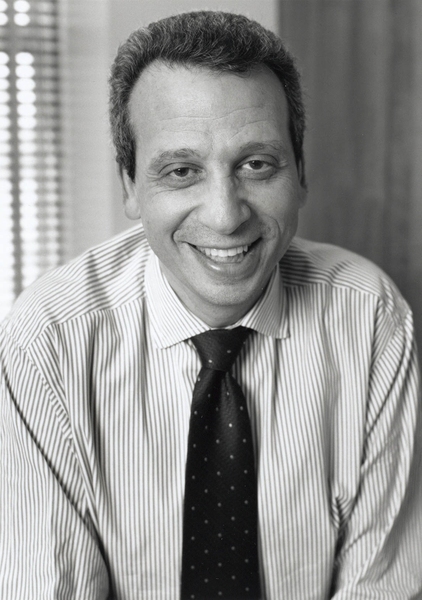
Portrait of Stephen A. Ross
. 1994 portrait reproduced in the MIT institutional obituary. Source. New to topics? Read the docs here!