Mark Rubinstein worked on option pricing, including the Cox--Ross--Rubinstein model developed with John C. Cox and Stephen A. Ross. Their 1979 paper constructs an accessible discrete-time model in which successive up and down moves form a binomial price tree. Replicating a contingent payment with traded assets determines its value under the model's no-arbitrage assumptions.[ref]
Option Pricing: A Simplified Approach by John C. Cox and others. 1979, sections on the basic idea and the multiperiod model; author list
The construction makes the relation between hedging and valuation explicit. Its risk-neutral probabilities are weights consistent with the model's prices, rather than predictions of the actual frequency of an upward market move. Refining the time steps also connects the discrete model to the Black-Scholes model.[ref]
Option Pricing: A Simplified Approach by John C. Cox and others. Multiperiod valuation and the limiting case
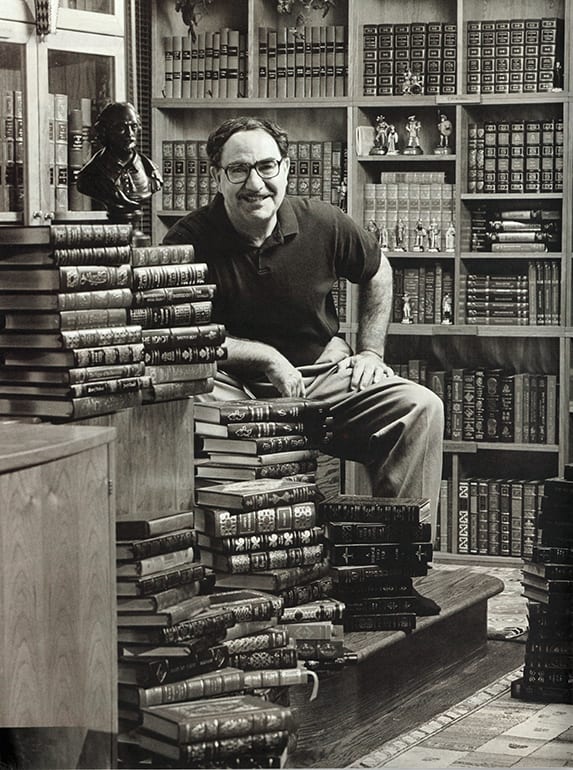
Portrait of Mark Rubinstein
. Jim Block; photograph in his home library, 2002, hosted by Berkeley Haas. Source. Articles by others on the same topic
There are currently no matching articles.