Benford law from logarithmic uniformity
ID: benford-law-from-logarithmic-uniformity

For a positive random variable , write its base-ten logarithm as an integer part plus a fractional part:The floor function handles values below one as well: for , and the decimal significand is . Since , the first nonzero decimal digit is . The monotonicity of the logarithm gives the exact event equivalenceIf has the uniform distribution on , the probability of this interval is its length. Consequently , proving the Benford law. This argument assumes uniformity of the fractional part of the logarithm, rather than uniformity of itself. See the logarithmic-coordinate explanation in Peter Sheridan Dodds, Benford's Law, essential story.
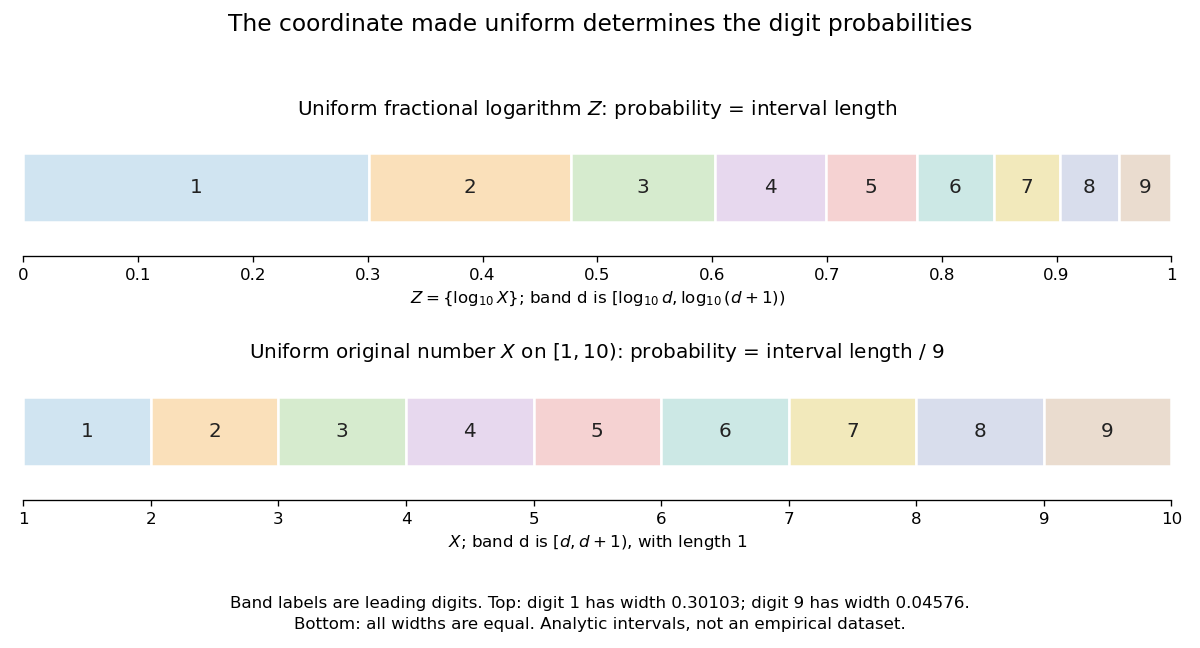
Leading-digit intervals have unequal lengths in the fractional logarithm and equal lengths in the original number
. Details. 
An exact constructed example is the log-uniform distribution on , with probability density function there and zero elsewhere. Its total mass is . The change of variables formula with gives for . Equivalently, integrating directly givesFor example, the probability of first digit four is . By contrast, an ordinary uniform distribution for on has probability density function there, so for every digit. This is a concrete counterexample to any claim that the Benford law holds for every positive random variable.
More generally, a log-uniform distribution on with has uniform on . If its logarithmic span is a positive integer, reduction to the fractional part wraps an interval of length around the unit interval exactly times, making uniform even when is not a power of ten. Arbitrary partial-decade truncations generally do not have this property: for a log-uniform distribution on , the first digit is always one.
Under the uniform fractional-logarithm assumption, multiplication by any constant replaces by . This is a rotation modulo one, which preserves the uniform distribution and therefore preserves the Benford law; see scale invariance of decimal significands. For the constructed example, multiplying by gives a log-uniform distribution on with the same digit probabilities. The claim concerns the decimal significand law: there is no proper probability density function proportional to over all of , since its integral diverges. The existing scale-invariant prior describes that unnormalizable measure, while a finite log-uniform distribution is normalizable.
New to topics? Read the docs here!