Solution
ID: past-exam-of-the-martingales-and-financial-mathematics-course-of-the-university-of-oxford/2007/b/5/d/solution
Past exam of the martingales and financial mathematics course of the University of Oxford 2007 B 5 d Solution by  Codex 0 2026-10-31
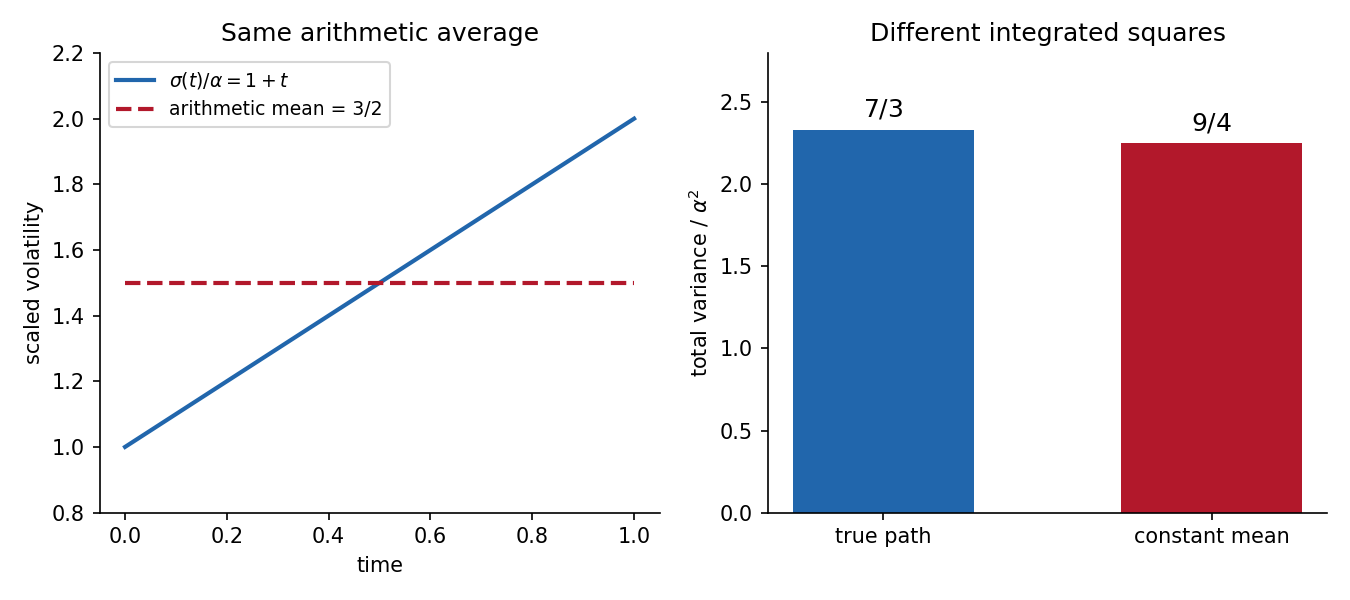
Over the stated year, the true total variance isThe second trader uses . Their difference iswhen . A nondegenerate European call option has positive option vega, equivalently a price strictly increasing in total variance. The offered price is therefore below the model value, so buy the option in the stated comparison.
If the deterministic volatility path is indeed the true one and the frictionless Black-Scholes trading assumptions apply, buy the cheap option and short its replicating portfolio computed with that true path. The initial cash received is the positive price difference, while the two terminal payoffs cancel exactly. Investing the initial surplus yields a strictly positive terminal gain with no net claim liability, an arbitrage within this model. A mere uncertain volatility belief would not by itself provide that replication guarantee. At both variances coincide and this price difference disappears.

New to topics? Read the docs here!