A European call option gives its holder the right, without an obligation, to buy one unit of an underlying financial asset at the strike price on the expiry date . European describes exercise timing, not geography: exercise is allowed only at . Here the underlying is one stock share, is its price at expiry, and the financial payoff is expressed as a cash amount. Physical exercise delivers a share against payment of ; immediate resale gives the same net amount under the assumed frictionless market.
The holder exercises only when buying at the strike price is advantageous. Writing for the positive part, the terminal financial payoff isThe European call option is a reusable building block for claim replication: its financial payoff is zero below the strike price and rises by one unit for each unit of stock price above it. The corner at lets combinations of European call options construct other payoff shapes, as in static replication on a finite terminal support.
For strike price , the following are deterministic calculations conditional on each displayed terminal stock price. They assign no probabilities to the three scenarios. The European put option has the opposite exercise right and the financial payoff .
| Terminal stock price | European call option | European put option | Difference |
|---|---|---|---|
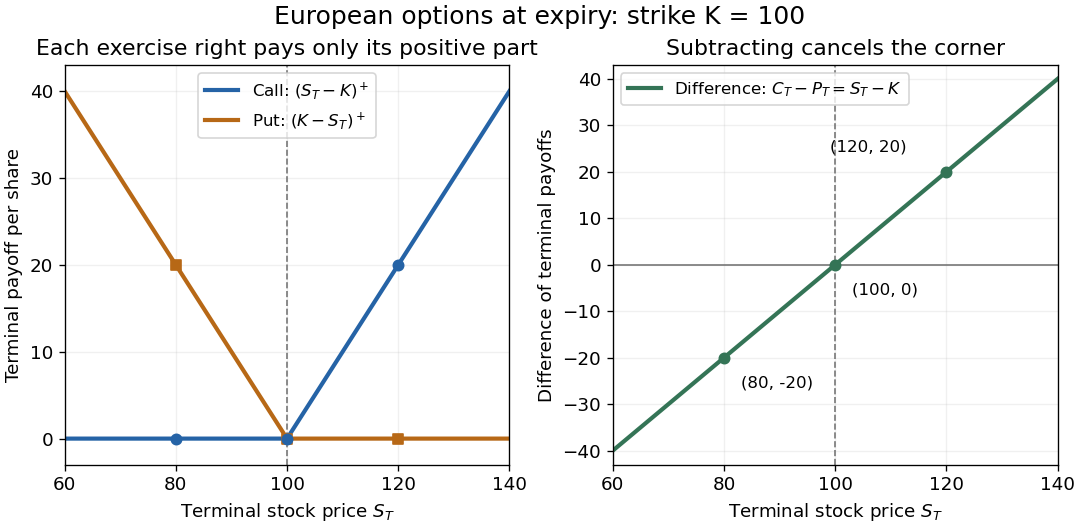

A financial payoff excludes the initial contract price. If the illustrative European call option costs , its financial payoff at is , and subtracting its initial cost gives . If that cost is instead borrowed for one year at the constant continuously compounded interest rate , the terminal net amount is . At or , the corresponding net amount is . Keeping all cash amounts at the same date avoids confusing a financial payoff with a financed gain.
Robert Shiller's Options Markets lecture, Yale ECON 252 (2011) introduces these exercise rights and payoff shapes.
A down-and-out European call pays the usual European call option payoff only if a lower barrier has not been hit before maturity. In the zero-interest, zero-dividend Black-Scholes model, for , its value is . This follows from reflection of the drifted logarithmic price killed at the barrier.
For a down-and-out European call with barrier equal to strike, zero interest and no dividends, hold one share and borrow the strike until barrier hitting or maturity. At continuous hitting the share price is exactly the debt, so liquidating leaves zero; on survival the portfolio pays . Hence the contract has value and delta one before knock-out. The pathwise replication works beyond constant-volatility Black-Scholes model, but can fail through downward jumps or execution gaps, and nonzero carry, transaction costs or discrete monitoring require changes.
For any fixed maturity, a European call option price is convex in its strike because is convex for every terminal stock value . Specifically, for , . Multiplication by the positive discount factor and expectation under the pricing measure preserve this inequality. This also explains why a violation of convexity creates a butterfly-spread arbitrage.
If the bank account is positive and nondecreasing and is a martingale under an equivalent martingale measure , then for the European call price is nondecreasing in . Put . For , and hence . Conditional convexity gives . Taking expectations and multiplying by proves the claim. The result is not generally true for negative strikes: with and , a negative-strike call costs , decreasing in maturity.
For and , integrate over to obtain the displayed identity. Tonelli theorem then expresses the moment of a nonnegative random variable as the same integral of expected call payoffs, even when the moment is infinite. This is a static representation across strikes rather than a dynamic replicating strategy in a restricted finite-asset market.
For and , minimize . Its minimum occurs at , giving the sharp constant. Taking expected values yields a uniform bound on from a finite moment of order .
For and , split the static call integral at a fixed positive strike. The first moment bounds the integrand near zero; polynomial call decay controls the integral at infinity for . The endpoint can fail, as shown by a Pareto distribution with survival exponent .
In a zero-interest one-period market with a continuous terminal stock law under a pricing measure, implies and . Thus a full differentiable call curve determines its pricing density. A finite collection of strikes generally does not. With a deterministic nonunit discount factor, divide the call curve by that factor before recovering the probability density.
Finitely many call prices impose finitely many payoff-moment constraints. They do not require a continuous terminal law or determine prices of arbitrary new claims. For example, , terminal values and , and upper-state probability give , matching the power curve. A payoff vanishing on these two states must cost zero, whereas integration against the power curve's strictly positive density can assign it a positive cost. A pricing density intended for arbitrary claims must be compatible with an equivalent law on the actual state space.
For , the zero-interest curve has positive second derivative . Its mass and first moment are both one, and . It prices an integrable payoff by when this law is equivalent to the physical terminal stock law, or on a canonical model with this pricing law. Finite-strike consistency alone is insufficient for that equivalence.
The midpoint butterfly buys half a call at each outer strike and sells one at the middle strike. Convexity of makes its terminal payoff nonnegative. A violation of the displayed price inequality makes its cost negative and creates arbitrage. The payoff is triangular between the outer strikes and zero elsewhere.
Buying the lower-strike call and selling the higher-strike call gives a strictly negative initial cost and terminal payoff . Hence an arbitrage-free call-price curve is decreasing in strike. The positive initial receipt may be consumed immediately or invested in cash.
A positive one-period martingale deflator applied to gives . If both strict payoff regions and have positive probability, then and , proving the strict lower bound. No normalization of the positive pricing variable is needed.
The Mellin transform of call prices can be inverted along a vertical contour with real part : . A finite exponential moment at and the quadratic denominator give absolute convergence.
For a martingale with increments in , European call option prices satisfy . At positive-probability states, the variance and the upward/downward conditional transitions are determined by this identity; transitions at zero-probability states cannot be recovered.
For an integer-valued underlying with European call option prices , the second strike difference equals . It is the discrete counterpart of recovering a payoff probability distribution from strike derivatives.
At a fixed maturity, no arbitrage makes a European call price nonincreasing in its strike because the lower-strike payoff dominates the higher-strike payoff state by state.
When terminal stock price takes finitely many ordered values, every payoff function of that price can be represented on the support by cash plus a linear combination of adjacent-strike call spreads.
The pathwise identity turns a squared-increment claim into a terminal-square claim and predictable stock gains. On integer terminal support , , so a static call strip plus a dynamic stock hedge replicates the claim.
Put-call parity fixes the price difference between a European call option and a European put option on the same underlying stock, with the same strike price and expiry . Assume no dividends or other payments from the stock before or at expiry, a known constant continuously compounded interest rate , and a frictionless market. Borrowing and lending are available at that same interest rate; short selling of the stock, European call option, European put option, and zero-coupon bond is permitted. Settlement is certain, and the buy-and-hold portfolios below may be held until without interim funding restrictions or forced liquidation. These assumptions exclude transaction costs, taxes, borrowing fees, and execution or settlement risks from the arbitrage argument.
At expiry, the two positive parts cancel their corners:Thus a European call option and a short European put option together have the same terminal financial payoff as one stock share with a debt of . A particularly readable claim replication uses two portfolios with nonnegative terminal amounts: portfolio A holds one European call option and a risk-free zero-coupon bond paying at ; portfolio B holds one European put option and one stock share. The zero-coupon bond costs today, since the discount factor is . There are no intermediate cash flows. For every terminal stock price,For the strike price , even the following very different outcomes leave the two portfolios equal:
| Terminal stock price | A: European call option + zero-coupon bond | B: European put option + stock |
|---|---|---|
The law of one price forces in this setting: otherwise buy the cheaper portfolio and sell the more expensive portfolio using short selling. Their terminal obligations cancel in every scenario, while the initial price difference can grow in the bank account. Hence absence of arbitrage givesWith a constant per-period interest rate over discrete periods, the same reasoning gives . This is a different compounding convention; is not the continuously compounded interest rate .
For an illustrative stock price , strike price , expiry one year away, interest rate per year, and given European call option price , put-call parity requiresBoth portfolios therefore cost approximately . The inputs specify no stock price dynamics: is supplied for illustration, not calculated from the Black-Scholes model. Put-call parity determines the European put option price conditional on that European call option price; it does not determine both prices by itself. At zero interest rate, the same and give the exact result .
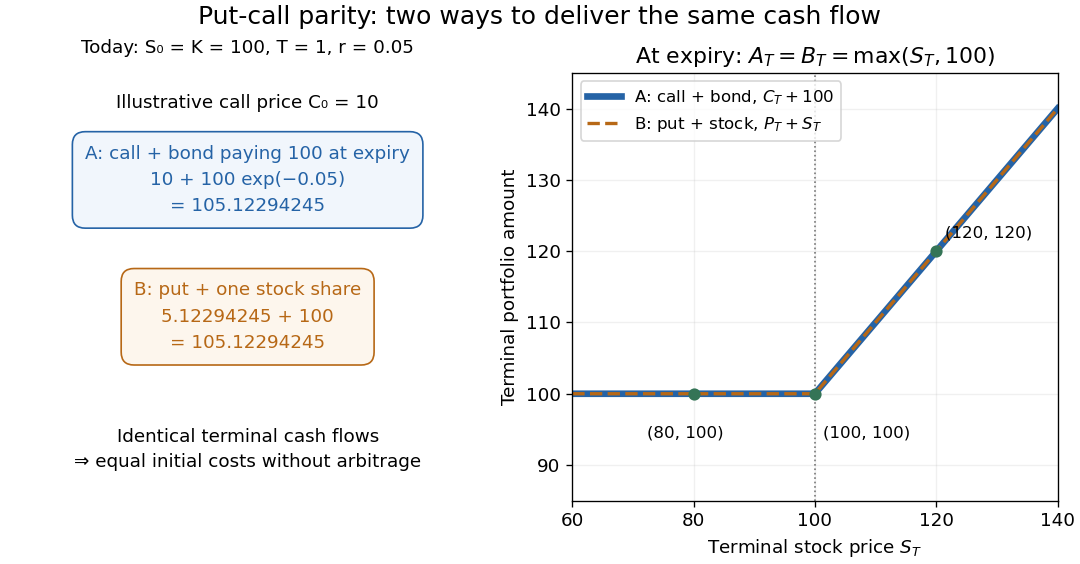
Two portfolios with identical terminal cash flows and equal initial costs under put-call parity
. Details. 
To compute both directions of arbitrage, keep all the preceding inputs except the quoted European put option price. If it is , portfolio B costs while portfolio A costs . Buy A, sell B, and place the initial surplus in the bank account. At expiry, A and the obligations from selling B cancel exactly, leaving in every scenario. If the European put option instead costs , buy B for and sell A for ; the initial surplus is approximately , growing to . Both constructions start with zero external capital. They are model calculations under the stated frictionless market assumptions.
The beauty of put-call parity is that uncertain individual financial payoffs produce an exact relation between today's prices. No forecast of the terminal stock price and no probability distribution are needed. It provides a consistency check and lets claim replication exchange one contract for a combination of others. Dividends introduce extra cash flows, and American put options can be exercised early, so the displayed European equality cannot simply be transferred to those contracts. K. Foster's [ref]
https://kfoster.ccny.cuny.edu/classes/spring2010/eco275/lecturenotes5.html. CCNY lecture notes on option values (2010), Put-Call Parity section
explain the matching portfolios; Jun Pan's [ref]https://www.mit.edu/~junpan/Jun_Pan_Teaching_Notes.pdf. MIT Financial Markets teaching notes, Arbitrage Pricing and Dynamic Replication section (PDF p. 130)
discuss put-call parity and its dividend adjustment.An original modern research source is Hans R. Stoll's [ref]
https://doi.org/10.1111/j.1540-6261.1969.tb01694.x. The Relationship Between Put and Call Option Prices
, The Journal of Finance 24(5), 801-824 (December 1969). Stoll studied the relation between contract prices and tested it against market data; this was a relation between prices rather than a formula fixing each price individually. Robert C. Merton's [ref]https://doi.org/10.1111/j.1540-6261.1973.tb01357.x. 1973 comment
, 28(1), 183-184, highlighted the importance of excluding premature exercise for an exact arbitrage equality. This distinction explains why the exercise assumption belongs in the statement of put-call parity.The difference of the terminal power-call and power-put payoffs is . Risk-neutral pricing and the geometric Brownian motion moment formula therefore give the displayed parity, with . At this reduces to dividend-adjusted put-call parity.
For the normalized Black-Scholes call function, completing the square gives , with and . The identities and implyFor a stock with risk-neutral drift , maturity difference , and positive strike , put-call parity then givesThe positive sign of in the reciprocal argument is forced by taking the reciprocal of . The identity includes by continuity and requires .
Articles by others on the same topic
There are currently no matching articles.