
Heston model Created 2026-10-03 Updated 2026-11-05
The Heston model couples a positive stock price to a square-root variance process. Under a chosen risk-neutral measure, a standard specification with continuous dividend yield iswith , and . Here is long-run variance, the mean-reversion speed, and the scale of variance shocks. The parameters under the pricing measure need not equal those under the physical measure.
The variance is a CIR model. It remains nonnegative; for , makes zero inaccessible. Correlation couples price changes to subsequent uncertainty, a mechanism absent from constant-volatility Black-Scholes model.
The joint process is affine: its conditional log-price characteristic function has the form , with coefficients solving Riccati equations. Fourier inversion then prices European options. The familiar closed-form description includes a one-dimensional numerical integral, rather than a purely elementary call-price expression.[ref]
Steven L. Heston 2026-11-05
Steven L. Heston introduced the Heston model, a stochastic volatility model in which the asset price and its instantaneous variance evolve together. The variance follows a square-root diffusion, while correlation between the price and variance innovations allows asymmetric option-price patterns.[ref]
The model is useful because richer uncertainty does not remove all analytical structure. An affine expression for the characteristic function of the log price allows Fourier inversion to recover the probabilities used in European option valuation. The resulting pricing formula includes numerical integration; “closed-form” here does not mean that every price is an elementary expression without a numerical step.[ref]
Institutional profile: www.rhsmith.umd.edu/directory/steve-heston
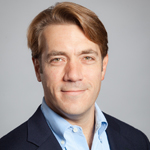
Portrait of Steven L. Heston
. Portrait selected from the matching University of Maryland institutional profile. Source. Stochastic volatility model Created 2026-10-03 Updated 2026-11-05
A stochastic volatility model gives an asset a separate random volatility or variance process. For example, a stock can have pricing dynamics , with random , instead of the constant variance of the Black-Scholes model. The Heston model uses a CIR model for ; an Ornstein-Uhlenbeck process can instead model a signed volatility whose square is the variance.
The extra state lets current uncertainty affect future uncertainty, and correlated asset and variance shocks change the distribution of future returns and option values. This differs from a local volatility model, where the coefficient is a deterministic function of time and current spot alone.
With two independent sources of uncertainty and only a stock and bank account, the variance risk is generally not fully hedgeable. A physical variance model then does not uniquely determine its pricing dynamics: a volatility-risk premium or additional traded instruments must be specified. Heston's original model makes the joint asset/variance system tractable through an affine characteristic-function calculation.[ref]