Harry Markowitz developed modern portfolio theory, making the tradeoff between expected return and variability a mathematical allocation problem. His 1952 Portfolio Selection by Harry Markowitz emphasizes that the variability of a combination depends on relationships between its components, not just on each component considered alone.[ref]
Portfolio Selection by Harry Markowitz. pp.79–82, expected return, covariance and portfolio variance
For an original toy example, let two return random variables each have variance one. Equal weighting givesWith zero covariance the result is ; with covariance one it is one. The calculation explains why counting assets alone does not determine diversification. Expected values, covariance estimates and allocation constraints supply distinct inputs to the optimization.
The 1990 economics prize recognized his theory of portfolio choice. The awarding academy's account identifies both the 1952 paper and his expanded 1959 treatment.[ref]
The Prize in Economic Sciences 1990 press release. 16 October 1990, Markowitz and portfolio selection
https://photoarchive.lib.uchicago.edu/db.xqy?show=browse8.xml%7C545. Named portrait record and credit
. Photograph undated.Robert Litterman developed the Black-Litterman model with Fischer Black. Their 1992 paper makes equilibrium expected returns a neutral starting point for portfolio modeling, then incorporates views that can differ in their confidence. The contribution addresses how uncertain inputs enter modern portfolio theory, rather than treating every proposed expected return as equally reliable.[ref]
Global Portfolio Optimization by Fischer Black and Robert Litterman. Publisher abstract: neutral equilibrium reference and views with differing confidence
An elementary Bayesian inference analogy illustrates the role of uncertainty. For an unknown quantity with normal distribution prior and an independent observation error giving , Gaussian conditional expectation gives the posterior meanThe more uncertain input receives less weight. This scalar example explains a modeling principle; the full Black-Litterman model treats related expected returns jointly, with a covariance matrix describing their uncertainty.

Robert Litterman with Fischer Black in 1994
. Historical photograph hosted and identified by Goldman Sachs, linked externally. Source.Mark Rubinstein worked on option pricing, including the Cox--Ross--Rubinstein model developed with John C. Cox and Stephen A. Ross. Their 1979 paper constructs an accessible discrete-time model in which successive up and down moves form a binomial price tree. Replicating a contingent payment with traded assets determines its value under the model's no-arbitrage assumptions.[ref]
Option Pricing: A Simplified Approach by John C. Cox and others. 1979, sections on the basic idea and the multiperiod model; author list
The construction makes the relation between hedging and valuation explicit. Its risk-neutral probabilities are weights consistent with the model's prices, rather than predictions of the actual frequency of an upward market move. Refining the time steps also connects the discrete model to the Black-Scholes model.[ref]
Option Pricing: A Simplified Approach by John C. Cox and others. Multiperiod valuation and the limiting case
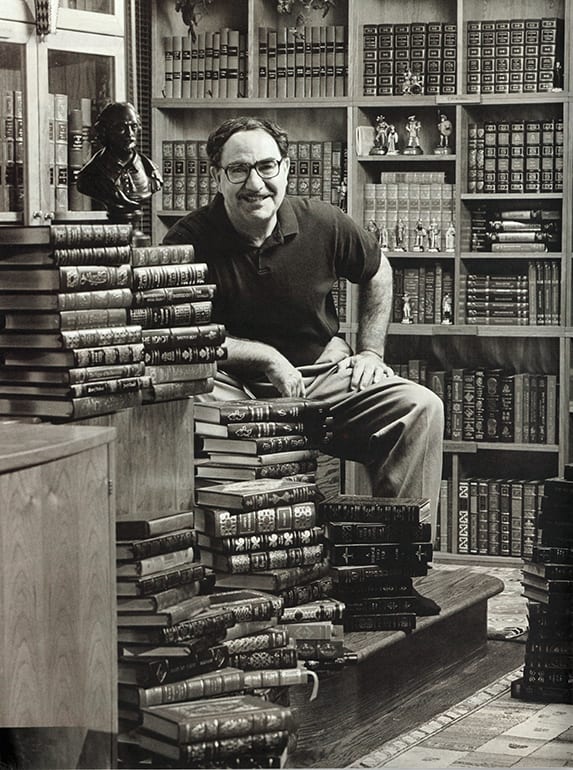
Portrait of Mark Rubinstein
. Jim Block; photograph in his home library, 2002, hosted by Berkeley Haas. Source.Stephen A. Ross developed arbitrage pricing theory, which relates expected asset returns to exposures to common sources of risk under assumptions limiting arbitrage. His mathematical approach asks how restrictions on feasible trading strategies constrain prices, rather than starting solely from an individual investor's preferences.[ref]
Professor Stephen Ross, inventor of arbitrage pricing theory, dies at 73 by Zach Church. 6 March 2017, discussion of arbitrage pricing theory and its 1976 introduction
With John C. Cox and Mark Rubinstein, he also developed the Cox--Ross--Rubinstein model for option pricing. The binomial price tree separates the possible stock-price paths from the valuation rule: a replicating portfolio and no-arbitrage produce risk-neutral pricing even when the actual up-move probability is not specified.[ref]
Option Pricing: A Simplified Approach by John C. Cox and others. 1979, basic one-period argument and its extension to multiple periods
Portrait of Stephen A. Ross
. 1994 portrait reproduced in the MIT institutional obituary. Source.John C. Cox developed mathematical methods for option pricing and risk-neutral pricing. With Stephen A. Ross and Mark Rubinstein, he introduced the Cox--Ross--Rubinstein model, whose binomial price tree gives a particularly transparent example of a replicating portfolio.[ref]
Option Pricing: A Simplified Approach by John C. Cox and others. 1979, author list and the one-period replication argument
At each node, the two possible next-step payments determine the holdings in a stock and a riskless asset. Repeating this calculation by backward induction values the final payment through the tree. For an American option, the calculation also compares continuation value with the value of immediate exercise. This turns the distinction between European and American exercise rules into a concrete computational decision.[ref]
Option Pricing: A Simplified Approach by John C. Cox and others. Multiperiod model and valuation of options permitting early exercise
Institutional profile: mitsloan.mit.edu/faculty/directory/john-c-cox

Portrait of John C. Cox
. Portrait selected from the matching MIT Sloan institutional profile. Source.Steven L. Heston introduced the Heston model, a stochastic volatility model in which the asset price and its instantaneous variance evolve together. The variance follows a square-root diffusion, while correlation between the price and variance innovations allows asymmetric option-price patterns.[ref]
The model is useful because richer uncertainty does not remove all analytical structure. An affine expression for the characteristic function of the log price allows Fourier inversion to recover the probabilities used in European option valuation. The resulting pricing formula includes numerical integration; “closed-form” here does not mean that every price is an elementary expression without a numerical step.[ref]
Institutional profile: www.rhsmith.umd.edu/directory/steve-heston
Portrait of Steven L. Heston
. Portrait selected from the matching University of Maryland institutional profile. Source.Myron Scholes, with Fischer Black, developed the Black-Scholes model and its option pricing equation. Their 1973 paper connects a contingent claim's value to the cost of a dynamically adjusted replicating portfolio, under explicit assumptions about trading and the underlying price process.[ref]
The Pricing of Options and Corporate Liabilities by Fischer Black and Myron Scholes. 1973, assumptions and derivation of the valuation equation
The mathematical insight is that a carefully chosen hedge can cancel the instantaneous random component of the claim's value. No-arbitrage then constrains the remaining locally riskless return, producing the Black-Scholes equation together with a final payoff condition. The result is a conditional conclusion within a model: it does not require an ability to predict the actual stock-price path.[ref]
The Pricing of Options and Corporate Liabilities by Fischer Black and Myron Scholes. Derivation of the differential equation and the boundary condition for a call
Institutional profile: www.gsb.stanford.edu/faculty-research/faculty/myron-s-scholes

Portrait of Myron Scholes
. Markus Prantl, via Wikimedia Commons; existing crop by JB Hoang Tam 2, CC BY-SA 3.0. Source.Fischer Black developed the Black-Scholes model with Myron Scholes. Their 1973 analysis shows how continuous adjustment of a replicating portfolio can eliminate the local exposure to the underlying random price change, leading to a no-arbitrage equation for the value of a contingent claim.[ref]
The Pricing of Options and Corporate Liabilities by Fischer Black and Myron Scholes. 1973, assumptions and derivation of the valuation equation
This approach makes the hedge part of the mathematical explanation of the price. It also makes the assumptions visible: ideal continuous adjustment and the specified price dynamics are ingredients of the derivation, so changing the trading rules or dynamics can change the valuation problem. The Black-Scholes equation is therefore a useful starting point for studying both a tractable model and the effects of relaxing its assumptions.[ref]
The Pricing of Options and Corporate Liabilities by Fischer Black and Myron Scholes. Model assumptions, valuation equation and discussion of extensions
Robert Litterman and Fischer Black in 1994
. Historical photograph hosted and identified by Goldman Sachs; reproduced by external link. Source.An economist who developed foundations of game theory and the Von Neumann-Morgenstern utility theorem with John von Neumann.

Historical portrait crop of Oskar Morgenstern
. Anonymous photograph, University of the Andes, Colombia; existing Commons crop from its 1954–1955 bulletin group photograph. The source crop is only 48 by 74 pixels. Source.Researcher whose work includes Peer effects, teacher incentives, and the impact of tracking: evidence from a randomized evaluation in Kenya by Esther Duflo and others.

Portrait of Esther Duflo
. Kris Krüg; CC BY-SA 2.0, via Wikimedia Commons. Source.Economist whose research is represented by School readiness and later achievement by Greg J. Duncan and others.



