
The conditional variance measures the remaining squared uncertainty after specified information has been used to form a conditional mean. For a real square-integrable random variable and a sub-sigma-algebra , let . ThenIt is a -measurable random variable, nonnegative almost surely, rather than necessarily a single number. With the information , its value is the variance in the group identified by . Its expected value is the mean squared error of predicting by its conditional mean.[ref]
In the exact mixture distribution in law of total expectation, group contains around mean two, and group contains around mean eight. Both groups have conditional variance four because their deviations from their own means are with equal probabilities. Therefore . Meanwhile, the two group means have variance . The law of total variance givesDirect calculation gives and , checking the decomposition.
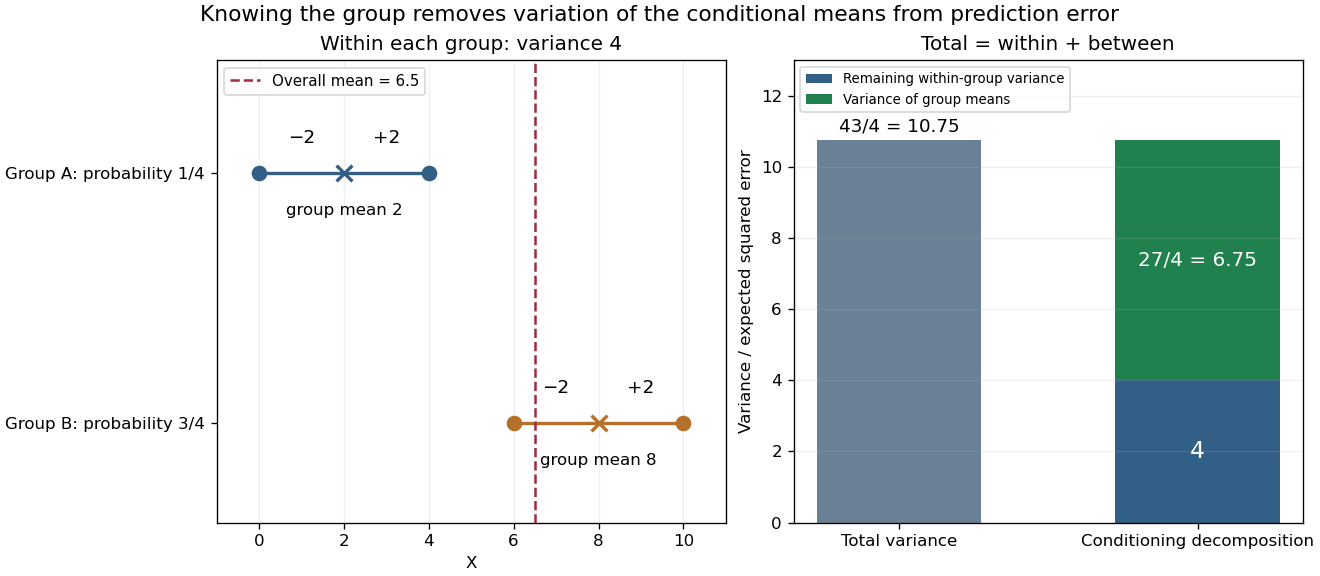
For any square-integrable -measurable predictor , the error identity isThe cross term vanishes because . Thus using the conditional mean minimizes mean squared error, while conditional variance quantifies what this information still cannot predict. This is the orthogonal projection interpretation in L2 space.[ref]


Conditional variance is a statistical measure that quantifies the variability of a random variable given that some other random variable takes a specific value or falls within a certain range. Essentially, it helps us understand how the dispersion of one variable changes when we know the value of another variable.
New to topics? Read the docs here!