E.g. a Galilean transformation generally changes the exact values of coordinates, but not the form of the laws of physics themselves.
Lorentz covariance is the main context under which the word "covariant" appears, because we really don't want the form of the equations to change under Lorentz transforms, and "covariance" is often used as a synonym of "Lorentz covariance".
TODO some sources distinguish "invariant" from "covariant": invariant vs covariant.
Articles by others on the same topic

The covariance measures the average product of two centered deviations. For real square-integrable random variables and ,Deviations with the same sign contribute positively; deviations with opposite signs contribute negatively. Their magnitudes and probabilities determine the net result. Taking recovers the variance. The definitions and algebraic properties are presented in Orloff and Bloom, MIT 18.05, Covariance and Correlation, sections 2–2.1.
For a worked example, let be independent random variables, each equally likely to be , or , and put . All nine pairs have probability . The expected values are zero, while linearity of covariance and the vanishing covariance of independent random variables giveThe shared term makes large accompany large on average. Replacing by reverses the covariance to without changing either variance.
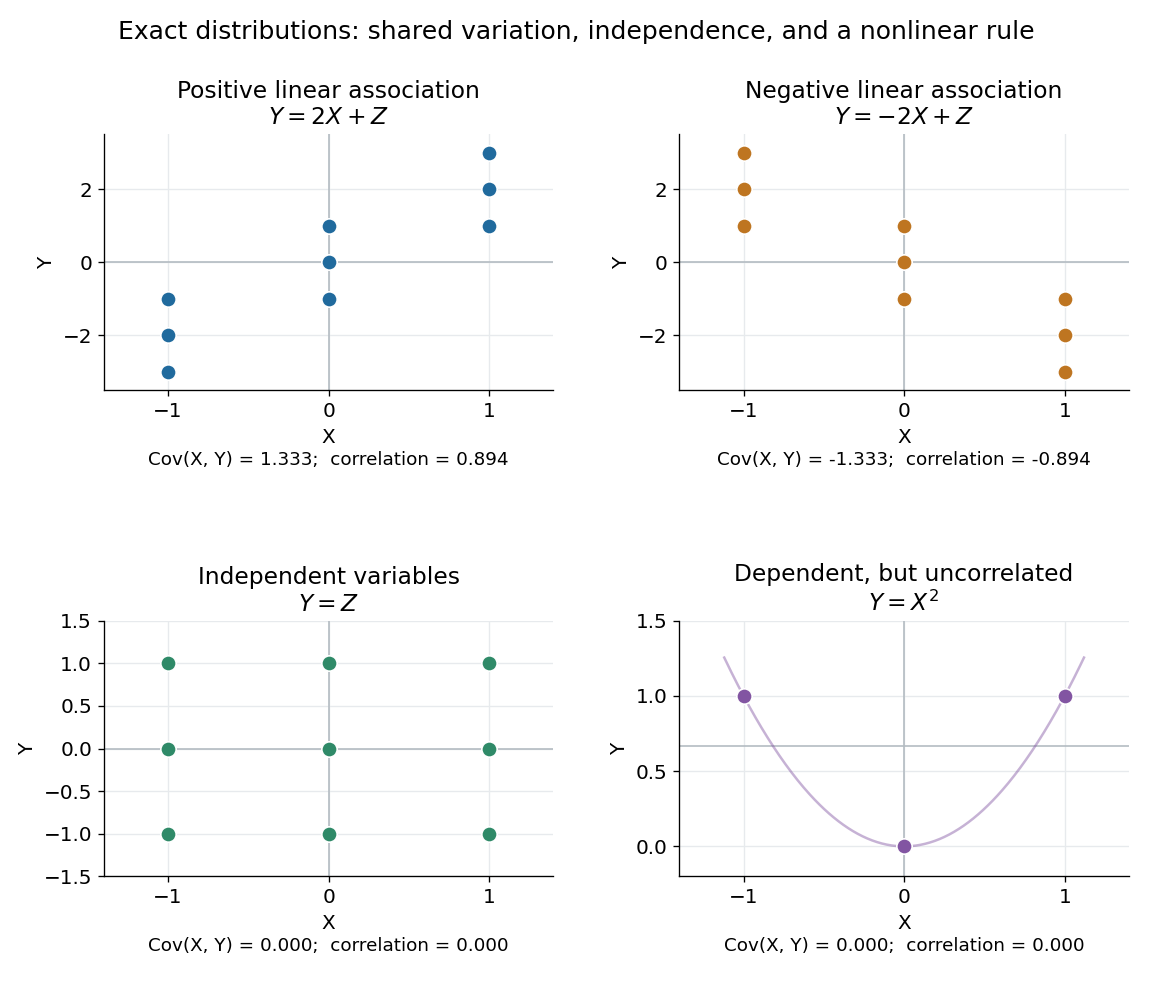
Positive, negative, independent, and nonlinear relationships have different covariance behavior
. In the first three panels, and independently take , and with equal probabilities; each point has probability . In the last panel, , and the three marked outcomes each have probability . The thin curve shows that quadratic function. Its zero covariance leaves strong nonlinear statistical dependence visible. Details.
The covariance is useful whenever deviations are added or subtracted. Expanding the square givesFor the worked model, these are and . Positive covariance increases variation in the sum while reducing variation in the difference: the same shared fluctuation reinforces one combination and partly cancels in the other. The identity applies beyond independent random variables.
The size of a covariance depends on the measurement scale. For constants , linearity of covariance gives . Adding offsets has no effect; rescaling either measurement rescales the covariance. The Pearson correlation coefficient divides by both standard deviations to describe the standardized linear relationship.