Use the two-sided spectral density of a stationary process conventionThus white noise of variance has density .
Absolute summability makes the linear filter of a stationary time series well defined in : . Its mean is . For its autocovariance, continuity of the inner product givesThe sum is absolutely convergent because . It depends only on , proving weak stationarity. Inserting the spectral inversion formula and exchanging the absolutely dominated sum with the integral yieldsHere the coefficients are real, so the two factors are complex conjugates. This is the spectral density transformation under a linear filter.
Applying a second linear filter of a stationary time series givesThe composition of absolutely summable time-series filters can also be calculated directly:Indeed ; this bound also justifies the interchange of the two sums. The filter gain multiplies under this composition. The sketches for the two individual filters are:
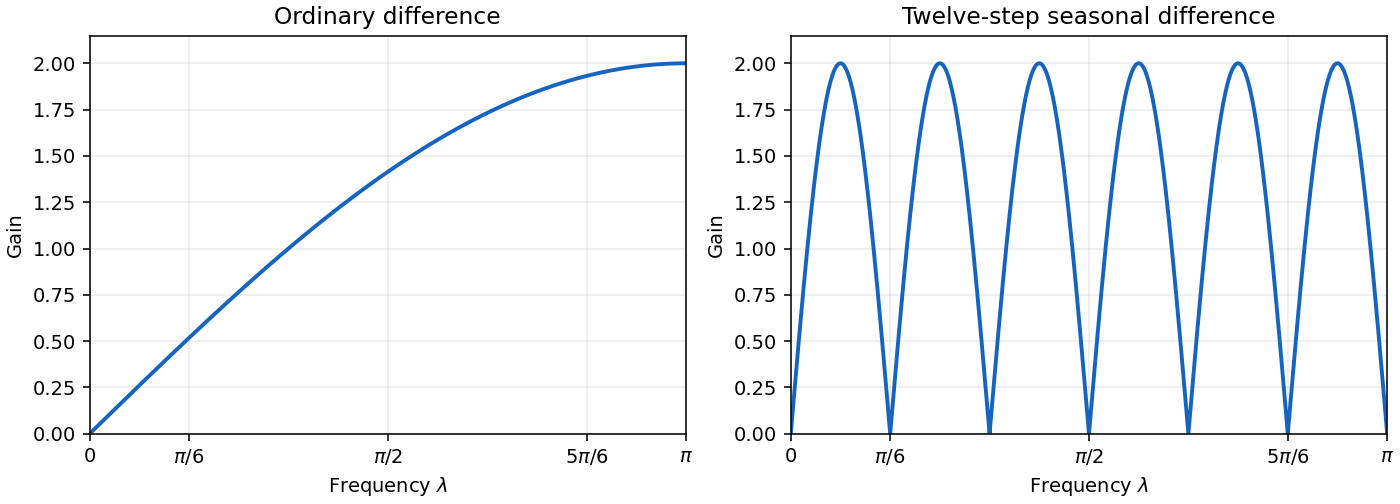
Ordinary and twelve-step seasonal difference-filter gains
. Details. 
Articles by others on the same topic
There are currently no matching articles.