Write . In a continuation interval, the Euler differential equation has power solutions and : substitution of gives . A decreasing bounded value uses the second solution.
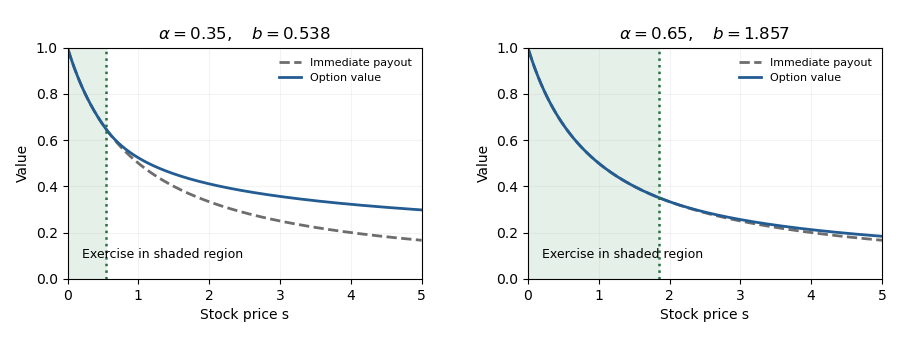
Let be the exercise boundary. Value matching and smooth fit require and . Dividing gives . ConsequentlyThis is a perpetual reciprocal-payoff American option.
To verify the obstacle inequality, observe that increases up to and decreases afterwards, because its logarithmic derivative is . Therefore for . In the continuation region . In the exercise region,The quadratic is convex. At the two endpoints of it equals and , respectively, so it is negative throughout that interval. Thus the obstacle problem is satisfied on both regions, with value matching and smooth fit at . The second derivative has a jump at ; the equation is understood piecewise and in the generalized Itô sense described in part (a).
For optimality, use the Risk-neutral measure for the Black-Scholes model, under which . The Itô formula makes a nonnegative supermartingale, so every exercise time satisfiesBefore hitting the exercise region, its drift vanishes. Since , the stopped process is a bounded martingale. Apply the optional sampling theorem at and let . The contribution from is at most , while the boundary value equals the payoff. Hence equality holds forIf , exercise immediately; otherwise wait for the first down-crossing. If that time is infinite, the discounted payout is zero. This proves both the value and the optimal stopping policy, and part (a) supplies its superhedge.
Articles by others on the same topic
There are currently no matching articles.