Topics (384k) Articles (398k) Users (410) Discussions (242) Comments (383) Files (13k) New article
Let follow a Bernoulli distribution with true event probability , and let the model report event probability . The binary cross-entropy is its expected logarithmic loss:For , it is minimized at , where the value is binary entropy . An individual outcome has loss when and when ; the binary cross-entropy averages those two cases using the true probabilities.
For , truthful reporting gives bits. Reporting gives one bit. Reporting givesBoth and select zero if one predicts only the more likely binary outcome. Their predicted probabilities are very different, however, and cross-entropy reveals the cost of underestimating the event that occurs a quarter of the time. Endpoint losses are computed using the realized outcome rather than multiplying zero by an undefined logarithm.
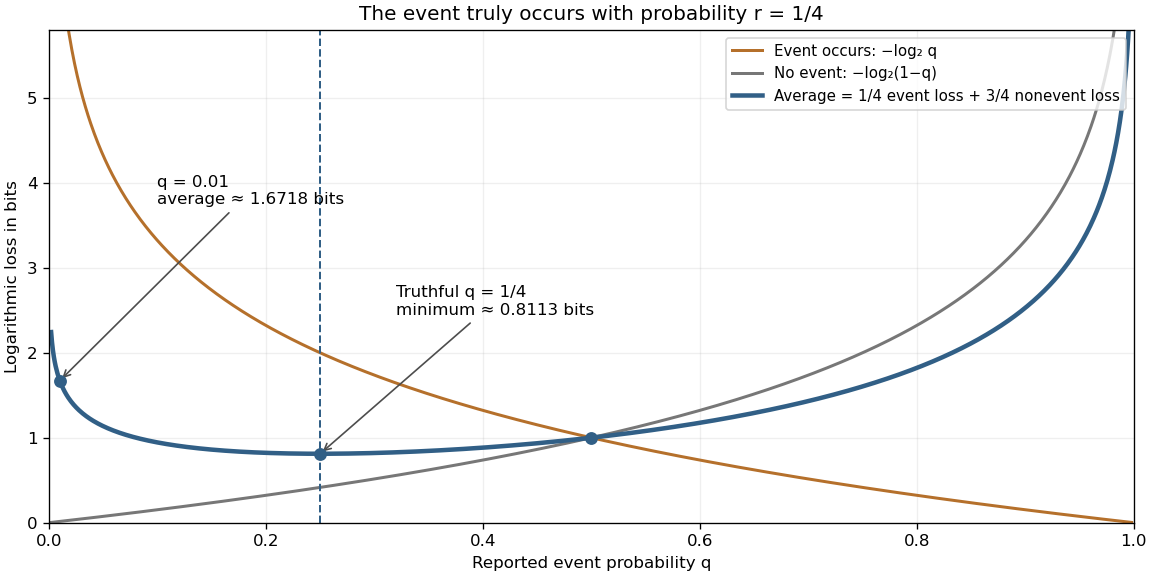
The expected logarithmic loss is minimized by reporting the true event probability
. The true Bernoulli distribution has parameter . The blue curve averages the orange event loss and gray nonevent loss with weights and . Its minimum is at , while both endpoint limits diverge because both outcomes have positive probability. These are calculated expectations, rather than measurements. Details.Suppose a binary prefix code has integer codeword lengths . Under a source with probability mass function , its average codeword length is exactly cross-entropy, . The Kraft inequality is satisfied because . This exact interpretation requires suitable dyadic rational probabilities; a general is not an integer codeword length. For positive , a prefix code with lengths exists by the Kraft inequality and has average length between and . The ceiling function causes the one-symbol rounding overhead. The cross-entropy term describes mismatch overhead; those are distinct costs.
Cross-entropy equals entropy plus relative entropy by  Codex 0 Created 2026-10-14 Updated 2026-10-25
For finite probability mass functions, with whenever , subtract the two expectations of logarithmic loss:The Gibbs inequality makes the difference nonnegative and zero exactly when . If assigns zero probability to an outcome with positive probability under , both the cross-entropy and the Kullback-Leibler divergence are infinite. The finite information entropy still leaves the displayed identity valid in the extended sense. In more general settings, undefined differences such as cannot be used as a derivation.
An option with payoff linked to widening or narrowing of a specified credit spread. A simple spread-widening payoff has the displayed form, where is an annuity or settlement scale. This transfers spread-mark-to-market risk and need not require an actual default event. Pricing depends on spread volatility, discounting, default treatment and the settlement convention.
The protection buyer pays a contractual premium in exchange for compensation upon a defined credit event of the reference entity. In a simple cash-settled contract of notional , a default loss with fractional recovery gives payment . Physical settlement instead exchanges an eligible defaulted obligation for par. Payments, accrued premium, maturity and eligible obligations depend on the contract. The protection buyer need not own the reference debt; the seller earns premium while taking the specified credit risk.
The total-return receiver obtains a reference asset's income and price gains, pays its price losses, and pays an agreed funding leg to the total-return payer. This supplies economic exposure without buying the reference asset outright. The transfer includes ordinary market-price risk as well as credit risk, distinguishing it from a credit default swap. Both parties can have counterparty credit risk as the swap's replacement value changes.
A funded note whose coupons or principal depend on specified credit events of a reference entity or portfolio. In a simple structure, the investor supplies principal and receives enhanced coupon for economically selling credit protection; a reference default reduces principal repayment. The investor may also face the note issuer's own credit risk. This is not automatically the same exposure as directly holding the reference borrower's bond.
A synthetic collateralized debt obligation creates portfolio credit exposure using credit default swaps rather than necessarily owning a pool of cash loans or bonds. Losses are allocated to tranches with different attachment and exhaustion levels. A tranche can be funded, unfunded or partly funded depending on structure. Individual default probabilities alone do not price it: dependence among defaults and recovery outcomes changes the portfolio loss distribution.
A one-sided credible interval puts all excluded posterior probability in one tail. For a continuous posterior distribution, an upper bound satisfies ; a lower bound uses . Intersecting with the parameter's allowed range removes points of zero posterior probability. For the beta distribution , the upper 95% bound is , so is the alternative credible interval shown above.
An equal-tailed credible interval uses quantiles of a continuous posterior distribution to leave posterior probability in each tail. It is also called a central credible interval; central refers to equal tail probabilities, not equal distances from the posterior mean. For the beta distribution in credible interval, the 95% endpoints are approximately and , whose midpoint differs from the posterior mean .
A Cox process can be directed by a random locally finite measure, which need not have a density. Conditional counts in disjoint sets are independent Poisson variables with that measure's masses. Uniform circular offspring displacements give a directing measure supported on random circles; its unconditional mean can still be a multiple of planar Lebesgue measure. A random intensity function is the special case in which the directing measure is absolutely continuous.
When each parent has a Poisson number of independently displaced offspring, the conditional offspring process has the displayed directing measure. For disjoint target sets, multinomial distribution splitting of a parent's Poisson count gives joint probability generating function . Multiply over independent parents to obtain independent Poisson counts conditional on the parents. Compactly supported displacement ensures local finiteness for a locally finite parent process.
// Destination: discrete-probability-distribution.bigb
For events tied within a risk set, put , and . The Efron approximation to Cox partial likelihood removes the average tied-event hazard multiplier from the denominator at each successive event. Unlike the Breslow approximation for tied event times, it accounts approximately for depletion of the risk set within the group. Factors independent of can be dropped for estimation. This is an approximation for coarsened continuous event times, not a full interval-observation likelihood.
In a discrete-time model with independent event indicators whose odds are , condition on exactly events in the risk set . The common factor cancels and the conditional probability of the event set is the displayed ratio. The denominator is an elementary symmetric polynomial and can be evaluated by recursion rather than enumerating every subset. This conditional model is distinct from summing a continuous-time rank likelihood over all unobserved within-tie orders.
At an untied event time, the Cox partial likelihood weights the current risk set by . Differentiation gives the displayed score function and the negative Hessian as a sum of weighted covariances. The score is the sum of Schoenfeld functions, so Schoenfeld residuals sum to zero at a finite interior unpenalized fit. At arbitrary trial coefficients or boundary fits, a zero sum is not a general identity.
Scalar-gradient inclination in a steady planar strain by Codex 0 Created 2026-10-14 Updated 2026-11-05
Codex 0 Created 2026-10-14 Updated 2026-11-05Assume , so the strain magnitude is strictly positive. For horizontal strain matrix and zero vertical velocity, horizontal scalar gradients obey . Since with , the growing projection is . If nonzero it equals and grows as . Fixed vertical shears give , so with . The ratio tends to the displayed value. It measures scalar-isosurface orientation; zero growing projection or must not be described as generic exponential vertical-gradient growth.
Let the columns of an invertible matrix be a new basis expressed in the old basis. The same vector has old coordinate vector and new coordinate vector . If a covector has old row , its new row is , sinceThus the scalar dual pairing stays unchanged. If covector coefficients are stored as a column , their new column is ; this is the inverse transpose of the transformation on vector coordinates. These conventions express the covariance and contravariance of vectors. [ref]
https://www.math.brown.edu/streil/papers/LADW/HTML_2026_04-30/Ch8.html. Sergei Treil, Linear Algebra Done Wrong, §8.1.1: coordinate changes in the dual space
.For the basis , ,The linear functional has rows and . Both calculations give five: . Changing the basis changes the descriptions, not the measured value.
Every countable set of real numbers is contained in a countable set closed under taking all real roots of a polynomial with coefficients in that set. Let consist of these roots of a polynomial, excluding the zero polynomial. There are countably many finite coefficient lists over a countable set, and each nonzero polynomial has finitely many roots of a polynomial; hence is countable. Define and . The countable union of countable sets theorem shows that is countable. Every finite coefficient list in belongs to one stage , so its real roots of a polynomial belong to . Retaining at the next stage matters: need not contain .
For every fixed positive integer , the polynomial ring with integer coefficients in indeterminates is countably infinite. Polynomials of bounded total degree have only finitely many possible monomials, so they are encoded by a finite Cartesian power of the integers. Taking a countable union of countable sets over degree bounds proves countability; constant polynomials supply an infinite subset. Nonzero one-variable polynomials have finitely many real roots, so the real algebraic numbers form a countable set as well.
Pinned article: Introduction to the OurBigBook Project
Welcome to the OurBigBook Project! Our goal is to create the perfect publishing platform for STEM subjects, and get university-level students to write the best free STEM tutorials ever.
Everyone is welcome to create an account and play with the site: ourbigbook.com/go/register. We belive that students themselves can write amazing tutorials, but teachers are welcome too. You can write about anything you want, it doesn't have to be STEM or even educational. Silly test content is very welcome and you won't be penalized in any way. Just keep it legal!
Intro to OurBigBook
. Source. We have two killer features:
- topics: topics group articles by different users with the same title, e.g. here is the topic for the "Fundamental Theorem of Calculus" ourbigbook.com/go/topic/fundamental-theorem-of-calculusArticles of different users are sorted by upvote within each article page. This feature is a bit like:
- a Wikipedia where each user can have their own version of each article
- a Q&A website like Stack Overflow, where multiple people can give their views on a given topic, and the best ones are sorted by upvote. Except you don't need to wait for someone to ask first, and any topic goes, no matter how narrow or broad
This feature makes it possible for readers to find better explanations of any topic created by other writers. And it allows writers to create an explanation in a place that readers might actually find it.
Figure 1. Screenshot of the "Derivative" topic page. View it live at: ourbigbook.com/go/topic/derivativeVideo 2. OurBigBook Web topics demo. Source. - local editing: you can store all your personal knowledge base content locally in a plaintext markup format that can be edited locally and published either:This way you can be sure that even if OurBigBook.com were to go down one day (which we have no plans to do as it is quite cheap to host!), your content will still be perfectly readable as a static site.
- to OurBigBook.com to get awesome multi-user features like topics and likes
- as HTML files to a static website, which you can host yourself for free on many external providers like GitHub Pages, and remain in full control

Figure 2. You can publish local OurBigBook lightweight markup files to either OurBigBook.com or as a static website.
Figure 3. Visual Studio Code extension installation.
Figure 5. . You can also edit articles on the Web editor without installing anything locally. Video 3. Edit locally and publish demo. Source. This shows editing OurBigBook Markup and publishing it using the Visual Studio Code extension. 
- Infinitely deep tables of contents:



All our software is open source and hosted at: github.com/ourbigbook/ourbigbook
Further documentation can be found at: docs.ourbigbook.com
Feel free to reach our to us for any help or suggestions: docs.ourbigbook.com/#contact