
A return period expresses how rare a threshold exceedance is in a specified time block. Let be the sample maximum in block , fix a threshold , and suppose is the same for every block. The conventional return period is blocks; blocks of duration give a time of . Thus an annual exceedance probability means a 100-year return period. This names a frequency scale, not a schedule or a guarantee of one exceedance in each century. The annual convention and the misleading “once every 100 years” interpretation are discussed in USGS: the 100-year flood.
To derive a waiting-time interpretation, assume the exceedance indicators are independent and identically distributed random variables with the Bernoulli distribution of parameter . Define , counting the successful block as well as all preceding blocks. The first Bernoulli trials must fail and the th must succeed, so independence gives the geometric distributionThe expected value can also be read directly from the geometric series: . This counts blocks from the starting boundary, not the exact time of an exceedance within its block. Counting only failed blocks instead would give expected value . The waiting law and its memorylessness of the geometric distribution are developed in Kyle Siegrist, Random Services: the geometric distribution.
For a horizon of complete years, at least one exceedance is the complement of no exceedances. Under the same independence and constant- assumptions,For the toy choice , this gives in 10 years, in 30 years, in 50 years, and in 100 years. Even after 100 years there is a chance of no exceedance. These numbers are exact model calculations rounded to one decimal place, not measured frequencies. The median waiting count is 69 years, since ; the expected value is 100 years. A mean and a median answer different questions.
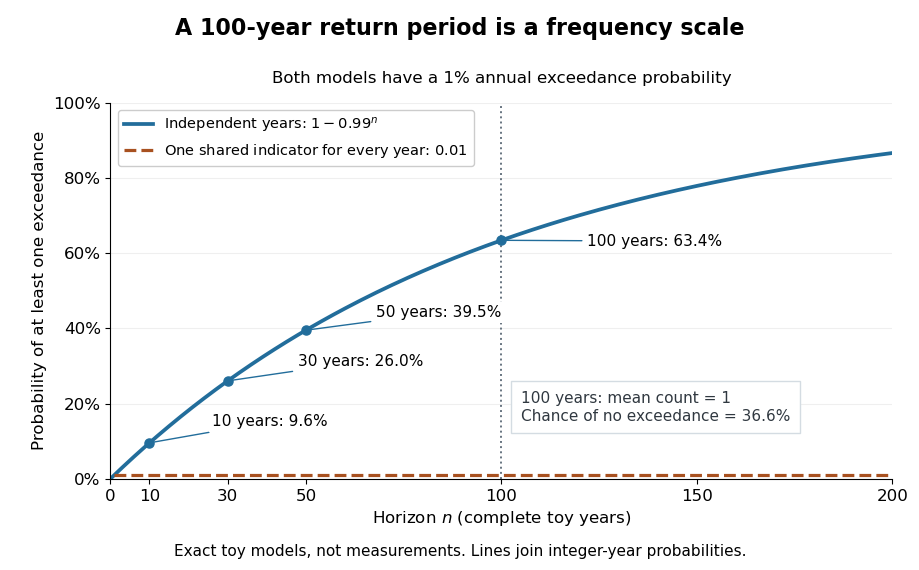
The exceedance count has the binomial distribution under independence, with expected value . Thus has expected value one, although its probability of being at least one is only : some realizations contribute several exceedances. For , the memorylessness of the geometric distribution gives . A long quiet spell does not make the next independent year's exceedance overdue, and an exceedance this year does not force a quiet interval. Two specified consecutive years both exceed with probability in this toy model.
A reproducible tabletop experiment makes the assumptions tangible. Put 100 identical slips numbered 1 to 100 in a bag; after thoroughly mixing, draw one and record whether it is 100. Replace the slip and mix again before every draw. Treat each draw as one toy year, so the exceedance indicator is a Bernoulli random variable with , provided the sampling is uniform and successive draws are independent. Repeat complete 30-draw runs and record the fraction containing at least one 100; separately repeat runs stopped at the first 100 and record their waiting counts. The first fraction targets ; the waiting-count histogram targets . Replacement keeps fixed, mixing is intended to support independence, and repeated runs expose sampling variation. This is a proposed demonstration of the toy model; no experimental results are asserted here.
Stationarity supports a time-invariant annual probability distribution, but does not imply independence. For an extreme counterexample, draw just one Bernoulli random variable of parameter and set for every year. This is a stationary process, yet the probability of any exceedance in every finite horizon is ; from an arbitrary starting boundary the wait is infinite with probability . The reciprocal marginal frequency therefore need not equal that forward waiting expected value. With equal marginal probabilities and arbitrary dependence, only the general bounds follow, the upper bound being the union bound. Linearity of expectation still gives without independence. Mere zero correlation does not restore the product formula; even pairwise independence does not imply joint independence. If annual probabilities change to , independence instead gives , and one fixed return period no longer describes all years.


The return period, also known as the recurrence interval, is a statistical measure used to describe the frequency at which an event of a certain magnitude is expected to occur within a specific time frame. It is commonly used in fields such as hydrology, meteorology, and risk assessment, particularly for events like floods, storms, earthquakes, and other natural phenomena. The return period is typically expressed in years and calculated using historical data.
New to topics? Read the docs here!