Three Bernoulli variables through characteristic functions
ID: three-bernoulli-variables-through-characteristic-functions

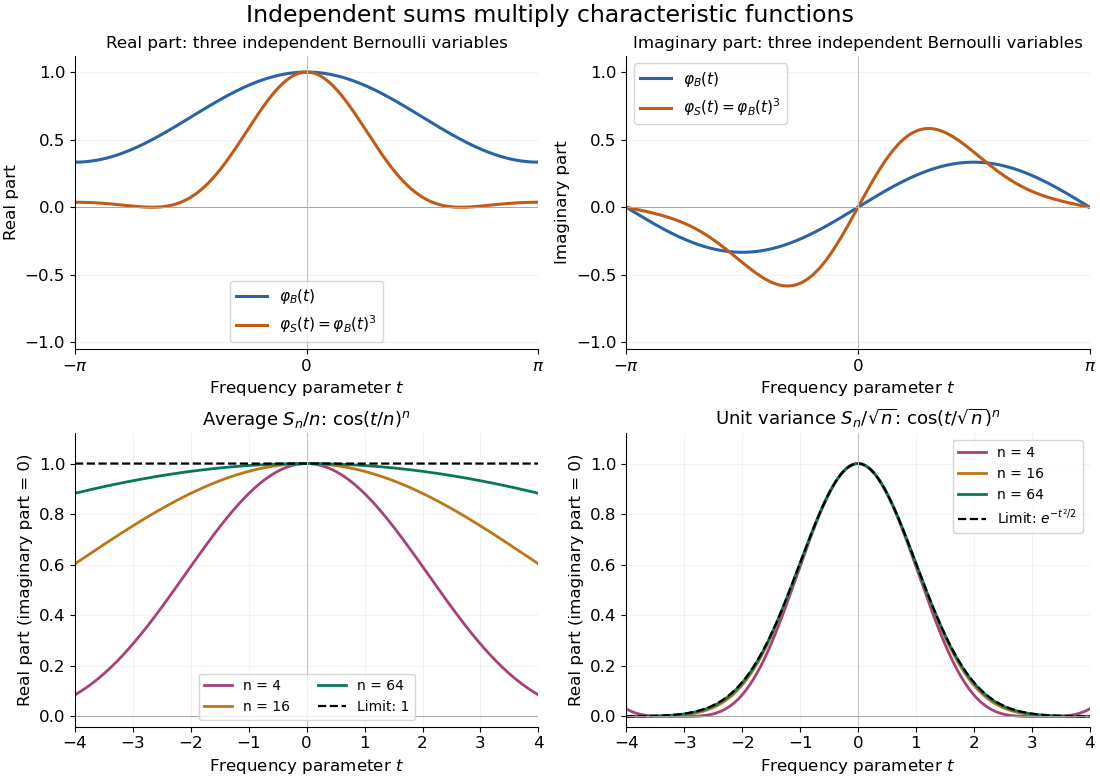
Let be independent random variables, each with the Bernoulli distribution of parameter , and let . Multiplying their characteristic functions and expanding by the binomial theorem givesThe coefficients are exactly the probability mass function of the binomial distribution with parameters : the sum takes with probabilities . Direct outcome counting verifies them: an outcome with ones has probability , and there are such outcomes. The coefficients sum to one, recovering .
At , . This is also : the complex exponential now records parity. The moments agree by two routes: linearity of expectation gives , while the variance of a sum of independent random variables gives . Summing gives the second moment , also recovered as .

New to topics? Read the docs here!