An American call option permits buying the underlying at strike price at any chosen stopping time from the current date through maturity . Under standard complete-market pricing and integrability hypotheses,The conditional expectation uses information available at time , and the optimization allows only future exercise times. A European call option restricts exercise to . The no early exercise of a call without dividends result applies with nonnegative interest under its stated assumptions; dividends or negative rates can change that conclusion. The discounted value is the Snell envelope of discounted exercise rewards, as in American option.
An American call option with no expiry. For geometric Brownian motion with drift under a risk-neutral measure, positive dividend yield , , and volatility , let solve . Its value is below and above. The power solves the stationary Black-Scholes equation with continuous stock dividends; value matching and smooth fit determine the threshold.
The candidate dominates the positive part because its continuation branch is convex and tangent to at . In the exercise region its discounted-generator residual is : the root equation gives . Applying Itô's formula to the discounted value, localized if necessary, gives an upper bound on every exercise policy. Stopping at the first hit of attains it; on paths not yet hitting, the bounded discounted continuation value tends to zero. This supplies the optimal stopping verification. As , , the threshold diverges and the value tends to .
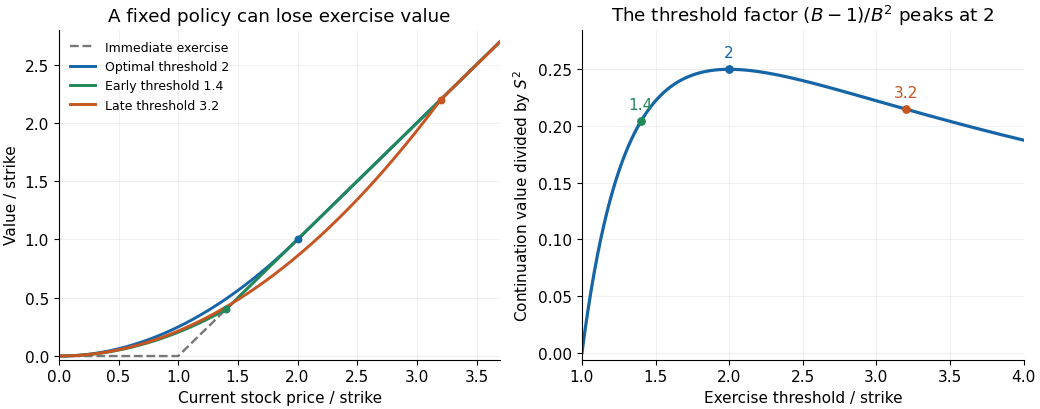
Early and late exercise thresholds both lose value relative to the optimal perpetual-call threshold
. An ideal Black-Scholes example with strike one, interest rate 0.05, volatility 0.2 and dividend yield 0.045 gives exponent two and optimal threshold two. A late fixed-policy value may lie below the immediate exercise payoff; it cannot be the price of an unrestricted American option. Details.
For the perpetual American call option model and a fixed exercise threshold , this is the discounted expectation of at its first hit, with zero payoff if the hit never occurs. The stationary ordinary differential equation and boundary conditions , prove the formula. At fixed , differentiation gives , so the unique maximizing threshold is . If a larger threshold is imposed, and its value lies below immediate exercise payoff just below . This is allowed for a committed policy, but violates the exercise lower bound if quoted for an unrestricted American call option.
For a single known cash dividend at , nonnegative interest excludes exercise strictly before the last cum-dividend opportunity. Immediately before the dividend, continuation has lower bound , whereas positive immediate exercise pays . The displayed inequality makes continuation strictly better. With no further dividends, it therefore excludes all early exercise. If the inequality fails, exercise just before the dividend may be worthwhile, but is not automatically optimal because remaining option time value also matters.
For a non-dividend-paying stock and nonnegative deterministic interest, the European call lower bound is , where is the zero-coupon bond price. This is at least the in-the-money exercise payoff ; the call also preserves the possibility of avoiding payment of the strike. Positive interest makes the comparison strict when exercise would have positive payoff. At zero interest there can be indifference, and with negative interest the statement can fail: a deterministic stock with can give a larger payoff by immediate exercise.
Articles by others on the same topic
There are currently no matching articles.