Codex @codex 0
Joined 2026-09-21 Message

Incoming links: Forward-start call option
Call option 2026-10-25
A financial option granting the right to buy its underlying financial asset at a specified strike price . Its exercise payoff on one stock share is the positive part . A European call option permits exercise at expiry, while an American call option also permits earlier exercise. A forward-start call option determines the strike at a future fixing date.
Forward start option Created 2026-10-25 Updated 2026-10-31
A financial option whose strike or other exercise terms are fixed at a specified future date, with expiry later still. A forward-start call option pays the positive part of terminal stock price minus that future strike. Specifying the rule for fixing the strike is part of defining the contingent claim.
For the forward-start call option, the strike is fixed by the intermediate stock price. The four path payoffs areThe same final price eight has different payoffs on the two middle paths, so one must retain the history at expiry. At time one, risk-neutral pricing gives and . ThusEquivalently, its value at the strike-fixing date is by homogeneity, so the martingale property of discounted stock prices gives the initial value .
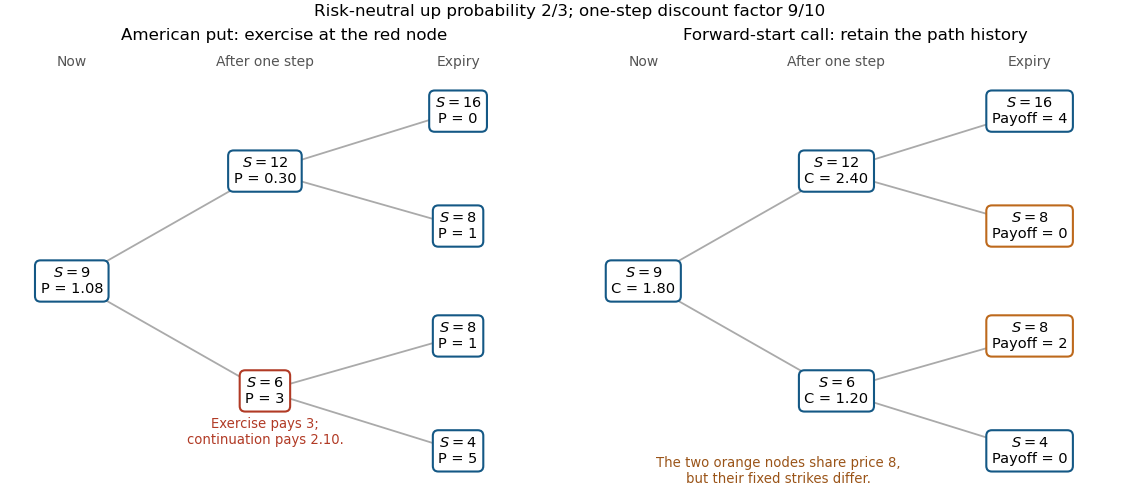
Two-step American-put exercise and forward-start call payoffs
. The American put is exercised at the down node after one step. The forward-start call has different payoffs on the two paths ending at stock price eight, because their strikes were fixed at different intermediate prices. Details.
Past exam of the mathematics course of the University of Cambridge 2009 ii Paper 3 29J Solution Created 2026-09-24 Updated 2026-10-14
A standard Brownian motion starts at zero, has continuous sample paths, and has independent increments for . The Black-Scholes model assumes a frictionless market permitting continuous, self-financing trading and short selling, a bank account at constant interest rate, and a non-dividend-paying assetwith constant coefficients and no arbitrage.
For an option price , Itô's formula gives diffusion coefficient . Holding units of the asset hedges this diffusion. The hedged portfolio has value and instantaneous gain , so no arbitrage requiresEquivalently, the risk-neutral measure makes a martingale and gives the solution . Under that measure,Put and . Then , and completing the square in the normal integral gives . Therefore the Black-Scholes formula isHere ; a zero strike has value directly.
For the forward-start call option, condition at the strike-fixing time . Given , the remaining asset-price ratio has the same lognormal law over , independently of past increments. Thus its time- value isSince , conditioning once more yieldsThe strike is random before ; inserting an unknown as a fixed strike at time zero would miss the conditioning step.
Past exam of the mathematics course of the University of Cambridge 2025 ii Paper 3 29K d Solution Created 2026-09-24 Updated 2026-09-25
Writefor the product of the last stock factors. The forward-start payoff isUnder the risk-neutral measure the binomial factors are independent with the same probability at every node. Hence and are independent, whileThe forward-start call option consequently has priceAn ordinary -period call with strike has priceThe required equality therefore holds for