For the forward-start call option, the strike is fixed by the intermediate stock price. The four path payoffs areThe same final price eight has different payoffs on the two middle paths, so one must retain the history at expiry. At time one, risk-neutral pricing gives and . ThusEquivalently, its value at the strike-fixing date is by homogeneity, so the martingale property of discounted stock prices gives the initial value .
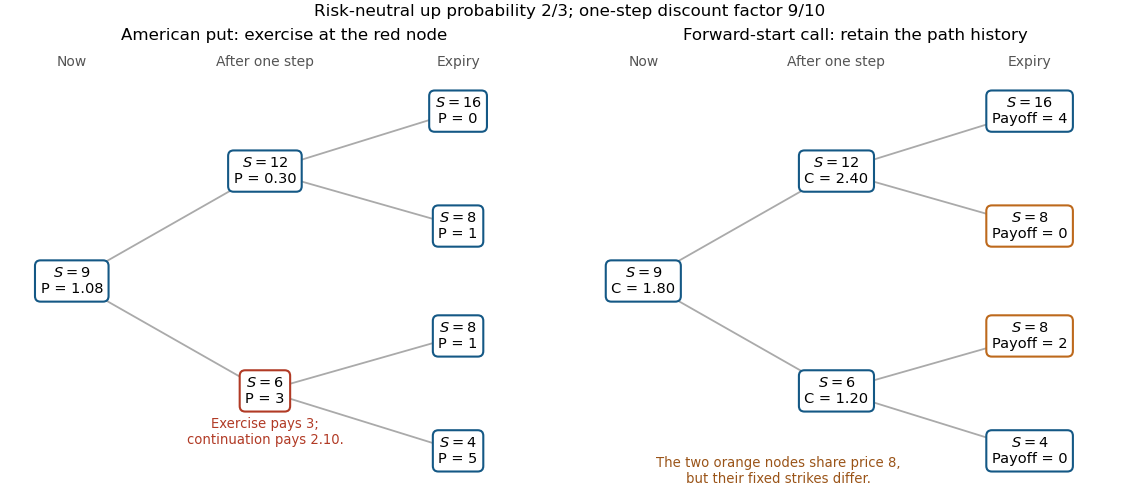
Two-step American-put exercise and forward-start call payoffs
. The American put is exercised at the down node after one step. The forward-start call has different payoffs on the two paths ending at stock price eight, because their strikes were fixed at different intermediate prices. Details.
Articles by others on the same topic
There are currently no matching articles.