Standard one-dimensional Brownian motion is a real-valued stochastic process on a probability space with three defining properties: almost surely; its sample paths are continuous almost surely; and its Brownian increments over any finite collection of disjoint time intervals are independent, withHere denotes the normal distribution with expectation and variance . The alternative symbol denotes the same kind of stochastic process. Continuity is a simultaneous statement about an entire sample path, rather than a separate assertion at each fixed time. Relative to its natural Brownian filtration, a future Brownian increment is independent of all observations up to its starting time.
The normalization gives , so the standard deviation of a Brownian increment over duration is . For , , and , the corresponding standard deviations are , , and . Time becoming one hundred times shorter makes typical displacement ten times smaller. Brownian scaling expresses this rule for the whole stochastic process, while the Brownian covariance kernel describes how positions at different times remain related despite independent increments.
For a concrete probability calculation, let be the cumulative distribution function of . At time four, has that normal distribution, henceThese numbers can be reproduced using the error function: . In particular, zero expectation does not mean small displacement: , but the same fixed interval contains only about of the probability at time four.
The probability density function of , for , isIts partial derivatives satisfyThus the normal distribution spreads according to the heat equation. Starting at a fixed position replaces by . This is a useful bridge between individual random trajectories and the deterministic evolution of their probability density function: the same Brownian motion provides both descriptions.
Physical diffusion uses its own scale. For constant diffusion coefficient , the position model has variance , and its probability density function satisfies . For example, gives displacement variance after four seconds, hence standard deviation . Standard Brownian motion corresponds numerically to in chosen units; omitting the factor two changes the physical convention. Einstein's 1905 paper relates diffusion to the mean squared displacement in precisely this convention. [ref]
https://djalil.chafai.net/docs/M2/history-brownian-motion/Einstein%20-%201905.pdf. Einstein, 1905 paper, English translation, section 4
Continuity does not supply a smooth physical velocity. The difference quotient has normal distribution , so its standard deviation grows as : for the three durations above it is , , and . This calculation motivates the nowhere differentiability of Brownian motion, but it alone is not a proof of the simultaneous assertion at every time. The theorem says that, with probability one, no finite derivative exists anywhere along the sample path. A drawn polygon only displays a finite grid; its straight segments cannot establish this theorem. See Theorem 7.1.6 in Probability: Theory and Examples (fifth edition) by Rick Durrett.
For physical particles, Brownian motion is a model of position on suitable observation scales. It does not claim that microscopic velocity is a derivative of this idealized path. Einstein explicitly restricts his assumption of independent increments to intervals that are not too short. [ref]
https://djalil.chafai.net/docs/M2/history-brownian-motion/Einstein%20-%201905.pdf. Einstein, 1905 paper, English translation, section 4
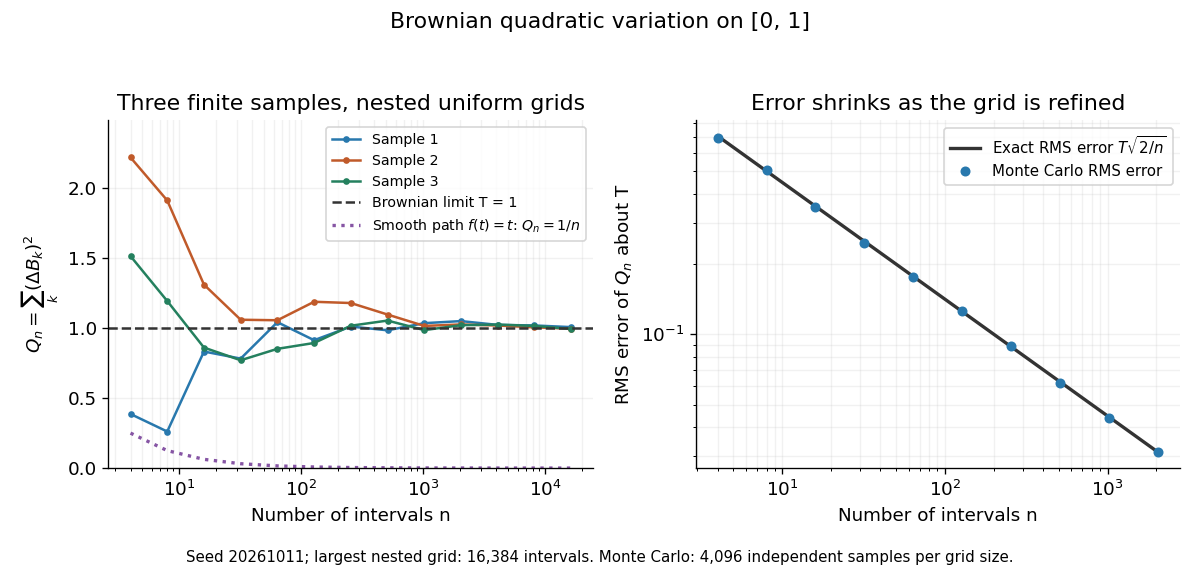
Another way to measure the roughness is quadratic variation. On , divide time into equal intervals and formWriting each Brownian increment as with independent standard normal random variables gives . Since and , the variance of is , andThis proves mean-square convergence to along uniform partitions. For and , the expectation is , the variance is , and the root mean square of the error is . For a general deterministic partition of an interval with lengths , the same calculation gives error variance , so shrinking the largest interval also suffices.
The resulting quadratic variation is , whereas the smooth function gives . This difference explains why the ordinary rules of calculus need the second-order correction in the Itô formula. In the figure, coarser sums reuse the same finest-grid Brownian increments; their individual values can oscillate with refinement even though the error tends to zero in mean-square convergence. Refining a fixed interpolating polygon forever would instead give zero quadratic variation, so the finite-grid illustration must not be confused with the limiting Brownian motion.
Historically, Brown's 1828 report describes microscopic observations made in 1827, starting with particles released from pollen and extending to inorganic materials; this challenged an explanation based solely on living matter. His observations and the later mathematical model are distinct contributions. [ref]
https://en.wikisource.org/wiki/The_miscellaneous_botanical_works_of_Robert_Brown/Volume_1/A_brief_account_of_microscopical_observations_made_on_the_particles_contained_in_the_pollen_of_plants. Brown, 1828 report, reprinted in his collected works
Einstein's 1905 paper derived a quantitative connection between kinetic theory, diffusion, and displacement. [ref]https://djalil.chafai.net/docs/M2/history-brownian-motion/Einstein%20-%201905.pdf. Einstein, 1905 paper, English translation
Wiener's 1923 Differential-Space developed integration on spaces of paths, a foundation for Wiener measure; it also acknowledges earlier work and his own previous papers. These dates mark documented contributions rather than an assertion that each subject had a single discoverer. [ref]https://djalil.chafai.net/docs/M2/history-brownian-motion/Wiener%20-%201923.pdf. Wiener, Differential-Space, 1923, sections 1 and 6
A planar self-propelled particle with translational diffusion coefficient , propulsion speed , rotational diffusion and constant angular drift has orientation correlation . Integrating this correlation twice gives the displayed mean-square displacement. For , its long-time diffusion coefficient is . The full position-angle process has the Markov property, whereas position alone generally retains orientational memory. The angular second moment refers to an unwrapped angle.
The Lévy construction builds Brownian motion on by successive independent midpoint displacements on dyadic intervals. Start with and , where has the standard normal distribution. On each dyadic interval , choose a fresh independent standard normal random variable and use the displayed midpoint rule. Conditional on the endpoints, this is the correct Brownian bridge midpoint law.
To verify the increment law, if with , the new increments are . They are Jointly Gaussian, each has variance , and their covariance is zero, hence they are independent. Induction gives all dyadic Brownian increments. The change between consecutive linear interpolants has uniform norm . The Gaussian tail bound and union bound bound the chance that this maximum exceeds by . The First Borel-Cantelli lemma and prove uniform convergence almost surely. The continuous limit has the required Brownian increments at arbitrary times by dyadic approximation.
Let for and . Integrating these Haar wavelets gives tents of height supported on the corresponding dyadic intervals. For independent standard normal random variables , the displayed series, summed level by level, is exactly the succession of midpoint displacements in the Lévy construction of Brownian motion. Its almost sure convergence is uniform, and its limit is standard Brownian motion. This gives a continuous function from Gaussian coefficients even though the unintegrated unit-variance Haar wavelet series diverges in L2 space.
With thermal initial velocities and relaxation time , the one-dimensional displacement variance is . It approaches at short times and at long times. Initial velocity preparation changes the short-time result.
For ordinary long-time diffusion, the signed mean displacement vanishes while one-coordinate mean-square displacement is and the three-dimensional mean-square radial displacement is . An rms distance is neither mean signed displacement nor cumulative path length.
For isotropic three-dimensional diffusion with coefficient , the vector mean displacement is zero, the radial RMS is and the mean radial magnitude is . The radial distribution is the Maxwell speed distribution arising from three independent Gaussian coordinate increments. State the statistic before calling a quantity an average distance; it is not the cumulative path length.
A colloidal grain in a liquid is large enough to see with a microscope, yet small enough for thermal motion to compete with its tendency to settle. In the Perrin sedimentation experiment, the equilibrium number density falls with height: a visible miniature atmosphere. Counting grains at different heights measures an energy scale; tracking their Brownian motion measures a transport rate. Connecting both to the same Avogadro constant makes the experiment a quantitative test of kinetic theory. The Wiener measure describes an idealized path law; these measurements instead test a physical model and its material parameters.
Jean Baptiste Perrin's 1909 memoir traces his sedimentation experiments to May 1908. It reports relative counts , , , at heights , , , , and compares radius estimates from Stokes settling velocity, counted grain mass, and rows of touching grains.[ref]
Mouvement brownien et réalité moléculaire by Jean Baptiste Perrin. 1909 memoir, §§15, 20–22; scan pp. 28, 41–49
The 1926 lecture describes resin precipitated from alcohol into water, washed and fractionated by centrifugation to obtain nearly monodisperse gamboge or mastic grains. Diameter and density were measured separately. A sealed slide-and-cover-glass chamber prevented evaporation; a vertical microscope resolved roughly layers through a roughly depth. Refocusing and photographing compared layer populations after equilibrium; changing temperature reversibly changed the distribution.[ref]
Discontinuous Structure of Matter by Jean Baptiste Perrin. Nobel Lectures, Physics 1922–1941; Discontinuous structure of matter, 11 December 1926, pp. 148–150
In Les Atomes (1913), Jean Baptiste Perrin restricts the eyepiece view to fewer than five or six grains and alternates observations between heights. Focus displacement requires a refractive index correction to recover actual layer separation. Horizontal positions were marked with a camera lucida, usually every , and distances calibrated with a micrometer; the polygon joins sampled positions rather than recording the intervening trajectory.[ref]
https://fr.wikisource.org/wiki/Les_Atomes/III. Les Atomes, chapter III, §§61–64
[ref]https://fr.wikisource.org/wiki/Les_Atomes/IV. Les Atomes, chapter IV, §§70–75
Take identical rigid spheres of radius , particle density and displaced liquid density , at uniform absolute temperature . Let increase upwards from a reference layer and write . The buoyancy correction gives the effective gravitational massThe actual grain mass is ; the displaced liquid subtracts from the effective gravitational mass. In a dilute, noninteracting particle suspension, the Boltzmann distribution therefore givesHere is number density and is the Boltzmann constant. Equivalently, the dilute osmotic pressure supports the grains above it: . Dividing by and integrating yields the same exponential function. No dynamic viscosity appears in this equilibrium argument. If , the population instead increases upwards; at equal densities this gravitational model predicts uniform .
A microscope counts a finite optical slab, not an infinitesimal plane. For equal viewed area and slab thickness , an ideal uniform detection window centred at givesThus equal optical volumes preserve the exponential function count ratio exactly, even for finite , provided the windows lie wholly inside the accessible chamber and have the same detection response. Unequal depth response or overlapping a boundary can corrupt this inference. Repeated observations estimate the mean count; closely spaced visits need not be independent because grains remain in view.
For an original chosen model, set , , , and . These are illustrative inputs, not Jean Baptiste Perrin's measurements. Using givesIf equal observation effort gives expected count in the reference layer, the expected counts , and higher are approximately , and . Fractions describe expected values over observations, not fractional grains. Using the actual grain mass instead of its buoyancy-corrected value would make the inferred Avogadro constant six times too small for these chosen densities.
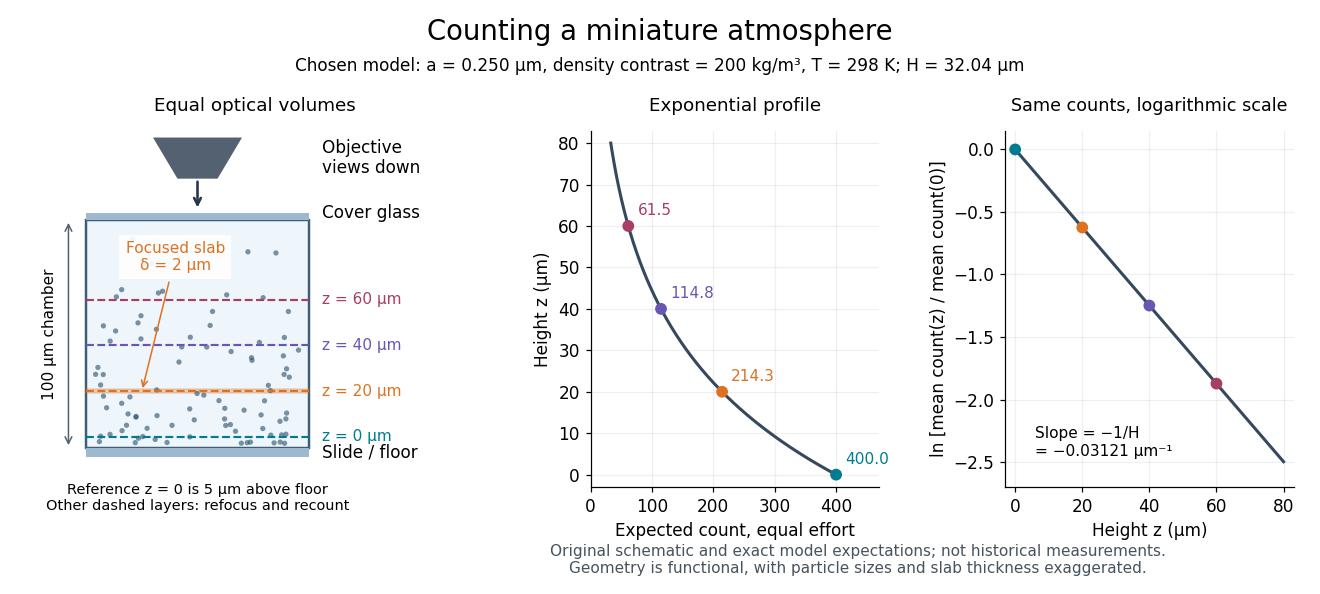
For two observed layers , define the positive logarithmic count slopeSince , where is the molar gas constant, the sedimentation scale height givesSeveral heights check whether one slope fits the whole profile. A mixture of grain radii generally gives a sum of exponential functions, with the larger grains depleted faster aloft; one apparent radius need not describe every height.
An independent readout uses horizontal displacements at lag , avoiding the vertical gravitational drift. Define the one-coordinate mean squared displacement . In a stationary liquid without horizontal advection, translational diffusion predictsA camera sees two horizontal coordinates, so its squared radial displacement has twice the one-coordinate mean. Neither observable is path length or instantaneous velocity. The bulk Stokes–Einstein relation, with dynamic viscosity , then gives
The 1926 lecture compares displacement-based and equilibrium determinations of the Avogadro constant.[ref]
Discontinuous Structure of Matter by Jean Baptiste Perrin. Nobel Lectures, Physics 1922–1941; Discontinuous structure of matter, pp. 152–154
Rotational diffusion supplies a further observable when an identifiable grain orientation can be followed; centre positions alone cannot measure it.
For the chosen model above and , the bulk prediction is . At , and the planar value is . Reconstructing from these stipulated model outputs returns by construction; this arithmetic consistency check is not experimental confirmation. Historical force comes from comparing separately measured profiles and displacements using independently checked material parameters.
The diffusive flux and gravitational particle flux provide another useful connection. With constant drag coefficient , zero vertical net flux readswhere is the downward settling velocity magnitude. With , the chosen model gives . The equilibrium profile forgets how rapidly it was established, while displacement measurements retain that rate information.
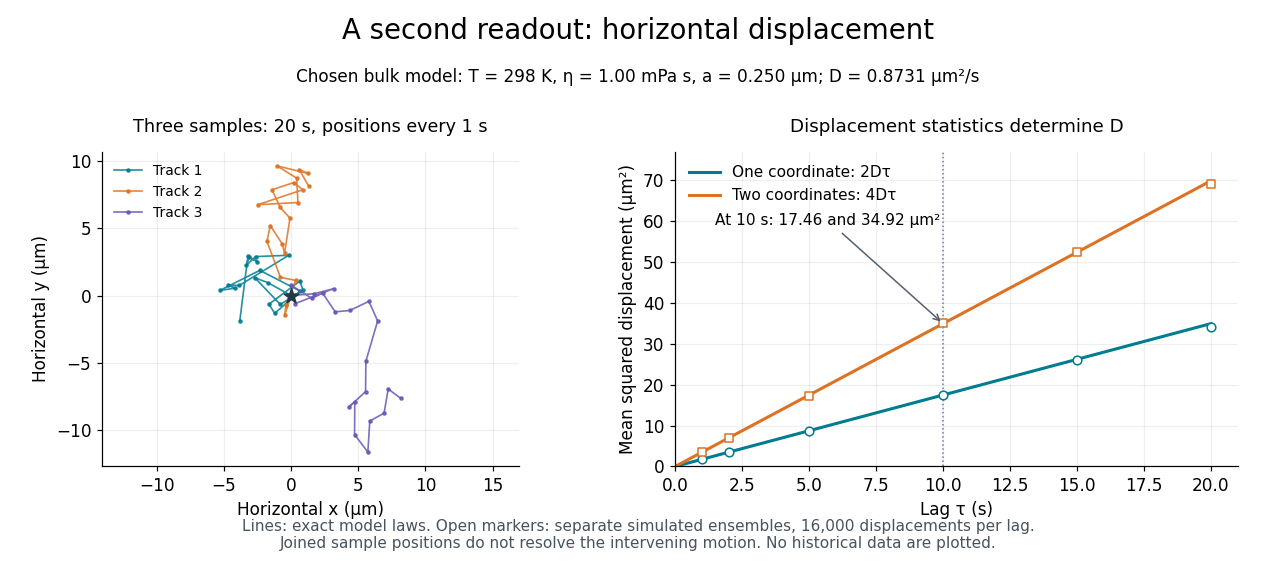
Independent horizontal displacement readout for the chosen Brownian model
. Three simulated planar tracks illustrate sampled endpoints. The other panel compares exact one-coordinate and planar mean squared displacement laws with separate simulated ensembles at each lag. These model observations do not reuse the height counts and are not historical measurements. All use . Details.At fixed measured count slope, , whereas at fixed measured diffusion coefficient, . First-order propagation of uncertainty follows by taking logarithmic derivatives:For independent small errors, the radius contributes to the relative variance of , compared with for . Shared radius and temperature calibrations make the two estimates correlated; their agreement is therefore not two wholly independent determinations. As a finite-error example, overestimating by multiplies the respective answers by and .
This explains the importance of the radius cross-checks in the 1909 memoir: testing the Stokes drag law through an independent radius estimate helps prevent circular inference.[ref]
Mouvement brownien et réalité moléculaire by Jean Baptiste Perrin. 1909 memoir, §§20–21, scan pp. 41–46
Convection must also be excluded: a residual horizontal speed adds to an uncentred mean squared displacement, making a linear fit misleading.Buoyancy changes the effective gravitational mass; a nearby no-slip wall changes the hydrodynamic resistance matrix and therefore the diffusion coefficient. These are distinct corrections. Write the horizontal resistance as , with representing wall hindrance at a specified height. Applying the Stokes–Einstein relation with that resistance givesif one mistakenly uses the bulk resistance in the inversion. A chosen would overestimate by ; this is a sensitivity example, not a correction measured in Jean Baptiste Perrin's apparatus. Normal and parallel coefficients of the hydrodynamic resistance matrix need not coincide. Stokes settling velocity near a wall can likewise bias a radius inferred using an unbounded-fluid formula.
For a passive dilute particle suspension at uniform temperature, a change of mobility alone does not change the Boltzmann distribution. In the absence of additional wall forces the correct local vertical flux is , so zero flux still gives the same sedimentation scale height. Walls can nevertheless invalidate that simple inference through adsorption, additional interaction energies, or sampling of inaccessible grain-centre positions. Optical position errors and exposure averaging also affect displacement readout; varying distance from the wall, observation lag and optical depth tests different possible errors.
For , let and . The Brownian reflection principle gives , hence . Also , with strict inequality on the positive-probability event : reflection gives its probability as . The Doob L2 maximal inequality bounds , so . At all quantities vanish and the lower inequality is equality.
// Target: probability-theory.bigb
The sign transform of standard Brownian motion is itself standard Brownian motion. The integrand is predictable because it is a Borel function of a continuous adapted process. Brownian motion spends zero Lebesgue time at a specified level: integrate over positive times. Consequently the transform's quadratic variation is , regardless of the chosen sign value at zero. The Lévy characterization of Brownian motion applies.
On a real Hilbert space , this centered jointly Gaussian process is linear in its test vector and has the displayed covariance, with independent increments in time. Equivalently choose an orthonormal basis and independent real Brownian motions , and define stochastic integration by whenever . In infinite dimension it need not be an -valued random variable; the integral is the meaningful object.
The process is a martingale in the filtration and has quadratic variation . The integral is well defined because its bracket is . The Lévy characterization of Brownian motion makes Brownian in this filtration, and stochastic-integral associativity gives the displayed representation. The resulting integrand is continuous at zero despite the singular inverse integrand.
For standard Brownian motion started at zero in , every fixed orthogonal transformation preserves the process law. Its transformed increments remain independent centred Gaussian random vectors with covariance , and its paths remain continuous. Consequently its exit law from any centred sphere is normalized surface measure. Translations give the same assertion for spheres centred at its starting point.
For standard one-dimensional Brownian motion, the Itô formula for gives this recursion. Stop at exits from to make the stochastic integral a true martingale. Gaussian tail integrability and the Doob Lp maximal inequality dominate all stopped powers on a fixed horizon, justifying the limit. Odd moments vanish and .
// Target: probability-and-statistics.bigb
The process is a martingale only for . For higher powers its finite-variation drift is , which is not identically zero. Subtracting the random compensator instead produces a true martingale on each finite horizon.
// Target: probability-and-statistics.bigb
Planar Brownian motion started away from zero does not hit zero. Stopping the harmonic function on an annulus gives probability of reaching its inner circle before its outer circle. This tends to zero as . Exhausting the plane by outer circles proves point avoidance at finite times.
// Target: probability-and-statistics.bigb
Lévy area is the antisymmetric second-level integral of multidimensional Brownian motion. For distinct independent components the integrals are also Itô integrals. Combined with the symmetric tensor , it gives the second level of enhanced Brownian motion. It is not continuously determined by the uniform norm of the Brownian path.
A Brownian motion starting outside a fixed affine subspace of codimension at least two almost surely never hits it. Choose a two-dimensional orthogonal projection annihilating the subspace's direction and with nonzero projected initial displacement. The projected process is planar Brownian motion starting away from zero, and a hit of the subspace would hit zero in that projection. The polar point for planar Brownian motion result excludes this. In three dimensions this shows avoidance of every fixed line when started outside it.
A Wiener sausage is the region swept out by a ball of fixed radius along a Brownian motion path. A deterministic continuous displacement gives the variant . On each bounded time interval it has finite expected volume: the region lies inside a ball whose radius is the path's maximum displacement plus , and the Brownian maximum has Gaussian tail bounds and finite moments of every order.
Start traps at a unit-intensity Poisson random measure in Euclidean space and attach mutually independent Brownian motions, independent of the initial measure. For a deterministic target path , independently thin initial positions according to whether their marked path comes within radius one of the target by time . The retention probability integrates, by the Tonelli theorem, to the expected volume of the sausage along . Symmetry of Brownian motion makes this the expected volume of the sausage along . The Poisson zero-count probability proves the displayed survival formula. This derives the formula directly from independent thinning, without assuming a separate marking or displacement theorem.
For the completed natural Brownian filtration, every event in the germ sigma-field of Brownian motion has probability zero or one. Indeed, an event measurable at every positive time is independent of all increments after each such time. Letting that time decrease to zero and using path continuity makes the event independent of the entire Brownian path sigma-field. Since it is itself measurable in that sigma-field, its probability equals its square.
An increment of a Brownian motion between deterministic times is . It has normal distribution and is independent of the filtration up to time . Increments on disjoint time intervals are independent. Their covariance is the length of overlap of the corresponding intervals; this also follows from the Brownian covariance kernel.
At integer times, has the same standard normal distribution for every . The event that its limit superior exceeds a fixed finite level is a tail event of the independent unit-time Brownian increments, since changing any finite initial segment contributes only a term tending to zero. The Kolmogorov zero-one law applies. Its probability is positive because each fixed-time exceedance has the same positive probability, giving a positive probability of infinitely many exceedances by the decreasing union-of-tail-events argument. Thus its probability is one. Intersecting over integer levels proves the stated divergence, without the lower iterated-logarithm bound.
The ordinary time integral of standard Brownian motion is a centered Gaussian process with continuously differentiable paths and derivative . For , its covariance is , obtained by integrating the Brownian covariance . Consequently has normal distribution . This time integral is distinct from the Itô integral with respect to Brownian motion.
The quadratic functional is finite almost surely. The Brownian half-integer sine expansion writes it as a sum of independent scaled squared standard normals. Its mean is , and its Laplace transform is determined by a hyperbolic cosine product.
The independent squared-normal series for the integrated square of Brownian motion gives the product . The half-integer cosine product reduces this to . Expanding at zero gives mean and variance .
For standard Brownian motion and , , the title gives the joint Laplace transform of the terminal square and the integrated square of Brownian motion. At the answer is . To prove the formula, use the stochastic exponentialOn every finite interval , , so the bounded local martingale criterion makes it a martingale. The Girsanov theorem changes into the zero-started Ornstein-Uhlenbeck process under the terminal density . Its terminal variance is . Multiplying by recovers the integrand on the left of the title. The Gaussian quadratic exponential moment then gives , which simplifies to the title formula. At this reduces to the Laplace transform of the integrated square of Brownian motion after Brownian scaling.
For standard Brownian motion and deterministic , the process , , is standard Brownian motion on that interval in its own natural filtration. Disjoint reversed time intervals give independent centered normal increments with the correct variances. This is different from an arbitrary random-time shift, which can depend on future data. It is also different from the time inversion of Brownian motion transformation .
For a deterministic , the processes , , and , , are independent standard Brownian motions. The first uses reversed, sign-changed past increments; the second uses future increments independent of the entire past. The first process is not generally independent of , but translating a range by preserves its Lebesgue measure pathwise.
A longitudinal Brownian field is a centered Gaussian random field withwhere is a valid transverse covariance kernel. For each fixed it is a scaled Brownian motion, and increments over disjoint longitudinal intervals are independent. Such a field drives a Markov model of wave propagation in a random medium. Its formal longitudinal derivative is Gaussian white noise in , with transverse correlations described by ; it is not in general a Brownian sheet.
The times of local maxima of a Brownian motion path are dense in the half-line almost surely, and every such local maximum is a strict local maximum. Density follows from nowhere monotonicity of Brownian motion and the extreme value theorem. Strictness follows by checking that maxima over separated rational compact time intervals are unequal; the increment across their gap supplies an independent nondegenerate normal distribution.
Almost surely, no restriction of a Brownian motion path to an interval of positive length is a monotone function. On a fixed interval, monotonicity forces the independent centered normal random variables given by every dyadic subdivision's increments to have the same sign. The probability is at most for a subdivision into pieces. A countable union over rational intervals gives the simultaneous pathwise assertion.
For three-dimensional Brownian motion, every radius and every initial point satisfyIf the initial point is on one of the spheres, it is already a hit at time zero. If it is inside a lattice-centered open ball, its eventual exit hits that sphere. Otherwise choose at each integer time a nearest lattice center. The current displacement from it has norm at most , so the multivariate normal distribution of the next unit increment gives a uniform positive chance of entering its radius- open ball. The geometric tail bound from a uniform escape probability makes eventual entry certain, and continuity forces a boundary crossing. This periodic-family recurrence does not contradict the Brownian sphere-hitting probability in dimension three for one fixed sphere.
For every fixed mesh , independent increments with the normal distribution imply increments of absolute value greater than one occur infinitely often almost surely, by the second Borel-Cantelli lemma. A countable intersection over contradicts uniform continuity on .
A filtration is a Brownian filtration for when is an adapted process and each future increment is independent of . The natural filtration of a Brownian motion has this property. Arbitrary enlargement by future information need not preserve it.
The natural Brownian filtration is the natural filtration generated by a Brownian motion. Its usual augmentation adds null events and makes it right-continuous; the Brownian martingale representation theorem holds for this augmented natural filtration. A larger Brownian filtration can preserve independence of future increments while containing additional randomness, so it need not have martingale representation with respect to the specified Brownian motion.
A martingale representation theorem states conditions under which every martingale in a filtration can be represented as a stochastic integral with respect to one or more fundamental martingales.
The conditional expectation of at time is , by independent Brownian increment. Itô's formula cancels its time derivative against its second spatial derivative and leaves the displayed stochastic integral. The integrand is bounded, so Itô isometry verifies its square integrability.
Every square-integrable random variable measurable with respect to a Brownian filtration can be written as its expectation plus an Itô integral against that Brownian motion. Equivalently, every square-integrable martingale in that filtration has the formfor a predictable square-integrable process .
In the completed natural Brownian filtration, a bounded continuously differentiable with bounded derivative satisfiesThe integrand is unique up to -almost everywhere equality. Gaussian integration by parts first gives the duality between the payoff and every square-integrable Itô integral. The Brownian martingale representation theorem then identifies the integrand as the projection of onto the predictable processes in the product space. This explains the conditional expectation in the formula, rather than a nonadapted terminal derivative.
For every and standard Brownian motion ,is a positive martingale. Applying Itô formula cancels the drift, and its expectation is one by the moment-generating function of the normal distribution.
For Brownian motion started at , the time integral is a Gaussian random variable withThe variance follows by integrating the covariance kernel twice.
The displayed continuous centered Gaussian process, with value zero at time zero, has the Brownian covariance kernel. Hence it is a Brownian motion in its own natural filtration. More generally, replacing three by gives covariance for , so three is the only nonzero valid coefficient. Its conditional future increment in the original Brownian filtration is , and is generally nonzero.
The diffusion coefficient sets the linear growth of mean-square displacement. In one dimension the convention is common.
For a stationary zero-mean velocity with an absolutely integrable velocity autocorrelation function , the diffusion coefficient is its time integral. Indeed, differentiation of the mean squared displacement identity gives , and the right side tends to the displayed integral. In the equilibrium generalized Langevin equation, this gives whenever stable relaxation and the required integrability hold. The formula is named after Melville S. Green and Ryogo Kubo.
A mean squared displacement is the expected value of a squared position change over a specified time lag. For isotropic free diffusion in dimensions, it equals . A nonzero mean drift contributes its squared displacement as well as the displacement variance; specifying the tracked coordinates and whether the mean is subtracted is essential.
The unnormalized autocorrelation function of a stationary velocity. For zero mean, is the velocity variance. It is different from the normalized autocorrelation function often used in time series.
If , integrating the two-time covariance over the square givesThis identity connects a mean squared displacement to the Green-Kubo formula for diffusion.
For isotropic Brownian motion started at zero with independent coordinate variances , the Gaussian distribution has density . Integrating the radius with spherical volume element gives . The root mean square displacement is instead , and the mean vector is zero. None of these is the microscopic path length.
Solutal diffusivity is the diffusion coefficient governing transport of a dissolved constituent down its concentration gradient. For uniform and a stationary solvent, the diffusion equation is . It need not equal the thermal diffusivity.
If is Brownian motion in and is an orthogonal matrix, then is Brownian motion. Its increments remain independent centered Gaussian vectors and have covariance .
Two independent one-dimensional Brownian motions started at and meet at the first time a Brownian motion started at hits zero. The meeting time has densityAn orthogonal sum coordinate is independent of this hitting time and makes the meeting position conditionally .
Wiener measure is the probability distribution of Brownian motion on a continuous-path space, usually or .
There exists a probability measure on under which the coordinate process is standard Brownian motion, and its distribution there is unique. Construct consistent centered Gaussian finite-dimensional laws with covariance and use the Kolmogorov extension theorem. The fourth increment moment supplies a continuous modification by the Kolmogorov continuity theorem. Its independent increments and normal increment distributions are unchanged. Uniqueness follows because coordinate evaluations at rational times generate the Borel sigma-algebra of continuous-path space.
On , the Cameron-Martin space consists of the absolutely continuous functions with and . Its norm is
Translation of Wiener measure by a path is equivalent to Wiener measure exactly when belongs to the Cameron-Martin space of Wiener measure. In that case the density isTranslation by any continuous path outside that space produces a singular measure.
If with deterministic , the finite-time Cameron-Martin theorem densities have second moments bounded uniformly in time. Their uniformly integrable martingale limit is the strictly positive displayed density, giving equivalence on the full infinite continuous-path space. Finite-time densities alone do not guarantee such a global density: a nonzero constant drift has infinite energy and its infinite-horizon path law is singular, distinguished by the limiting ratio .
For the Cameron-Martin space of Wiener measure path , the Cameron-Martin theorem says that translation of Brownian motion by this linear function changes its law through time by the density
On every compact time interval, a Brownian path is almost surely a Hölder continuous function of every exponent , and of no exponent . In particular, as for every after choosing a Hölder exponent strictly between and .
The zero set of one-dimensional Brownian motion is almost surely closed, uncountable, and has zero Lebesgue measure. The last fact follows from Tonelli theorem because for every .
If is standard Brownian motion, then is also standard Brownian motion. More generally, applying an orthogonal transformation to a multidimensional Brownian motion preserves its law.
For and ,Changing measure with the density turns into Brownian motion. At the density equals , and Brownian motion hits almost surely.
A Bessel process of dimension is the radial part of -dimensional Brownian motion. Away from zero it solves the stochastic differential equationThis equation also defines noninteger dimensions through its weak solutions.
A dimension-two Bessel process starting at has the displayed marginal law, where are independent standard normal random variables. Take the norm of a planar Brownian motion starting at . Planar Brownian motion avoids a fixed point, so the norm stays positive; Itô formula gives drift and a martingale term of bracket . The Lévy characterization of Brownian motion identifies that term as its driving Brownian motion. The squared radius divided by has a noncentral chi-squared distribution with two degrees of freedom and noncentrality .
A squared Bessel process of dimension is a nonnegative continuous solution of the displayed stochastic differential equation. It extends the squared radial part of integer-dimensional Brownian motion to arbitrary nonnegative dimensions. Before hitting zero its square root solves . At dimension zero, a process started at zero remains there. The coefficients are not Lipschitz at zero, so positivity or uniqueness must not be justified by a global Lipschitz theorem.
For independently driven nonnegative squared Bessel processes , put . Where , use Brownian weights and . Where , fill the weights with . Their squared norm is always one and their cross-variation is zero, so their stochastic integral is Brownian motion by the Lévy characterization of Brownian motion. Multiplying by recovers the sum's martingale part even at zero, and the drifts add to .
For , couple and from positive , killing each at zero. Their sum has no Brownian term and increases, so simultaneous extinction is impossible. The ratio has time-changed generator . Its scale density is , integrable at both endpoints. Optional stopping of its normalized scale function at the first extinction gives the displayed regularized incomplete beta function. At this is Cardy's formula.
For , the drift is globally Lipschitz and bounded. Solve its equation strongly for the prescribed Brownian motion, and stop at the first hit of . Local uniqueness makes these stopped solutions agree up to the larger threshold; their stopping times increase as the threshold decreases. With , Itô's formula for gives on every finite horizon. Hence the patched lifetime is infinite. Localization away from zero proves pathwise uniqueness of the positive global solution. Uniqueness before a stopping time refers to the stopped solution, not to arbitrary unconstrained continuations afterward.
The radial part of three-dimensional Brownian motion started away from the origin is a Bessel process of dimension three. The radial Laplacian is , so the Itô formula gives the displayed equation. The radial martingale has unit quadratic variation rate and is Brownian motion by the Lévy characterization of Brownian motion. The reciprocal is a local martingale. Stopping it on gives . Letting shows that zero is not hit.
For started at a point of radius one, its radial process has the law of the inverse-clock process , where inverts . The logarithmic growth of an exponential Brownian clock with positive drift gives , whereas . Substituting proves the displayed almost sure escape rate and divergence of the radius. Independently, Brownian scaling gives the same rate in probability; if an almost sure logarithmic rate is already known to exist, that identifies its value.
Couple and from , with . Suppose their finite lifetimes end at zero and . Their difference is positive and has derivative , so . For , the Itô formula givesThe normalized scale function of a one-dimensional diffusion is a bounded local martingale. Its finite quadratic variation and the divergent clock force on simultaneous extinction; on strict extinction . Its terminal value is therefore the strict-extinction indicator, proving the formula by optional sampling theorem. For SLE boundary images, ; this compares strict and simultaneous boundary swallowing times for .
For a three-dimensional Bessel process started at one, stays strictly positive and satisfies . The Itô formula makes its reciprocal a local martingale, but for . Thus the reciprocal is a strict local martingale. It can deflate the market with constant bank account and stock price without yielding a true pricing density for the bank account.
For a Bessel process of dimension , started at , the Itô formula giveson its stochastic interval before hitting zero. Thus the power is a local martingale after localization away from zero. For this interval is the whole lifetime; at the power is constant. The unqualified assertion fails for a reflecting Bessel process of dimension one, which acquires local time of a semimartingale at zero.
For Brownian motion started at radius , the displayed process is a continuous local martingale. It is a bounded true martingale when , but a strict local martingale when or . In the latter case the boundary is outside the starting point, so stopping does not remove the singularity at the origin. Brownian scaling gives ; when , the stopped expectation tends to .
For a Bessel process of dimension started at , its scale function of a one-dimensional diffusion gives for . In particular, almost surely. The minimum is attained because the process tends to infinity; the hitting formula alone already implies positivity of the infimum.
A Bessel process of dimension started away from zero hits zero almost surely exactly when . For , its scale function of a one-dimensional diffusion is ; for it is . The boundary hitting probability from a diffusion scale function then gives the classification by taking the inner boundary to zero and the outer boundary to infinity.
For , put and . It is nonnegative on , vanishes at both endpoints and solves on . Optional stopping at gives uniformly as . Thus the limiting exit to zero or occurs in finite time, not merely as an asymptotic approach to zero. Scale probabilities give ; letting gives almost sure finite hitting of zero.
If is a Bessel process of dimension started at and , thenis a Bessel process of dimension started at . This follows from Brownian scaling in the stochastic differential equation and uniqueness in law.
For , use the clock . After the inverse time change, the Dambis-Dubins-Schwarz theorem givesso the time-changed process is a Bessel process of dimension . Its lifetime is , which is finite almost surely exactly when .
The strong law for Brownian motion gives . For every , eventually . Integrating these bounds, taking logarithms and dividing by squeezes the growth rate between and . Let . The corresponding inverse clock grows like .
One-dimensional reflected Brownian motion on has the same law as . The Tanaka formula represents it as a Brownian motion plus a nondecreasing local time of a semimartingale that grows only at zero.
Apply the Skorokhod reflection map on the half-line to Brownian motion with negative constant drift and positive variance parameter . The result is kept nonnegative by a regulator acting only at zero. It has a stationary distribution, unlike zero-drift reflection on the whole half-line.
The stationary law is the law of . Let . The Exponential martingale for Brownian motion , stopped on first hitting , is bounded by . On no hitting, the driving path tends to minus infinity. Dominated convergence and optional stopping therefore give . The reflected process started at zero converges to this supremum law: its value at time has the law of the driving path's maximum up to , by reversing the increments. The resulting density is for .
The occupation time of a measurable set through time is . The occupation-times formula expresses such integrals through local time of a semimartingale. Recurrence and the Strong Markov property imply that one-dimensional Brownian motion spends an unbounded total time in every nonempty open interval.
A one-dimensional Brownian motion spends an infinite total time in every nonempty open interval almost surely. To prove this for after first hitting zero, alternate exits from that interval with returns to zero. By recurrence of one-dimensional Brownian motion all these stopping times are finite, and the Strong Markov property makes the successive exit durations independent and identically distributed random variables that are strictly positive. Some fixed positive duration is exceeded with positive probability, so the Borel-Cantelli lemma makes the sum of the durations infinite. Translate and scale for other intervals. In particular, if a nonnegative function is bounded below by a positive constant on such an interval, its infinite-horizon Brownian occupation time integral diverges. Recurrent visits alone, without this duration argument, would not prove divergence of an integral.
For any real constant , one-dimensional Brownian motion repeatedly returns to zero. Consider successive segments from zero until exiting , separated by returns to zero. Their capped durations are independent identically distributed positive bounded random variables by the Strong Markov property, so their sum diverges by the strong law of large numbers. On each such segment . Thus the exponential clock has infinite lifetime, despite arbitrarily deep negative excursions.
For a continuous semimartingale with local time of a semimartingale ,for every nonnegative measurable function .
Planar Brownian motion is the random vector formed from two independent standard one-dimensional Brownian motions.
For a start in the punctured unit disc, the logarithmic lift starts at in the upper half-plane. Local conformal invariance of planar Brownian motion changes its clock by . That clock is finite at the disc exit because the stopped path is compact and avoids zero. Its terminal real coordinate is therefore the usual upper-half-plane Cauchy exit law from a Brownian half-plane. Subtracting gives the displayed winding law. Its first absolute moment diverges logarithmically, even though the final point modulo angle lies on a compact circle.
For planar Brownian motion started at , let be its continuous unwrapped angle, initialized at zero. Then converges in distribution to the standard symmetric Cauchy distribution, with density . The angle records all completed turns rather than a bounded principal argument. The assertion is a convergence in distribution at deterministic times; it does not assert convergence of sample paths. A precise statement appears as Theorem 7.31 in Mörters and Peres, Brownian Motion.
A planar Brownian motion range has zero two-dimensional Lebesgue measure almost surely. Assuming finite expected area, Brownian scaling gives half that expected area for each half-time range. Inclusion-exclusion then makes their expected overlap zero. Translate their ranges by the midpoint position; the independent Brownian arms at a deterministic time make the expected overlap the integral of the squared point-hitting probabilities for a half-time range. Those probabilities vanish almost everywhere, so the half-time expected area, and hence the full-time expected area, vanish. This argument does not assert zero hitting probability for every individual point solely from an almost-everywhere integral conclusion.
Started at radius one, planar Brownian motion avoids the origin, and its logarithmic radius is a continuous local martingale because the logarithmic potential is harmonic away from zero. It is a strict local martingale: at deterministic , the angular average of a logarithmic potential gives , whereas the initial value is zero. Absolute integrability follows from integrability of near zero and the Gaussian tail. Its positive expectation does not contradict nonnegative-local-martingale bounds, since this process takes both signs.
Planar Brownian motion started away from zero almost surely avoids zero. On every finite time interval its continuous path therefore has positive minimum modulus, making the logarithmic stochastic integral well-defined. Since complex quadratic covariation satisfies , analytic Itô calculus gives the displayed exponential identity without a drift correction. Its real part is the change in logarithmic radius and its imaginary part is the continuous accumulated argument, including every winding. This is a pathwise logarithmic lift, not a single-valued logarithm on the entire punctured plane.
For planar Brownian motion started at , continuous winding angles sampled at the displayed radii have independent stationary increments. At , apply the Strong Markov property, rotate by the current angle, and rescale space by and time by . The future radial-level winding increment has the original law and is independent of the past. The logarithmic radius and winding angle are independent Brownian coordinates on the common clock . At radial passage they are therefore and , where is a Brownian first-passage time. Its Laplace transform gives the displayed characteristic function. The level process is a symmetric Cauchy process; replacing the passage clock by its right-continuous version supplies a càdlàg modification without changing any fixed-level law.
For independent coordinate Brownian motions, the stochastic area with the stated orientation is . Its bracket is . Reversing orientation changes its sign but not its law or quadratic variation.
The radial martingale and the planar Brownian stochastic area have common bracket and zero cross variation, because their integrand vectors and are orthogonal. The Itô formula also gives .
Articles were limited to the first 100 out of 207 total.
Articles by others on the same topic

Brownian motion, also known as particle theory, is the random movement of small particles suspended in a fluid (like air or water) resulting from their collision with the fast-moving molecules of the fluid. This phenomenon was named after the botanist Robert Brown, who observed it in 1827 while studying pollen grains in water. The key characteristics of Brownian motion are: 1. **Randomness**: The movement is erratic and unpredictable.



Small microscopic visible particles move randomly around in water.
If water were continuous, this shouldn't happen. Therefore this serves as one important evidence of atomic theory.
The amount it moves also quantitatively matches with the expected properties of water and the floating particles, was was settled in 1905 by Einstein at: investigations on the theory of the Brownian movement by Einstein (1905).
This suggestion that Brownian motion comes from the movement of atoms had been made much before Einstein however, and passed tortuous discussions. Subtle is the Lord by Abraham Pais (1982) page 93 explains it well. There had already been infinite discussion on possible causes of those movements besides atomic theory, and many ideas were rejected as incompatible with observations:The first suggestions of atomic theory were from the 1860s.
Further investigations eliminated such causes as temperature gradients, mechanical disturbances, capillary actions, irradiation of the liquid (as long as the resulting temperature increase can be neglected), and the presence of convection currents within the liquid.
Tiny uniform plastic beads called "microbeads" are the preferred 2019 modern method of doing this: en.wikipedia.org/wiki/Microbead
Original well known observation in 1827 by Brown, with further experiments and interpretation in 1908 by Jean Baptiste Perrin. Possible precursor observation in 1785 by Jan Ingenhousz, not sure why he wasn't credited better.
Observing Brownian motion of micro beads by Forrest Charnock (2016)
Source.