For a real matrix and a vector , exactly one of the following systems has a solution:The linear inequalities here are componentwise. In the first system is nonnegative; in the second system is unrestricted in sign. The second system is a certificate that the first has no feasible point. This nonnegative-equations alternative is developed in Boyd and Vandenberghe, Convex Optimization slides, §5.34.
Build the target, or separate it. Write the columns of as . Then is a conic combination: its coefficients must be nonnegative, but need not sum to one. The obtainable targets form the finitely generated coneA solution explains how to build from those columns. A certificate instead defines a linear functional . The condition says that its dot product with every generating column is nonnegative, and hence with every point of . But places the target strictly on the other side of the hyperplane . Thus belongs to the dual cone of and rules out every allowed conic combination at once.
A certificate that can be checked by eye. Take the identity matrixHere is the nonnegative orthant. The equation forces , violating . The certificate givesThe linear functional simply reads the first coordinate: all allowed column combinations have a nonnegative first coordinate, while has first coordinate . For comparison, the target is obtained with .
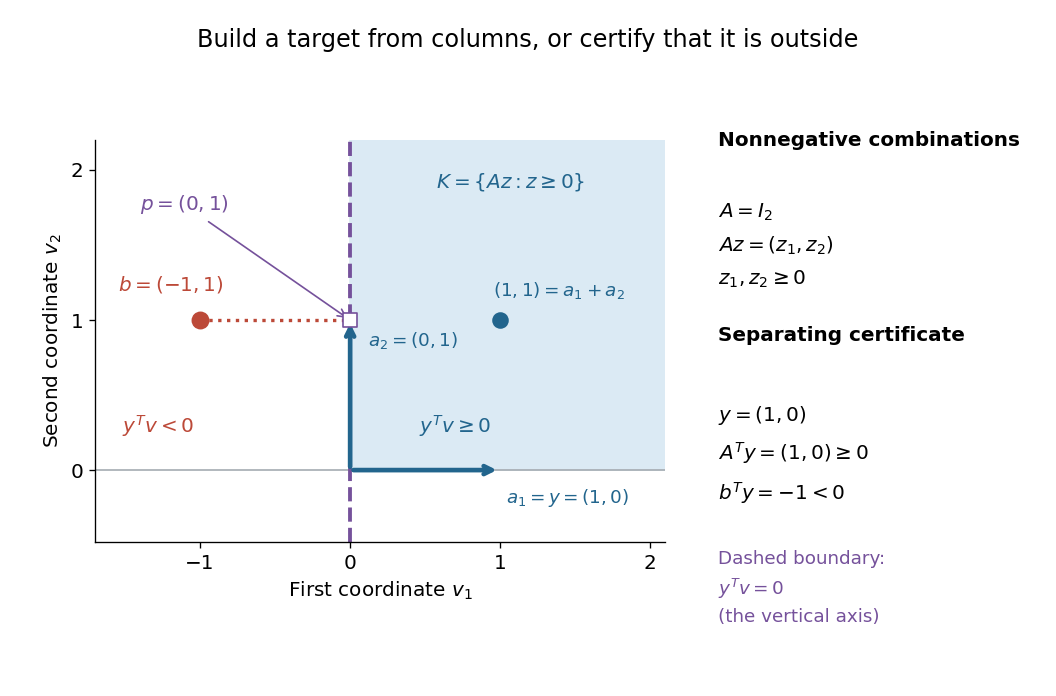

Why this is useful and striking. A successful search can exhibit one feasible point; an unsuccessful search alone cannot explain why every candidate fails. Farkas' lemma guarantees an equally concrete witness of impossibility for this finite linear problem. Once is supplied, verification needs only matrix multiplication, sign tests and one dot product. The same idea gives a Farkas certificate for linear inequalities and underlies linear programming duality.
Brief geometric proof. The two systems cannot both hold, because they would implyFor existence of a certificate when , closedness of finitely generated cones makes a closed convex cone, so separation from a closed convex cone supplies and for every . Testing each column gives . Concretely, let be the Euclidean projection onto a convex set of onto and set . The projection inequality gives for . Testing and gives , whence . In the example, and . Alternatively, the Fenchel-Moreau theorem applied to the cone's indicator functional proves the same separation through its polar cone.
An original historical source is Julius Farkas's [ref]
https://geodesic.mathdoc.fr/item/JRAM_1902__124_149129/. Theorie der einfachen Ungleichungen, Journal für die reine und angewandte Mathematik 124 (1902), pp. 1–27
. The linked archival record verifies the author, title and publication details.Suppose a linear program has a Farkas' lemma certificate , , . A purported feasible point of , would imply . Hence every relaxation below the displayed positive threshold remains infeasible. For rational inputs, bounds on the encoding length of a certificate supply the precision gap used by the ellipsoid method.
Let and . For unrestricted , the system of linear inequalities has no feasible point if and only if there is a vector withThe entries are nonnegative Lagrange multipliers for the rows. Multiplying inequalities by them preserves their direction; the condition cancels every variable, leaving the contradictionThis is a Farkas' lemma alternative for non-strict inequalities; no strict-feasibility assumption is needed. See Boyd and Vandenberghe, Convex Optimization (2004), §5.8.3, pp. 261–262.
Three individually possible requirements, jointly impossible. Suppose two unrestricted real coordinates , drawn as in the diagram, must satisfyWrite every row in the same direction:Then and . The nonnegative weighted sum, with Lagrange multipliers , is visiblyEach individual requirement defines a half-space in the plane. Even every pair has a feasible point: satisfies the first two, the first and third, and the second and third. Their common intersection is empty, because the first two force , while the third demands at most .
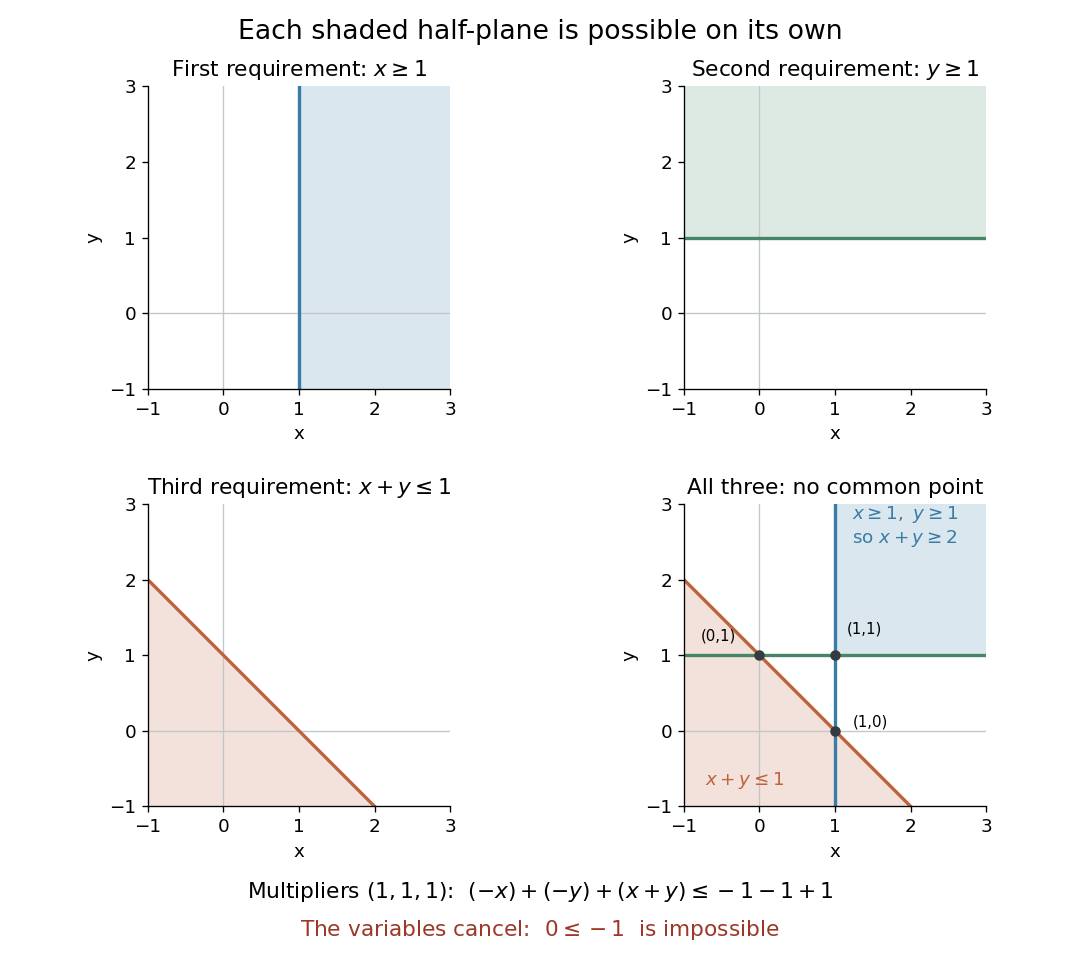

Why cancellation is necessary for unrestricted variables. A nonzero linear functional can be made arbitrarily positive or negative by varying unrestricted , so alone would not yield a contradiction. Equality is essential here. If is also imposed, the sufficient certificate becomes , , , because then . This is the sign convention used in robust infeasibility under uniform constraint relaxation. One can instead append the rows and use the equality certificate on the enlarged system. Reversing all constraints to reverses the scalar sign to , as in the normalized integer Farkas infeasibility gap.
Checking a solver's infeasibility claim. A returned Farkas certificate for linear inequalities gives a short verification procedure: compute and , and check the three displayed conditions against the original constraints. Any positive multiple is another certificate; division by normalizes to . With rational numbers as data and certificate, the tests can be exact. With floating-point arithmetic, a small residual is a diagnostic rather than an exact cancellation: unrestricted can amplify a nonzero residual without bound. A rigorous certificate therefore needs exact cancellation or justified error bounds and additional bounds on the variables. The strict negative scalar is the margin of contradiction.
The same weighted sums give dual bounds. For the linear program maximizing over unrestricted with , any satisfying givesfor every feasible point. Minimizing over these multipliers is the dual linear program; the bound itself is weak duality. For example, maximize subject to , , . The multipliers give the upper bound , attained at . The infeasibility example above uses the same row directions, but lower bounds of on both coordinates. Its multipliers cancel the objective function as well as the variables: with would bound zero by a negative number. Thus impossibility and linear programming optimality certificates use the same arithmetic. See Boyd and Vandenberghe, Convex Optimization slides, §§5.32–5.35 for infeasibility as a dual alternative.
Why every inconsistent system has such a certificate. Introduce a slack variable vector and write . Split the unrestricted vector as with . Applying Farkas' lemma to the column matrix gives , , and . The first two conditions together are exactly . This reduction explains both the equality and the nonnegative row multipliers.
Suppose have integer entries of absolute value at most , has columns, and is infeasible. A Farkas certificate for linear inequalities can be chosen with , , and the displayed lower bound. Normalize an infeasibility certificate to obtain the last equality, then maximize over the resulting compact linear polyhedron. A maximizing extreme point has at most positive entries: otherwise the augmented columns on its support would be dependent, allowing feasible perturbations in both directions. For its independent supported columns, select independent equations. Cramer's rule expresses the supported entries with a common nonzero integer determinant denominator. That determinant has absolute value at most . The positive value therefore has a positive integer numerator over a denominator of at most this size, proving the bound.
Articles by others on the same topic
There are currently no matching articles.