Short one share at time zero and invest the one hundred pounds received in the bank asset. The initial net investment is zero. After one period, repurchasing the share leaves . Since and , this payoff is strictly positive in both states. Hence this is an arbitrage opportunity.
The risk-neutral probability must make the expected stock multiplier equal the bank multiplier:Both up and down paths have positive probability under this measure. A self-financing portfolio's discounted value is then a Q-martingale, since the discounted bank asset is constant and the discounted stock is a martingale. An arbitrage with zero initial wealth would have nonnegative terminal value and positive value in some possible state, giving a strictly positive Q-expectation and contradicting its zero discounted initial value. Thus the market with is arbitrage free.
Retain the whole price history when calculating the arithmetic average. The Asian option payoffs at expiry areIn particular and have the same terminal stock price but different averages and payoffs. The average is an additional state variable; the terminal stock nodes cannot be merged for this claim.
Use and discount one step by . At the up node, and immediate exercise pays . Continuation is worth . At the down node, and immediate exercise pays , while continuation is . Thus the American put option should be exercised at either time-one node, and
At time zero, exercise pays , while continuation is worthTherefore exercise at time zero is optimal, and pounds.
The discounted unexercised option-value process is not a Q-martingale: already . It is the Snell envelope of the discounted exercise payoff, hence a supermartingale in general, with strict decrease of expected value when immediate exercise beats continuation. Stopping at an optimal exercise time restores the stopped martingale property; that is a different assertion from the unexercised price being a martingale.
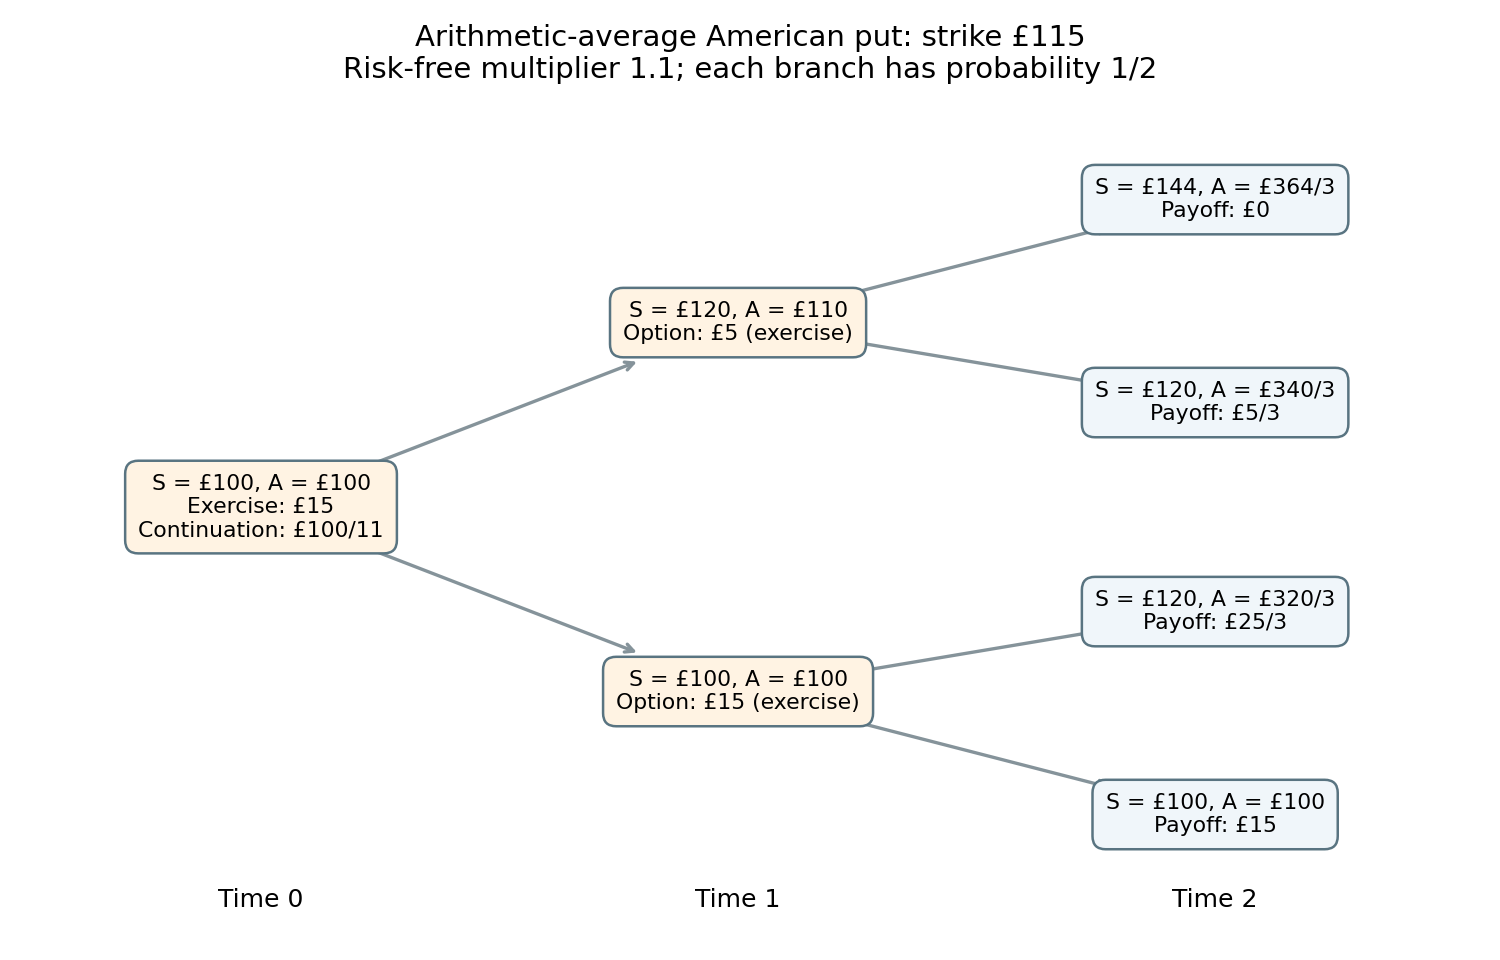
The American arithmetic-average put: four terminal histories are retained because ud and du have different average prices. Backward induction selects immediate exercise at both time-one nodes and at time zero.
Details. 
Articles by others on the same topic
There are currently no matching articles.