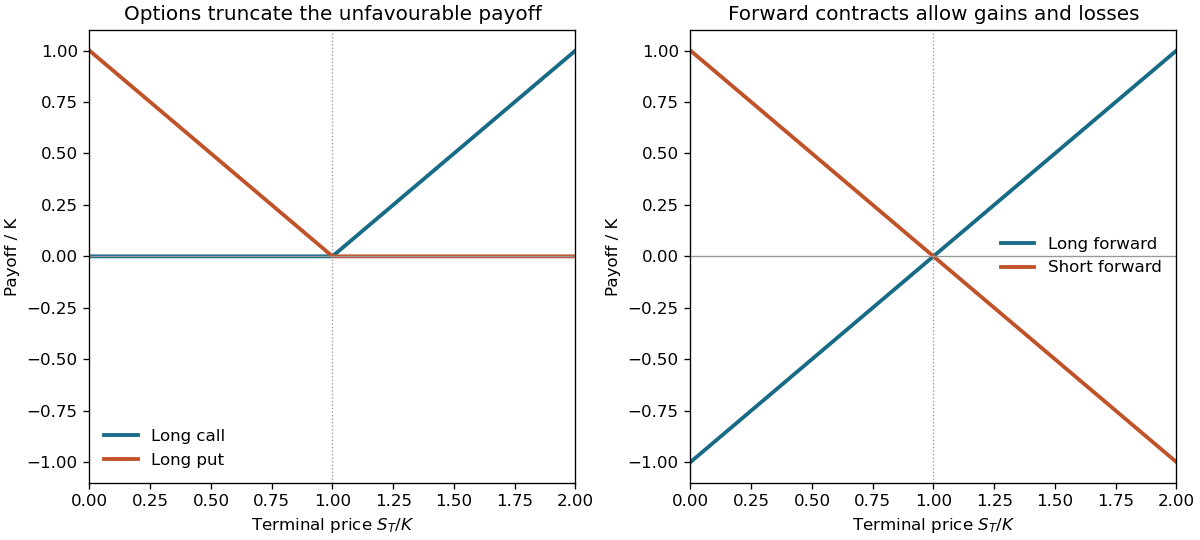
The call is zero below K and then rises with slope one; the put falls with slope minus one below K and is zero above it. A long forward instead has FTlong=ST−K and a short forward has FTshort=K−ST. Both are straight lines crossing zero at K, with negative as well as positive outcomes.
The option's exercise right truncates the unfavourable side, whereas the forward is an obligation. These are payoffs, not total profits: an option premium and its financing cost have not been subtracted. A newly agreed fair forward may have zero initial value while still having a nonzero future delivery price.