In a finite-state discrete-time financial market, a replicable terminal financial payoff has the displayed value under any equivalent martingale measure for the bank account numéraire. Here represents current information and conditional expectation averages over future states. The self-financing portfolio's discounted portfolio wealth is a martingale, so its current value equals the discounted expectation of its terminal value. In an incomplete market, nonreplicable claims need not have a unique price; continuous-time extensions require further conditions on admissible trading strategies and integrable discounted wealth.
For the European call option in the example,Discounting the physical expected value instead gives when , or when . Those amounts describe discounted physical expectations, not the replicating portfolio's cost. Holding fixed is crucial: changing beliefs can influence traded prices in a richer financial market model.
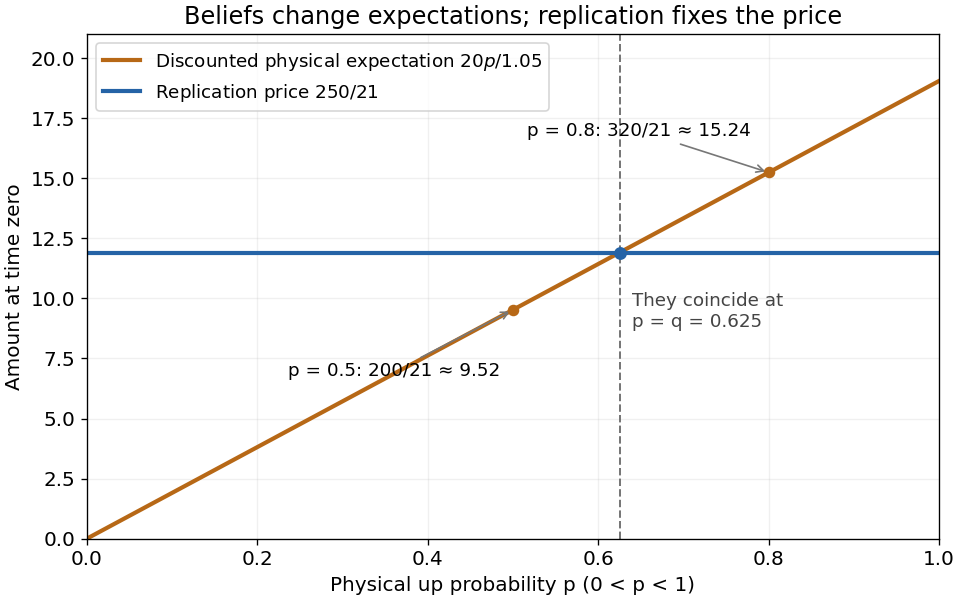
Physical expectations vary with beliefs while the one-step replication price stays fixed
. Details. 
For a non-dividend-paying traded asset and bank account , delta hedging sets the share holding to . Its bond value is . Itô's formula and the self-financing condition give the displayed pricing equation on the whole real line. The linear drift change of measure supplies risk-neutral dynamics , so the same price is the discounted conditional payoff expectation under the usual admissibility and integrability hypotheses.
Articles by others on the same topic
There are currently no matching articles.