
In the convention with constant term , Parseval's identity isOnly the first harmonic contributes here, so
The curve starts at and initially rises. It crosses zero at and , attains its maximum at and minimum at , then returns to . These follow either from the shifted sine form or from .
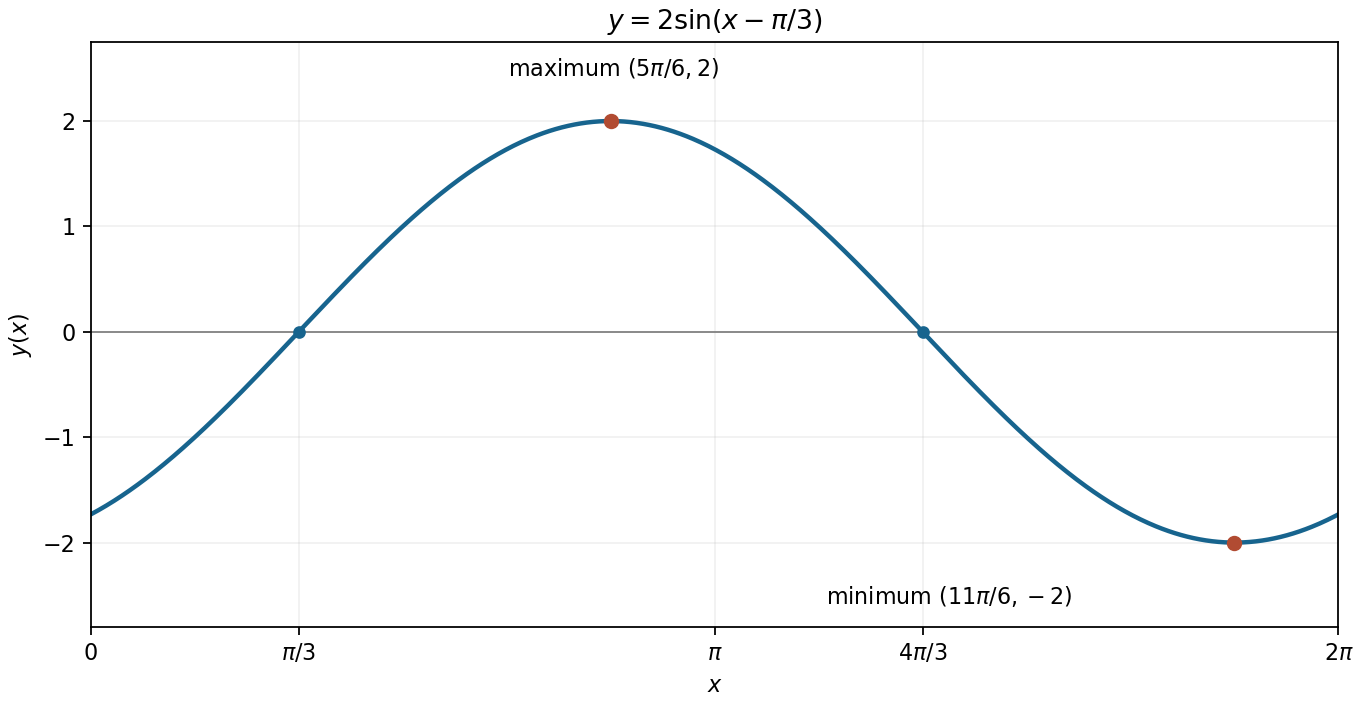
The unique periodic sinusoidal response, with its maximum, minimum and zero crossings
. Details. 
Using the sine addition formula, combine the surviving modes:It has amplitude and a phase delay . The full general solution would add , but this exponential is periodic only for , so the displayed periodic solution is unique.
The constant coefficient is . For every the two mode equations arewhere is the Kronecker delta. The first equation gives , so the second becomes . HenceNo other modes survive. This is the single-frequency case of the Fourier solution of a first-order equation with periodic forcing.
Fourier orthogonality isolates a coefficient. Multiplication by and integration over annihilates the constant, all cosine terms and all sine terms except the one with , whose squared integral is . Thus the corresponding coefficients on the two sides must agree for each positive integer .
Multiplication by works in the same way, while integration against the constant mode extracts . This is the uniqueness of the Fourier coefficients; it does not follow from comparing a few point values of the series.
Differentiate the Fourier series term by term and collect cosine and sine terms. Substitution into the equation givesFor a smooth periodic solution, differentiation of the series is justified. Alternatively, multiply the differential equation by each trigonometric mode and integrate by parts; periodicity cancels the boundary terms and gives the same coefficient constraints without first differentiating an infinite sum.
In the real Fourier series convention for period ,where the Fourier coefficients areThese formulas apply to integrable periodic functions. Writing equality at each point requires appropriate convergence hypotheses; the periodic solution sought below is smooth, so its series causes no such difficulty.
The time already elapsed since the noise is minutes. Conditional on a particular noise time and on still being in progress, memorylessness of the exponential distribution givesThis law does not depend on . Averaging over the conditional distribution of therefore leaves the same remaining-time law. HenceThe elapsed minutes are not subtracted from the original mean; the exponential residual lifetime has the same mean after any elapsed duration.
Use the lower limit for the inner integral:HenceThe prefactor is the probability that interruption occurs; the remaining exponential is its conditional positive tail. This is the positive difference of independent exponential waiting times. The exponent is dimensionless because both and are measured in minutes.
There are unlisted articles, also show them or only show them.