Apply Itô's formula to for positive initial value . The drift correction is , soThis is geometric Brownian motion. Under the physical probability measure, has the standard normal distribution. For positive volatility,The drift here is , because this is a physical bankruptcy probability. The risk-neutral measure will instead give drift for pricing. If , the value is deterministic and the default probability is the indicator of ; the usual positive-volatility convention is used in the remaining formulas.
In the Merton model, the total equity payoff is , exactly a European call option on the company value with strike . Total debt pays . The first payoff has slope zero below and slope one above it; the second has slope one below and is constant above it.
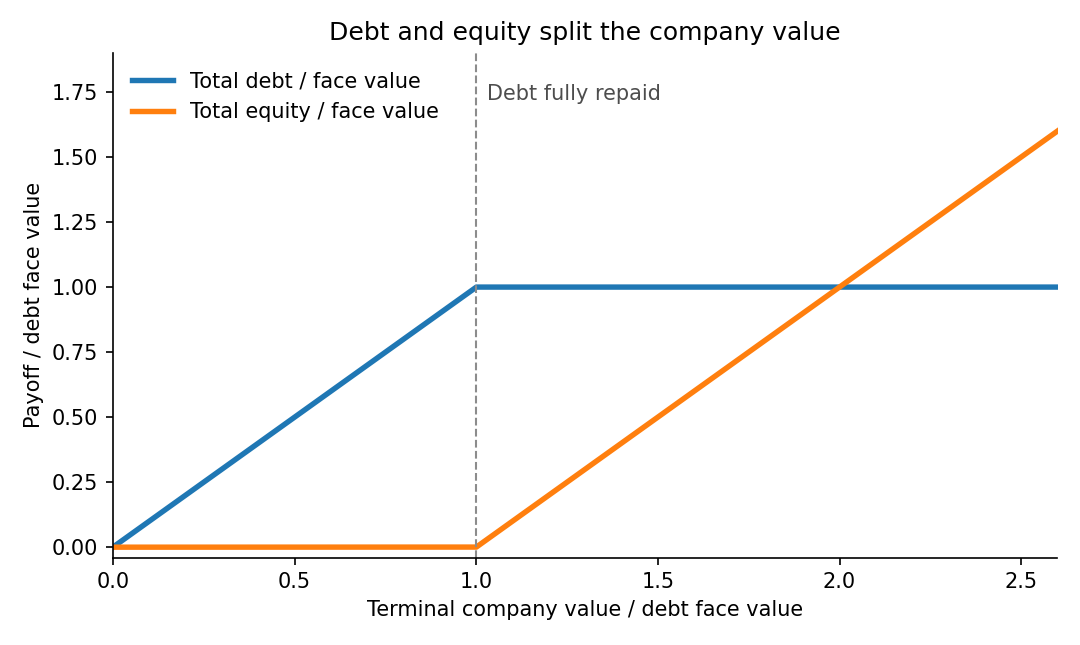

LetThe Black-Scholes formula gives total equity value . Because the total company value is a traded asset, replication gives total debt value . Divide by the numbers of securities to obtainThese are prices per security; the payoff diagram represents the two aggregate claims.
As insurance against credit default, the payment is the positive shortfall of recovery below face value:Thus the credit default swap in this question is one th of a European put option on the firm value. Its price isEquivalently, adding this insurance to one corporate bond produces a sure unit payment, so its price is minus the bond price from part (b). This also fixes the positive orientation of the printed “difference”: insurance compensates face value minus recovery.
At maturity, one stock share is worth . For a nonnegative strike , the digital call option therefore pays one exactly onUnder the risk-neutral measure, is normal with mean and variance . The risk-neutral pricing consequently givesThe effective company-value strike is , because both the outstanding debt and the number of shares matter. At , the strict positive-share event remains .
Articles by others on the same topic
There are currently no matching articles.