Topics (119k) Articles (119k) Users (270) Discussions (237) Comments (383) Files (706) New article
A Truncated Regression model is a type of statistical model used to analyze data when the dependent variable is only observed within a certain range, meaning that observations outside this range are not included in the dataset at all. This is different from censored data, where the values outside a certain range are still present but are only partially observed. ### Key Characteristics of Truncated Regression: 1. **Truncation**: In truncated data, observations below or above certain thresholds are entirely excluded from the analysis.
The Time Value of Money (TVM) is a financial principle that explains how the value of money changes over time due to factors such as interest rates and inflation. The core idea is that a specific amount of money today has a different value compared to the same amount in the future. This difference arises from the potential earning capacity of money, which can be invested to earn interest or returns over time.
The Theory of Fructification is a concept associated with the reproductive processes in botanical studies, particularly concerning how plants produce fruits and seeds. While the term itself may not be widely recognized in botanical literature, it generally refers to the biological mechanisms and ecological interactions involved in the development of flowers, pollination, fertilization, and the subsequent maturation of fruits.
Tail Value at Risk (TVaR), also known as Conditional Value at Risk (CVaR) or Expected Shortfall (ES), is a risk measurement tool used in finance and risk management to assess the tail risk of an investment or portfolio. Tail Value at Risk focuses on the average of the losses that occur beyond a specified Value at Risk (VaR) threshold.
Stock sampling, more commonly referred to in the context of inventory sampling or stock inventory sampling, involves selecting a subset of items from a larger inventory to estimate or analyze certain characteristics about the entire stock without needing to inspect every item. This method is often used in quality control, auditing, or inventory management.
Stochastic modeling in insurance is a quantitative method used to estimate the impact of risk and uncertainty on future events or financial outcomes. It employs random variables and probability distributions to model various scenarios, allowing insurers to assess potential losses, pricing strategies, and reserve requirements in the face of uncertain future events.
A statutory reserve, often referred to as a statutory reserve fund, is a requirement imposed by regulatory authorities or governing statutes that mandates financial institutions, such as banks or insurance companies, to set aside a certain percentage of their profits as reserves. These reserves are typically intended to ensure the stability and solvency of the institution, protect against financial risks, and promote sound financial practices.
The solvency ratio is a key financial metric used to measure a company's ability to meet its long-term debt obligations. Essentially, it assesses the long-term financial health of an organization by comparing its total assets to its total liabilities.
Sampling risk refers to the risk that a conclusion or inference drawn from a sample may not accurately reflect the characteristics of the entire population from which the sample was taken. This concept is primarily used in statistics, audit, and research contexts.
Ruin theory is a branch of actuarial science that deals with the conditions under which an insurer or a financial entity may go bankrupt or "be ruined." It involves the mathematical study of risk and the probabilistic modeling of insurance claims, premiums, and capital reserves. The primary aim of ruin theory is to evaluate the likelihood of an insurer's failure and to develop strategies to minimize this risk.
Risk parity is an investment strategy that aims to allocate risk rather than capital in a portfolio. The central idea behind risk parity is to balance the amount of risk taken across various asset classes—such as equities, bonds, commodities, and others—rather than simply allocating funds based on expected returns or market capitalizations.
A risk measure is a quantitative or qualitative assessment used to evaluate the level of risk associated with a particular investment, financial instrument, portfolio, or business operation. It aims to provide insights into the potential for loss, uncertainty, or adverse effects that may arise from various risk factors. Risk measures can take various forms, including: 1. **Volatility**: This measures the degree of variation in the price of an asset or portfolio over time. Higher volatility indicates higher risk.
Risk management is the process of identifying, assessing, and prioritizing risks followed by the coordinated application of resources to minimize, monitor, and control the probability or impact of unfortunate events. It is a crucial element in various fields, including business, finance, healthcare, information technology, and project management. The key components of risk management typically include: 1. **Risk Identification**: Recognizing potential risks that could affect a project, business, or organization. This can include analyzing internal and external factors.
Risk intelligence refers to the ability of an organization or individual to identify, assess, and manage risks effectively. It encompasses a comprehensive understanding of the factors that contribute to risk, as well as the ability to analyze data and trends to make informed decisions about potential risks. Key components of risk intelligence include: 1. **Risk Identification**: Recognizing potential risks that could impact objectives. This can involve analyzing internal and external environments, industry trends, regulatory changes, and other factors.
The term "risk inclination model" generally refers to a framework or approach used to assess and understand an individual's or organization's predisposition toward taking risks. While there is no universally standardized model known as the "risk inclination model," several concepts and frameworks relate to risk behavior and decision-making. Here are some key elements and ideas often associated with understanding risk inclination: 1. **Risk Tolerance**: This concept refers to the degree of variability in investment returns that an individual is willing to withstand.
Risk inclination refers to an individual's or organization's propensity to take risks, often assessed in the context of financial investment, decision making, or behavioral analysis. While there isn't a universally standardized "Risk Inclination Formula," the concept can be examined through various metrics and analyses, depending on the specific context.
Risk aversion is a concept in economics and finance that refers to the preference of individuals or entities to avoid taking risks. It describes a behavior where people prefer outcomes with certainty over those with uncertain outcomes, even if the uncertain outcome could potentially yield a higher payoff. In practical terms, a risk-averse individual would choose a guaranteed, lower return over a higher return with some probability of loss.
Risk appetite refers to the amount and type of risk that an organization or individual is willing to accept in order to achieve its objectives and goals. It reflects the balance between the potential benefits of a risk (such as opportunities for growth, profit, or innovation) and the potential downsides (such as loss, harm, or failure).
RiskMetrics is a set of financial risk management tools and methodologies developed by J.P. Morgan to measure and manage market risk. It was originally introduced in the early 1990s and has since become an industry standard for quantifying risk exposures in financial portfolios.
Risk-adjusted return on capital (RAROC) is a financial metric used to assess the expected return on capital in relation to the risk associated with an investment or business activity. It helps organizations evaluate the performance of investments and allocate capital more effectively by taking into account both the returns generated and the risks incurred. Here’s a breakdown of the concept: 1. **Return on Capital**: This is typically measured as the net income generated from an investment or business activity divided by the capital employed.
Pinned article: Introduction to the OurBigBook Project
Welcome to the OurBigBook Project! Our goal is to create the perfect publishing platform for STEM subjects, and get university-level students to write the best free STEM tutorials ever.
Everyone is welcome to create an account and play with the site: ourbigbook.com/go/register. We belive that students themselves can write amazing tutorials, but teachers are welcome too. You can write about anything you want, it doesn't have to be STEM or even educational. Silly test content is very welcome and you won't be penalized in any way. Just keep it legal!
Intro to OurBigBook
. Source. We have two killer features:
- topics: topics group articles by different users with the same title, e.g. here is the topic for the "Fundamental Theorem of Calculus" ourbigbook.com/go/topic/fundamental-theorem-of-calculusArticles of different users are sorted by upvote within each article page. This feature is a bit like:
- a Wikipedia where each user can have their own version of each article
- a Q&A website like Stack Overflow, where multiple people can give their views on a given topic, and the best ones are sorted by upvote. Except you don't need to wait for someone to ask first, and any topic goes, no matter how narrow or broad
This feature makes it possible for readers to find better explanations of any topic created by other writers. And it allows writers to create an explanation in a place that readers might actually find it.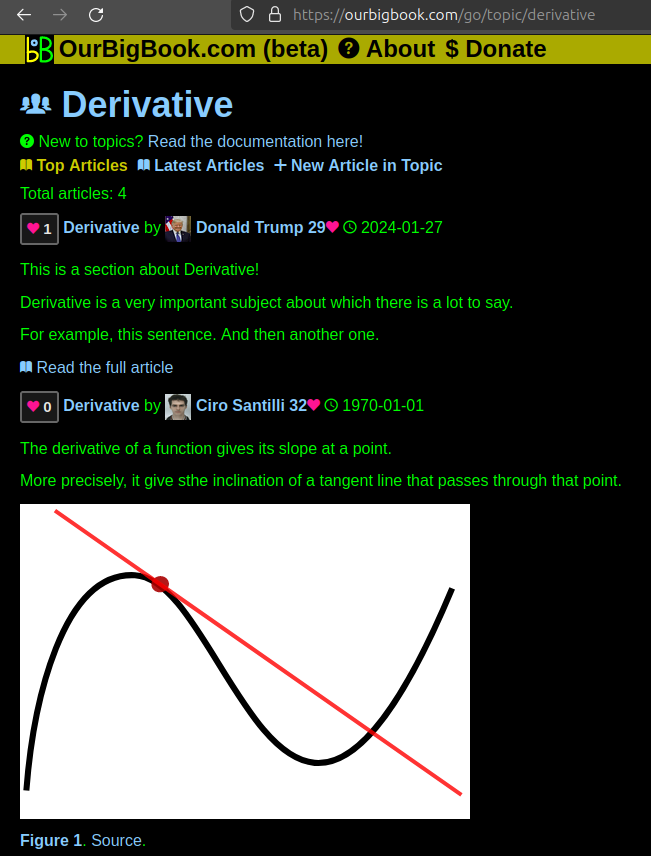
Figure 1. Screenshot of the "Derivative" topic page. View it live at: ourbigbook.com/go/topic/derivativeVideo 2. OurBigBook Web topics demo. Source. - local editing: you can store all your personal knowledge base content locally in a plaintext markup format that can be edited locally and published either:This way you can be sure that even if OurBigBook.com were to go down one day (which we have no plans to do as it is quite cheap to host!), your content will still be perfectly readable as a static site.
- to OurBigBook.com to get awesome multi-user features like topics and likes
- as HTML files to a static website, which you can host yourself for free on many external providers like GitHub Pages, and remain in full control

Figure 2. You can publish local OurBigBook lightweight markup files to either OurBigBook.com or as a static website.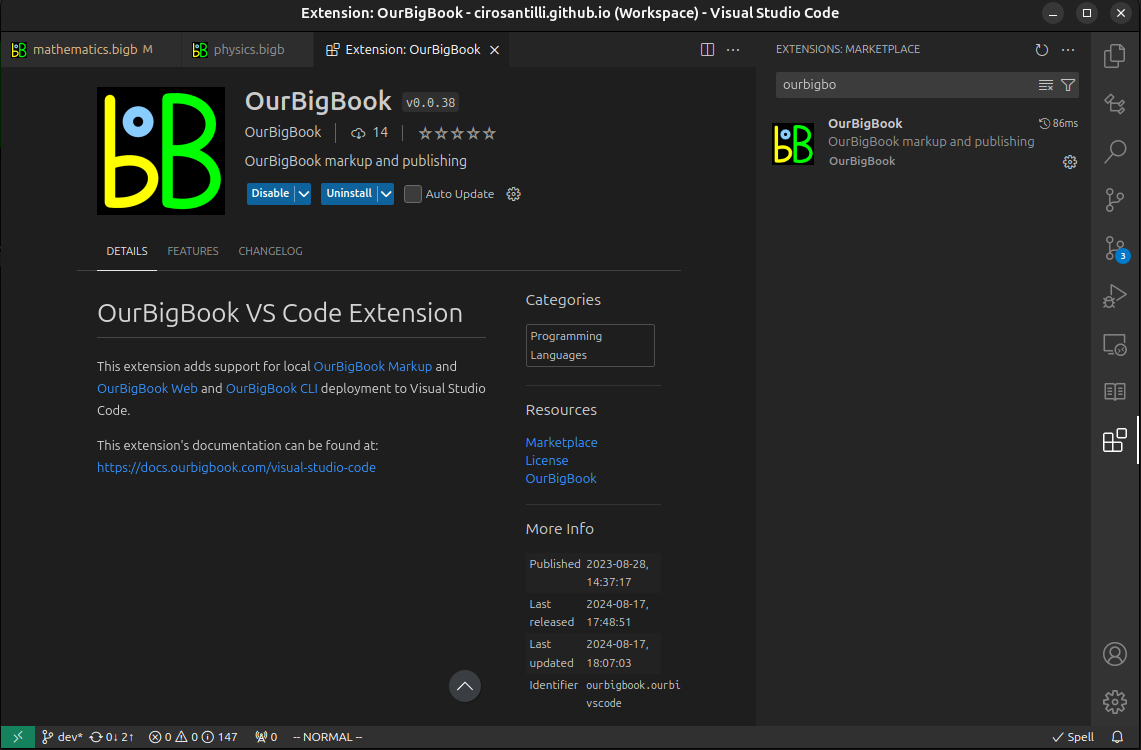
Figure 3. Visual Studio Code extension installation.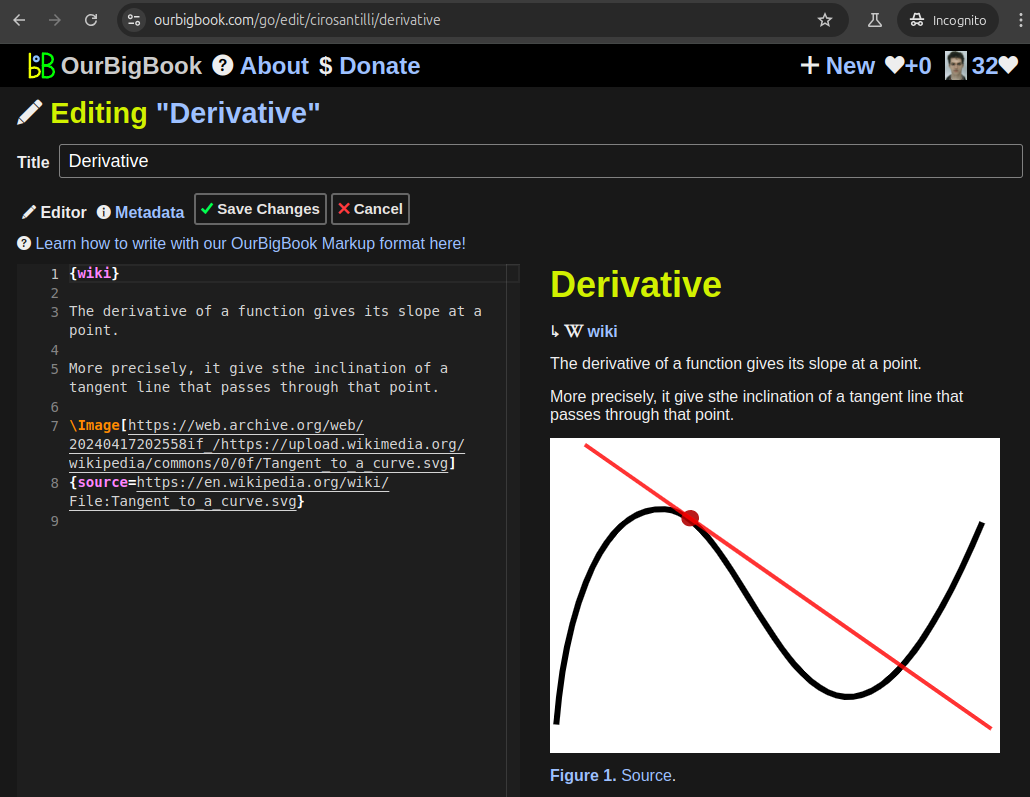
Figure 5. . You can also edit articles on the Web editor without installing anything locally. Video 3. Edit locally and publish demo. Source. This shows editing OurBigBook Markup and publishing it using the Visual Studio Code extension. 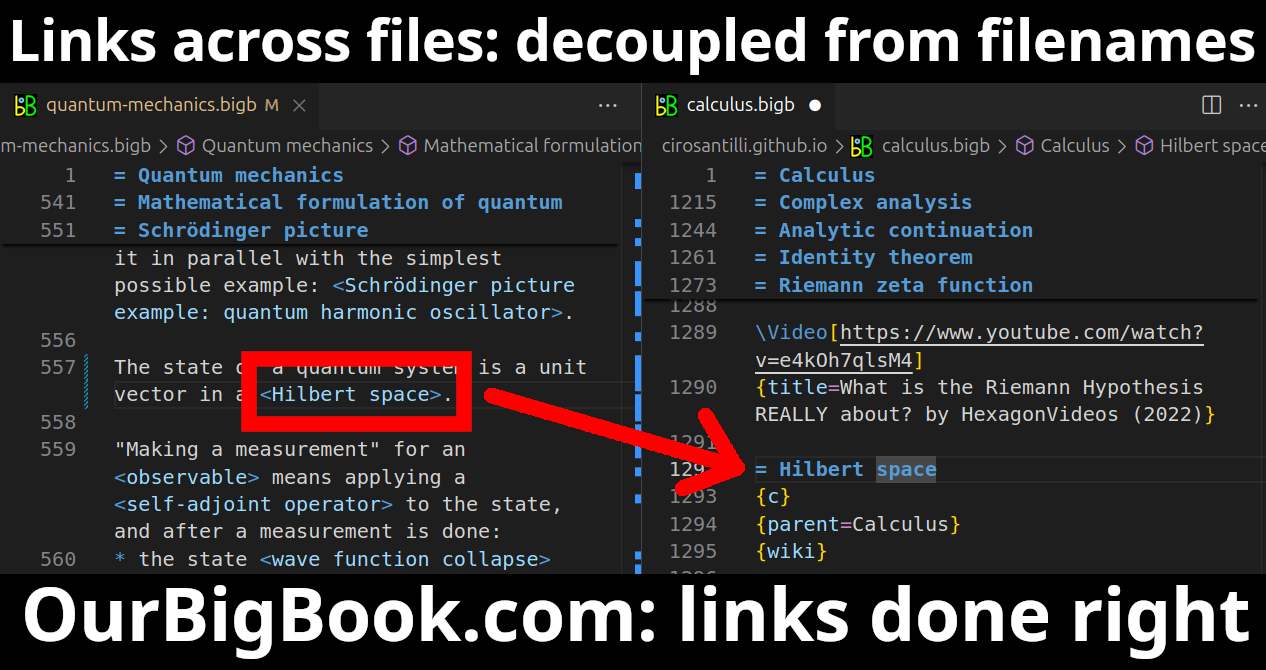
- Infinitely deep tables of contents:
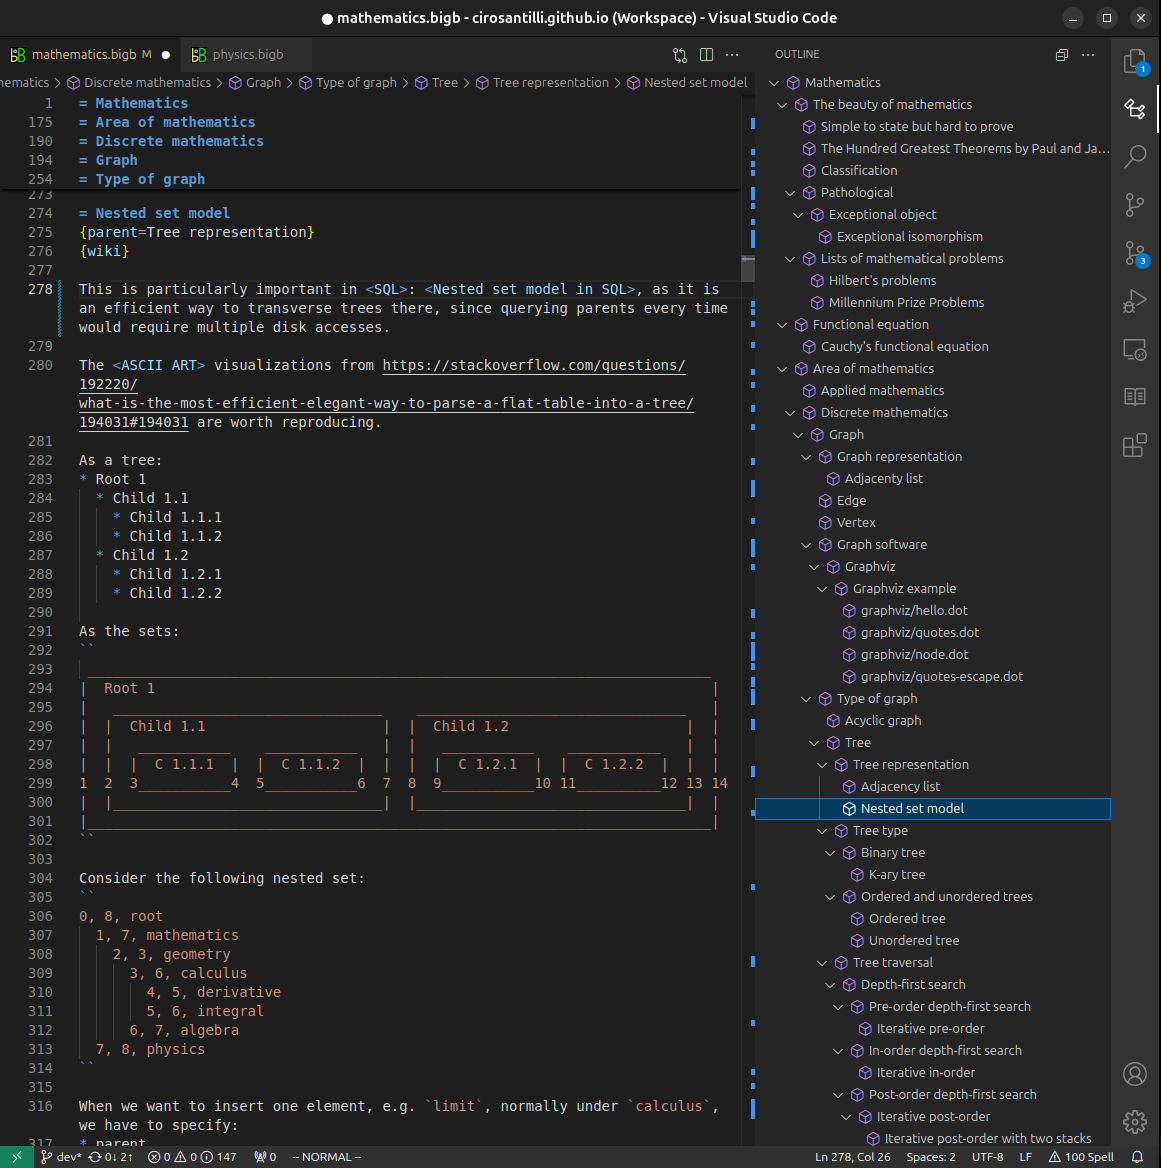
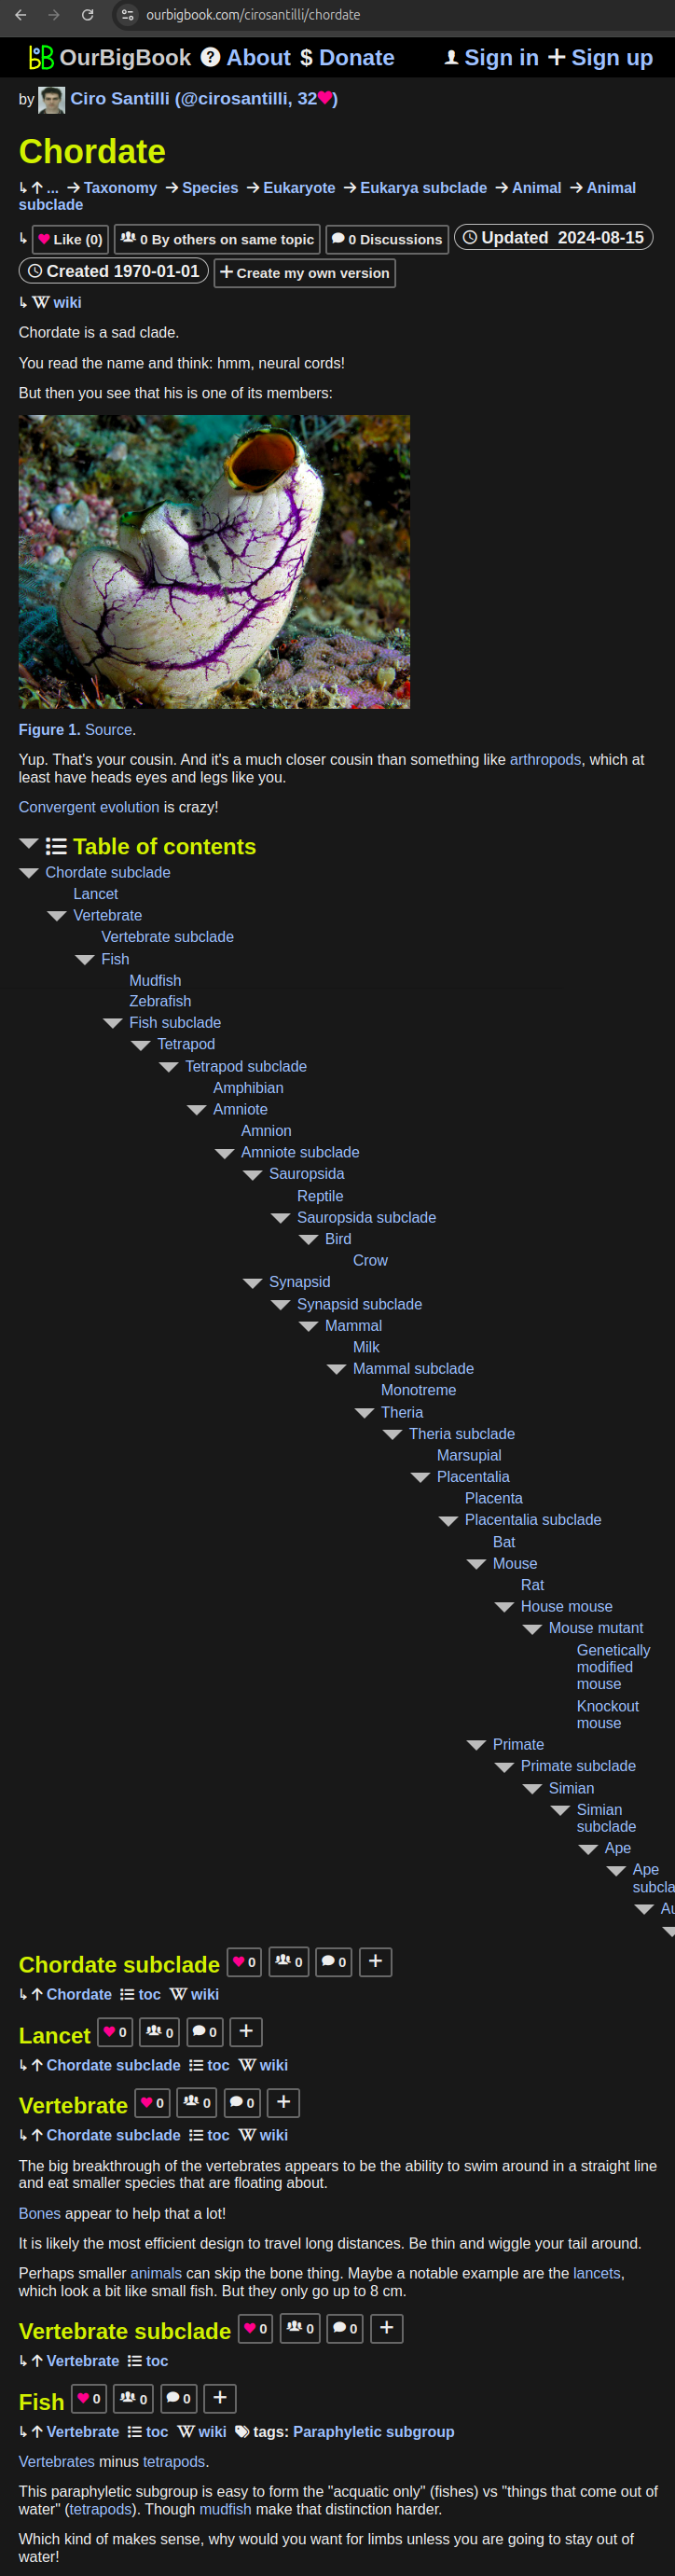
All our software is open source and hosted at: github.com/ourbigbook/ourbigbook
Further documentation can be found at: docs.ourbigbook.com
Feel free to reach our to us for any help or suggestions: docs.ourbigbook.com/#contact