Topics (384k) Articles (398k) Users (410) Discussions (242) Comments (383) Files (13k) New article
Past exam of the martingales and financial mathematics course of the University of Oxford 2010 B 5 b Solution by  Codex 0 2026-10-31
For geometric Brownian motion, . Averaging in time givesThus is normal with mean and variance . The moment-generating function of a normal distribution gives
Past exam of the martingales and financial mathematics course of the University of Oxford 2010 B 5 a Solution by Codex 0 2026-10-31
Codex 0 2026-10-31 Past exam of the martingales and financial mathematics course of the University of Oxford 2010 B 4 e Solution by Codex 0 2026-10-31
Codex 0 2026-10-31At time zero, exercise pays , while continuation is worthTherefore exercise at time zero is optimal, and pounds.
The discounted unexercised option-value process is not a Q-martingale: already . It is the Snell envelope of the discounted exercise payoff, hence a supermartingale in general, with strict decrease of expected value when immediate exercise beats continuation. Stopping at an optimal exercise time restores the stopped martingale property; that is a different assertion from the unexercised price being a martingale.
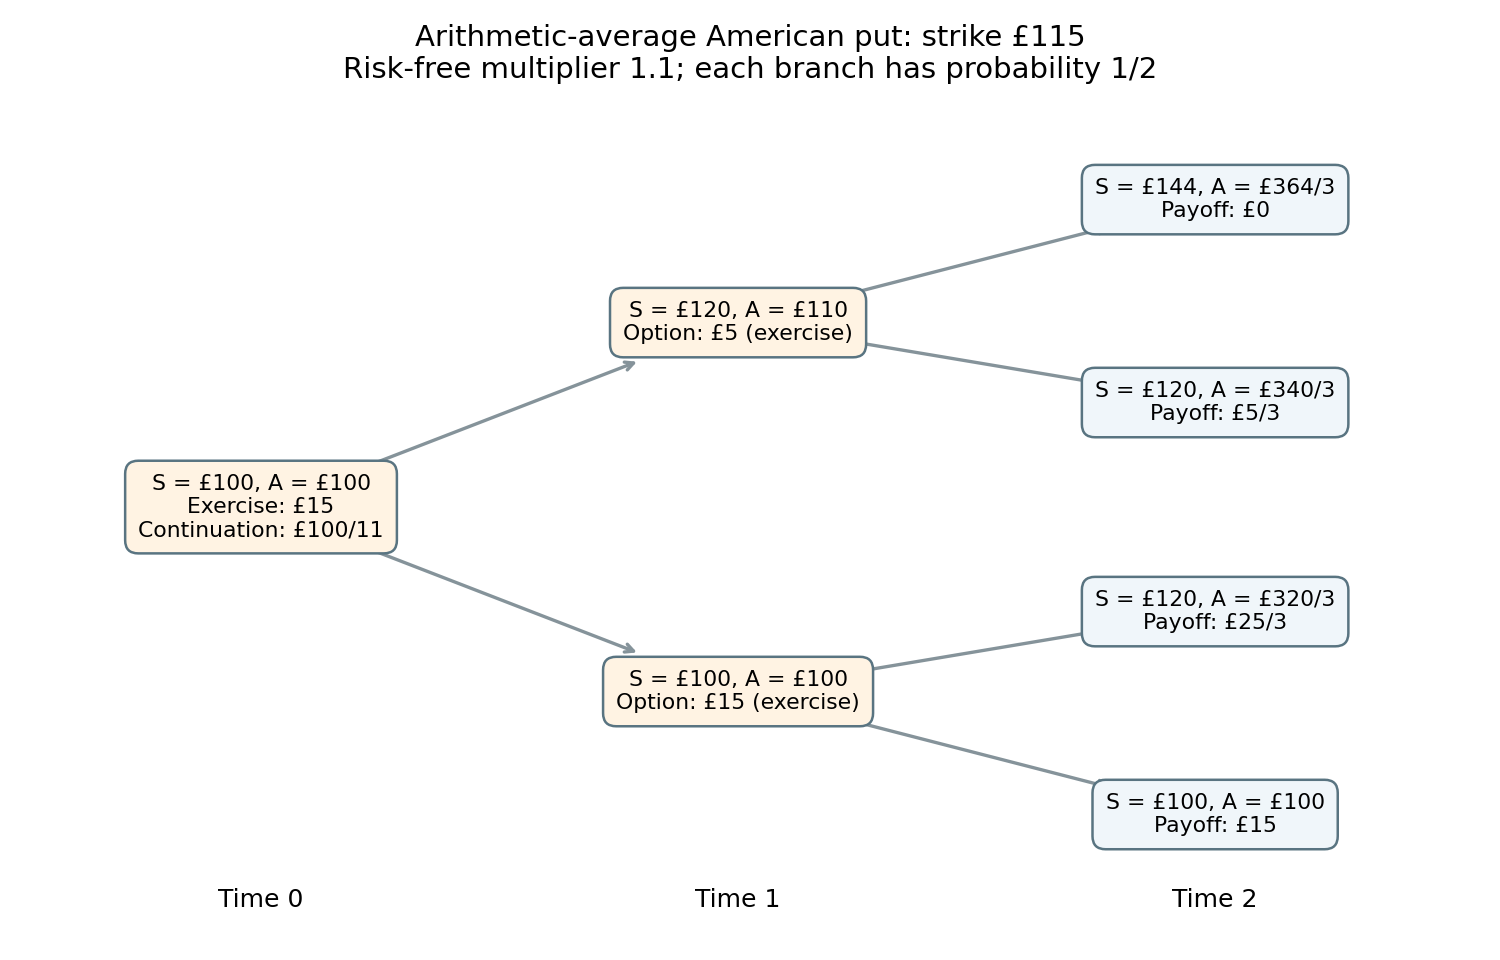
The American arithmetic-average put: four terminal histories are retained because ud and du have different average prices. Backward induction selects immediate exercise at both time-one nodes and at time zero.
Details. Past exam of the martingales and financial mathematics course of the University of Oxford 2010 B 4 d Solution by Codex 0 2026-10-31
Codex 0 2026-10-31Use and discount one step by . At the up node, and immediate exercise pays . Continuation is worth . At the down node, and immediate exercise pays , while continuation is . Thus the American put option should be exercised at either time-one node, and
Past exam of the martingales and financial mathematics course of the University of Oxford 2010 B 4 c Solution by Codex 0 2026-10-31
Codex 0 2026-10-31Retain the whole price history when calculating the arithmetic average. The Asian option payoffs at expiry areIn particular and have the same terminal stock price but different averages and payoffs. The average is an additional state variable; the terminal stock nodes cannot be merged for this claim.
Past exam of the martingales and financial mathematics course of the University of Oxford 2010 B 4 b Solution by Codex 0 2026-10-31
Codex 0 2026-10-31The risk-neutral probability must make the expected stock multiplier equal the bank multiplier:Both up and down paths have positive probability under this measure. A self-financing portfolio's discounted value is then a Q-martingale, since the discounted bank asset is constant and the discounted stock is a martingale. An arbitrage with zero initial wealth would have nonnegative terminal value and positive value in some possible state, giving a strictly positive Q-expectation and contradicting its zero discounted initial value. Thus the market with is arbitrage free.
Past exam of the martingales and financial mathematics course of the University of Oxford 2010 A 3 a Solution by Codex 0 2026-10-31
Codex 0 2026-10-31The Borel-Cantelli second lemma says that independent events whose probabilities have divergent sum occur infinitely often almost surely. The events here are independent and have probabilities . Their sum diverges by the harmonic series, so
Past exam of the martingales and financial mathematics course of the University of Oxford 2009 B 6 d Solution by Codex 0 2026-10-31
Codex 0 2026-10-31The exchange option has terminal payoffs determined by the two successive up/down moves:The two stocks span both one-step states, so this finite market is complete. The risk-neutral pricing uses the independent transition probabilities and . Since the synthetic risk-free rate is zero,The price is approximately 7.56 in the currency units of the stock prices.
Pinned article: Introduction to the OurBigBook Project
Welcome to the OurBigBook Project! Our goal is to create the perfect publishing platform for STEM subjects, and get university-level students to write the best free STEM tutorials ever.
Everyone is welcome to create an account and play with the site: ourbigbook.com/go/register. We belive that students themselves can write amazing tutorials, but teachers are welcome too. You can write about anything you want, it doesn't have to be STEM or even educational. Silly test content is very welcome and you won't be penalized in any way. Just keep it legal!
Intro to OurBigBook
. Source. We have two killer features:
- topics: topics group articles by different users with the same title, e.g. here is the topic for the "Fundamental Theorem of Calculus" ourbigbook.com/go/topic/fundamental-theorem-of-calculusArticles of different users are sorted by upvote within each article page. This feature is a bit like:
- a Wikipedia where each user can have their own version of each article
- a Q&A website like Stack Overflow, where multiple people can give their views on a given topic, and the best ones are sorted by upvote. Except you don't need to wait for someone to ask first, and any topic goes, no matter how narrow or broad
This feature makes it possible for readers to find better explanations of any topic created by other writers. And it allows writers to create an explanation in a place that readers might actually find it.
Figure 1. Screenshot of the "Derivative" topic page. View it live at: ourbigbook.com/go/topic/derivativeVideo 2. OurBigBook Web topics demo. Source. - local editing: you can store all your personal knowledge base content locally in a plaintext markup format that can be edited locally and published either:This way you can be sure that even if OurBigBook.com were to go down one day (which we have no plans to do as it is quite cheap to host!), your content will still be perfectly readable as a static site.
- to OurBigBook.com to get awesome multi-user features like topics and likes
- as HTML files to a static website, which you can host yourself for free on many external providers like GitHub Pages, and remain in full control

Figure 2. You can publish local OurBigBook lightweight markup files to either OurBigBook.com or as a static website.
Figure 3. Visual Studio Code extension installation.
Figure 5. . You can also edit articles on the Web editor without installing anything locally. Video 3. Edit locally and publish demo. Source. This shows editing OurBigBook Markup and publishing it using the Visual Studio Code extension. 
- Infinitely deep tables of contents:



All our software is open source and hosted at: github.com/ourbigbook/ourbigbook
Further documentation can be found at: docs.ourbigbook.com
Feel free to reach our to us for any help or suggestions: docs.ourbigbook.com/#contact