
The standard Gumbel distribution for maxima has distribution function for every real . Its probability density function is the derivative of its distribution function:This article uses the maxima convention throughout. Reflecting a standard Gumbel distribution random variable to gives the minima convention, with distribution function . The two conventions have opposite directions of asymmetry, so their formulas must not be interchanged. [ref]
https://www.itl.nist.gov/div898/handbook/eda/section3/eda366g.htm. NIST: extreme value type I distributions for maxima and minima
.For a location and positive scale , let . This location-scale family has cumulative distribution function and probability density functionSolving gives the standard quantile function , , and hence the standard medianThe median of is therefore . Location is not the median: at the cumulative distribution function is .
To derive the Gumbel distribution as an extreme-value limit, take the maximum of independent exponential random variables with rate and setThe exact distribution function isThe finite- lower boundary is required because . For each fixed real , eventually , and the natural logarithm of the first branch satisfiesExponentiating proves convergence in distribution to the standard Gumbel distribution. It is the familiar limit with : a simple calculation reveals a whole limiting shape. The name honors Emil Gumbel; Siegrist gives this exponential-maxima derivation and the standard Gumbel distribution formulas. [ref]
https://www.randomservices.org/random/special/ExtremeValue.html. Siegrist, Random Services: the Gumbel distribution and its exponential-maxima limit
.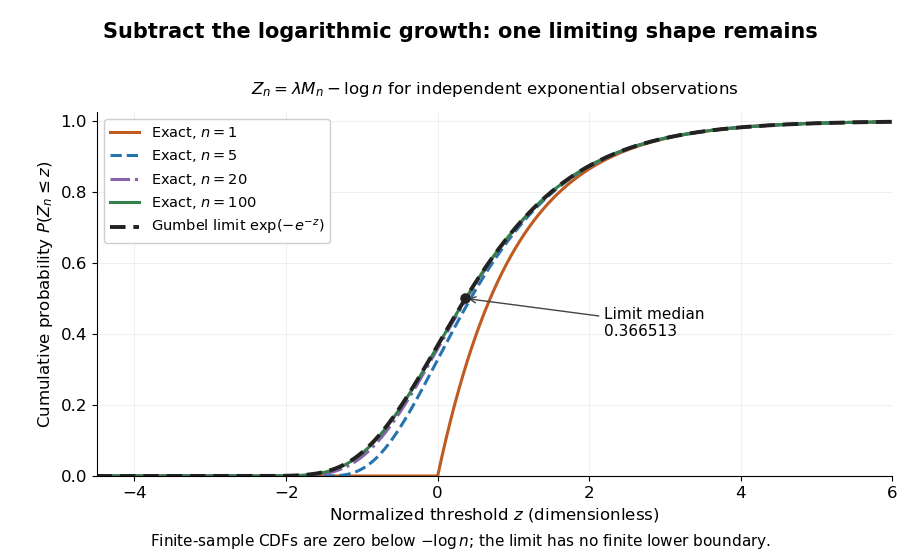
Centered exponential sample maxima for n equal to 1, 5, 20 and 100 approach the standard Gumbel cumulative distribution function
. Details. 
For the toy delay model , , the limiting Gumbel distribution approximation to has and . Its predicted median iscompared with the exact median . The approximation is about seconds lower in this example. It is not an exact finite-sample probability distribution: the approximating Gumbel distribution assigns positive probability to negative delays, while the exact sample maximum cannot be negative.
The maximum domain of attraction of the Gumbel distribution is characterized by an exponential tail ratio on the scale of a Gumbel auxiliary function. This allows many original probability distributions to share the limiting shape, but it does not make the centering appropriate to all of them.
New to topics? Read the docs here!