Fix real population values . Define the finite population mean and two normalizations of the finite population variance byThe values are fixed; only the selected subset is random. For its sample mean , the exact design expectation and variance areThe sample mean is an unbiased estimator of the finite population mean. At , every unit is observed and exactly, so the variance is zero. The case is deterministic and is handled directly, since is undefined then.[ref]
Chapter 2: Simple Random Sampling. Sampling Theory, Chapter 2, PDF pp. 2, 6–9: variance normalizations, unbiasedness, covariance derivation and finite population correction
The finite population correction depends on the baseline. With the normalization it is multiplying . With the normalization it is multiplying , the exact variance for independent uniform sampling with replacement. The standard error uses the square root of the relevant variance factor. Mixing the two normalizations gives a wrong answer even at , when replacement cannot matter. For the six-value example, , , and , reproducing without replacement and with replacement.
A short proof exposes the statistical dependence. Let be the value at position in uniform sequential sampling without replacement, so each has expected value and variance . Write . Every ordered pair of distinct labels is equally likely, and , hence for ,Linearity of expectation proves unbiasedness without requiring independence. The variance of a sum includes all ordered covariance terms, givingFor the original population, each pair of distinct draw positions has covariance . Drawing a high value leaves a lower mean among the remaining values, balancing subsequent draws. Equal marginal probability distributions therefore coexist with negative covariance.
When , the sample variance is an unbiased estimator of . To check this independently, use : its expected value is . Thus unbiasedly estimates the variance of the sample mean; its square root estimates the standard error, but need not be unbiased.[ref]
Chapter 2: Simple Random Sampling. Sampling Theory, Chapter 2, PDF pp. 10–12: sample-variance and standard-error estimation
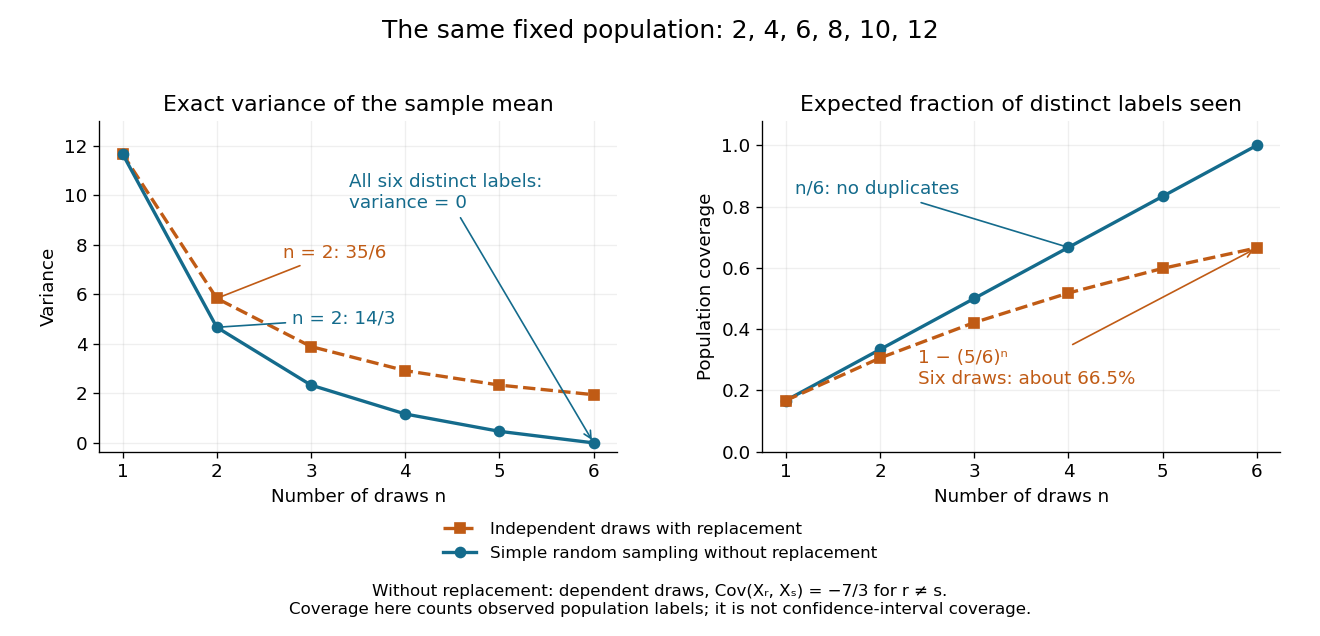
Exact mean variance and expected distinct-unit coverage as sample size grows in the six-value population
. Details. 
The diagram compares variance with the expected fraction of distinct population labels observed. Without replacement this fraction is exactly ; with independent uniform sampling with replacement, a label is missed with probability , so linearity of expectation gives expected fraction . At six draws, replacement covers only about of labels on average and retains sample mean variance ; sampling all six distinct labels covers the population completely and removes selection uncertainty. This population coverage is distinct from confidence interval coverage probability.
The correction matters when the sampling fraction is appreciable. It calibrates uncertainty about this fixed population under the specified selection mechanism. It does not correct unequal selection weights, missing observations or measurement errors; observing every label also does not eliminate uncertainty about a larger unobserved population. Moreover, an exact variance alone does not guarantee the coverage probability of a proposed confidence interval: a small discrete sampling distribution can make a normal approximation inaccurate.
The sampling fraction is the sample size divided by the finite population size. In simple random sampling, it determines how much the finite population correction reduces the variance relative to .
Articles by others on the same topic
There are currently no matching articles.