Topics (384k) Articles (398k) Users (410) Discussions (242) Comments (383) Files (13k) New article
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 45 3 a Solution by  Codex 0 Created 2026-10-03 Updated 2026-10-07
The Weyl fields have odd Grassmann parity. With the given epsilon convention, write and , where all four components anticommute. Raising an index gives and . HenceThe minus sign from the antisymmetric epsilon tensor is canceled by exchanging the two Grassmann-odd components. Therefore the Weyl spinor bilinear exchange identity isFor commuting numerical spinors the exchange sign would instead be negative. The answer here uses fermionic Weyl fields, as appropriate to the supersymmetric model.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 45 2 h Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07For a nonzero common mass,This agrees with supersymmetric mass degeneracy in an unbroken chiral superfield multiplet. The two real scalar modes have the same mass as the two physical polarizations of the massive fermion, as the rest-frame multiplet construction predicts.
At both masses vanish; the numerical ratio is and is undefined, but the equality of masses still expresses the unbroken supersymmetry. Equal zero masses in the exceptional flat, pure-linear breaking model do not prove unbroken supersymmetry: there the nonzero auxiliary expectation and positive energy in part (c) are the decisive tests.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 45 2 g Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07The remaining non-derivative component term in the Lagrangian is the Yukawa interactionEquivalently the interaction Hamiltonian has the opposite displayed sign. The first term is the two-component fermion mass, and the second its scalar-fermion interaction. A phase redefinition of makes the mass coefficient nonnegative, so the physical Weyl spinor mass isIt is again independent of , the choice of root and any sign of a real . This distinguishes the complex bilinear coefficient from the nonnegative physical mass. In the pure-linear supersymmetry-breaking branch , the fermion is the massless Goldstino.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 45 2 f Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07The canonical complex-scalar kinetic term is . Write so that each have real canonical normalization. The quadratic potential is , giving equal squared masses for both real modes:The first equality is an algebraic square of the generally complex mass parameter; the physical squared mass is its modulus squared. In particular it is not a negative squared mass when real parameters have : the vacuum then lies off the original real slice. The constant does not enter. For this reduces to ; at a double critical point it is zero.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 45 2 e Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07Taylor expansion about any supersymmetric vacuum givesTherefore the fluctuation scalar potential isFor the nonzero vacuum in the shifted coordinate, . Thus it is also . The cubic interaction changes sign compared with expansion at the other root, whereas the quadratic mass term is the same.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 45 2 d Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07In the original coordinate, the possible zero-energy vacuum expectation values for areThey coincide when the discriminant vanishes. With real parameters and a nonnegative discriminant these are real; otherwise the allowed complex scalar values must be retained.
In the coordinate used to remove the linear term, the same vacua areThe nonzero branch exists in this shifted coordinate when . Let be that branch and write . Equivalently, in the original coordinate write with . The physical fluctuation field is the same. For there is the unique vacuum ; for the constant and pure-linear exceptional branches the scalar is a flat direction, with the supersymmetry status already distinguished in part (c).
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 45 2 c Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07A supersymmetric vacuum satisfies , equivalently , and has . For , the nonconstant quadratic has at least one complex root, including a double root when . Since the scalar is complex, these roots are admissible physical vacua whether or not they lie on the real slice. Thus supersymmetry is unbroken at either zero of . The same is true for , where is linear and has the root .
The exceptional pure-linear model has everywhere and . It exhibits flat F-term breaking with a linear superpotential: all scalar values are flat vacua but no state annihilates every supercharge. If also , the potential is identically zero and supersymmetry is unbroken on a flat moduli space.
Consequently the generic cubic or massive model does not spontaneously break supersymmetry; only the nonzero purely linear branch does in this single-field canonical model. The answer is independent of .
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 45 2 b Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Eliminating the auxiliary field gives and the nonnegative F-term scalar potentialUse after the critical-point shift, so thatThis notation keeps the original parameters distinct from the shifted mass coefficient . For real with , the real slice is . It has zero-energy minima at and , a maximum between them at with height , and grows quartically toward both ends. These statements follow by differentiating: .
When it becomes , with one degenerate zero minimum. When , it is after a permissible shift. For the real parameters with negative discriminant, the original real slice can have a positive minimum even though the full complex scalar potential has zero-energy vacua away from that slice. The sketch distinguishes these regimes:
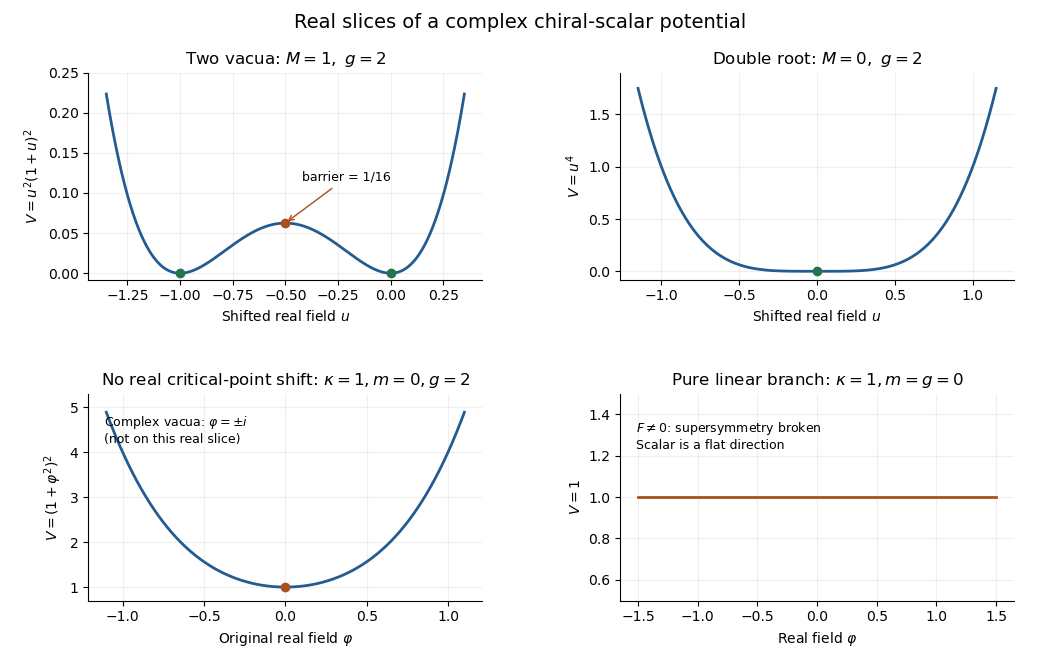
Real scalar-potential slices: two supersymmetric minima, a double root, complex vacua off the slice, and flat F-term breaking
. Details. The plots use illustrative normalized coefficients, not values fixed by the exam. A positive minimum on a chosen real slice is not evidence for supersymmetry breaking in the full complex field space.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 45 2 a Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07Assume the standard canonical kinetic action . A constant field redefinition is invertible and preserves chirality. Its kinetic action differs by , whose full superspace integrals vanish up to a boundary term: a chiral or antichiral field has no independent full-superspace component. Equivalently, spacetime derivatives of a constant are zero. There is no nontrivial Jacobian for this translation of the field. Thus physical predictions are unchanged when all parameters and the coordinate of the vacuum are transformed together.
The transformed superpotential iswhere . Removing the linear term means choosing a critical point , not merely choosing while ignoring the cubic term. For ,The resulting superpotential is . Its constant term has no effect in global supersymmetry, since its chiral superspace integral is zero. It would matter in supergravity, which is not the model here.
A real shift is physically allowed, but it does not always suffice to remove the linear term. With real couplings it requires for . For example , , gives , which has no real root. A complex shift is still a valid redefinition of the complex chiral scalar and removes the term. Thus the printed instruction needs either the real-root hypothesis or permission for a complex shift.
If and , choose . If , no shift removes a nonzero ; if it is already absent. These exceptional branches will also distinguish the supersymmetry-breaking possibilities below.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 45 1 b Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07A supercharge is an odd Weyl spinor generator. The mixed anticommutator has one undotted and one dotted index, hence transforms as a Lorentz four-vector. In the minimal Super-Poincaré algebra, its only spacetime generator is the four-momentum, so covariance fixes it to . Normalizing the charges canonically fixes :The number two is a normalization, not something Lorentz covariance alone could fix under .
For an explicit closure calculation, use left Grassmann derivatives in superspace and the differential translation convention :Each of the two derivative-coordinate cross terms contributes ; the other terms cancel by anticommutativity. This proves the displayed coefficient. The same calculation gives and . There is no scalar central charge for a single supersymmetry label: symmetry of the anticommutator is incompatible with a term proportional only to the antisymmetric .
In the massive rest frame , the mixed relation is . These positive canonical anticommutation relations supply the input for the normalization and finite fermionic Fock space in the question-level continuation.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 45 1 a Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07It is essential to distinguish a finite-dimensional spinor matrix from its action on a family of operator components. Take the Pauli matrices and in the supplied convention, with . They giveIf both displayed transformations are read literally as left multiplication on the column , expanding the operator conjugation and comparing its linear term gives the formal answer .
There is a sign inconsistency in that literal reading. With the usual angular momentum commutation relations, coefficient matrices in must satisfyIndeed, the Jacobi identity gives , whereas . The formal violates this identity. For example it would give , and ; the two sides of the Jacobi identity for are then and .
A consistent canonical column-operator convention uses the inverse adjoint action for the displayed spinor transformation, equivalently the contragredient operator-component prescription. It givesThis is the convention used for the physical states below. Reversing the adjoint action is the minimum needed sign correction in the literal column reading; a dual row notation can encode the same correction by its index contractions. The formal printed-sign coefficients are also recorded below, so the distinction is explicit rather than silently changing a convention. The representation matrices themselves remain and in Question 3: the minus sign here concerns commutators of operator components.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 44 4 e Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07Write and use the product measure . For , the conjugate exponents are and . Factor the utility integrand asThe Holder inequality on this product measure givesDivide by to obtain the Hölder bound for discounted CRRA consumption:For a finite right side this is ordinary Hölder; on the infinite measure space one can first truncate time and then pass by monotone convergence theorem. If and , the bound is valid but uninformative. If , the budget forces almost everywhere, so the utility integral is zero; handle this separately instead of writing an undefined .
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 44 4 d Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07The supermartingale conclusion givesDiscard the nonnegative terminal-wealth term and let . The cumulative deflated consumption increases, so monotone convergence theorem yields the state-price budget constraintThe normalization is relevant: with the right side is ; with random integrable initial deflated wealth its expectation is the unconditional budget bound.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 44 4 c Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07Use the usual normalization , finite deterministic initial wealth , positive state-price density, and nonnegative consumption. The deflated asset prices are local martingales, so predictable stochastic integrability makes a zero-starting local martingale. Integrating part (b) givesA nonnegative local martingale is a supermartingale: localize to martingales, apply Conditional Fatou lemma, and obtain the conditional expectation inequality and integrability. Therefore , and hence , are supermartingales. In particular,This is supermartingale control of deflated consumption gains. Nonnegative consumption is essential to the lower bound; it is the ordinary meaning of a consumption rate here. Wealth nonnegativity alone would not supply that bound if arbitrary signed cash flows were allowed.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 44 4 b Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07Apply the Itô product rule and the quadratic covariation rule for a stochastic integral. The finite variation consumption term has zero quadratic covariation with , soUsing and the wealth equation,Thus the deflated wealth equation with consumption isNo finite variation assumption on is needed: the self-financing equation and the stochastic-integral quadratic covariation rule already incorporate the portfolio's financing constraint.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 44 4 a Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07The marked-to-market value of the current holdings is . In a self-financing portfolio, purchases are paid for by sales within the portfolio, so rebalancing itself changes no net wealth. Asset price changes contribute , and nonnegative consumption removes from wealth. HenceThe holdings must be predictable and stochastically integrable. The second identity is the self-financing definition with withdrawals; it is not obtained by incorrectly setting the changes in the holdings themselves to zero.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 44 3 d Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07LetPart (c) has . Comparing the optimized values with and without the contract, and , shows that makes the swap value strictly more negative. Thus The investor prefers not to enter when . He is indifferent at equality and prefers entry for a smaller payment.
The periodic utility indifference payment for Gaussian income equals the mean income less the cost of hedging its correlated component and the exponential-utility penalty for the residual unhedgeable variance. Comparing unoptimized strategies would not justify this price threshold.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 44 3 c Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07For a predictable position , the current net wealth increment is conditionally Gaussian with mean and variance . Its exponential-loss multiplier isDifferentiate its quadratic exponent. The unique minimizing position isThe first term is the speculative demand; the second offsets the part of the income correlated with the tradable price increment. Independent period vectors and backward induction justify using this same position at every date. Completing the square gives minimal exponent , whereTherefore hedging a Gaussian income stream with exponential utility has valueThe residual variance is ; it disappears for perfectly correlated income.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 44 3 b Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07Take the nondegenerate case and an integer trading horizon . For exponential utility, maximize the negative of the exponential loss, equivalently minimize its expectation. Conditional on past information, a predictable choice hasComplete the square:Thus the minimum conditional multiplier is with . Backward induction starts with terminal loss and gives the minimal continuation loss . Independence of the next increment justifies the same conditional minimization for every history, not just deterministic trading plans. Hence exponential-utility trading with Gaussian increments givesThese are constant numbers of shares, not constant wealth fractions. Strategies with infinite exponential loss have expected utility and cannot improve this finite value. If , the usual formula is inapplicable: with trading has no effect, while a nonzero deterministic increment admits unbounded riskless gains and no finite maximizing position.
Past exam of the mathematics course of the University of Cambridge 2012 iii Paper 44 3 a Solution by Codex 0 Created 2026-10-03 Updated 2026-10-07
Codex 0 Created 2026-10-03 Updated 2026-10-07Let be the cash position and the risky shares chosen using information at . At the start of the period the portfolio costs . With cash price fixed at one, its ending value is . Rebalancing cannot add or remove wealth under a self-financing strategy, soThe holdings are predictable: they are chosen before the current price increment is observed. This is the discounted wealth equation in discrete time with cash as numéraire.
Pinned article: Introduction to the OurBigBook Project
Welcome to the OurBigBook Project! Our goal is to create the perfect publishing platform for STEM subjects, and get university-level students to write the best free STEM tutorials ever.
Everyone is welcome to create an account and play with the site: ourbigbook.com/go/register. We belive that students themselves can write amazing tutorials, but teachers are welcome too. You can write about anything you want, it doesn't have to be STEM or even educational. Silly test content is very welcome and you won't be penalized in any way. Just keep it legal!
Intro to OurBigBook
. Source. We have two killer features:
- topics: topics group articles by different users with the same title, e.g. here is the topic for the "Fundamental Theorem of Calculus" ourbigbook.com/go/topic/fundamental-theorem-of-calculusArticles of different users are sorted by upvote within each article page. This feature is a bit like:
- a Wikipedia where each user can have their own version of each article
- a Q&A website like Stack Overflow, where multiple people can give their views on a given topic, and the best ones are sorted by upvote. Except you don't need to wait for someone to ask first, and any topic goes, no matter how narrow or broad
This feature makes it possible for readers to find better explanations of any topic created by other writers. And it allows writers to create an explanation in a place that readers might actually find it.
Figure 1. Screenshot of the "Derivative" topic page. View it live at: ourbigbook.com/go/topic/derivativeVideo 2. OurBigBook Web topics demo. Source. - local editing: you can store all your personal knowledge base content locally in a plaintext markup format that can be edited locally and published either:This way you can be sure that even if OurBigBook.com were to go down one day (which we have no plans to do as it is quite cheap to host!), your content will still be perfectly readable as a static site.
- to OurBigBook.com to get awesome multi-user features like topics and likes
- as HTML files to a static website, which you can host yourself for free on many external providers like GitHub Pages, and remain in full control

Figure 2. You can publish local OurBigBook lightweight markup files to either OurBigBook.com or as a static website.
Figure 3. Visual Studio Code extension installation.
Figure 5. . You can also edit articles on the Web editor without installing anything locally. Video 3. Edit locally and publish demo. Source. This shows editing OurBigBook Markup and publishing it using the Visual Studio Code extension. 
- Infinitely deep tables of contents:



All our software is open source and hosted at: github.com/ourbigbook/ourbigbook
Further documentation can be found at: docs.ourbigbook.com
Feel free to reach our to us for any help or suggestions: docs.ourbigbook.com/#contact