Write and . The European power put formula isHere has a lognormal distribution. Since is decreasing and is a convex function, its discounted expected value is also decreasing and convex as a function of . For it is smooth and strictly positive: the normal distribution assigns positive probability to whatever the current positive spot price. Its endpoints areThe dominated convergence theorem justifies the second limit, because . For a quantitative sketch, the binomial theorem and truncated lognormal moment givewhere is the standard normal distribution function. This finite sum is useful for drawing the curve; its positive expectation form makes its qualitative shape clearer.
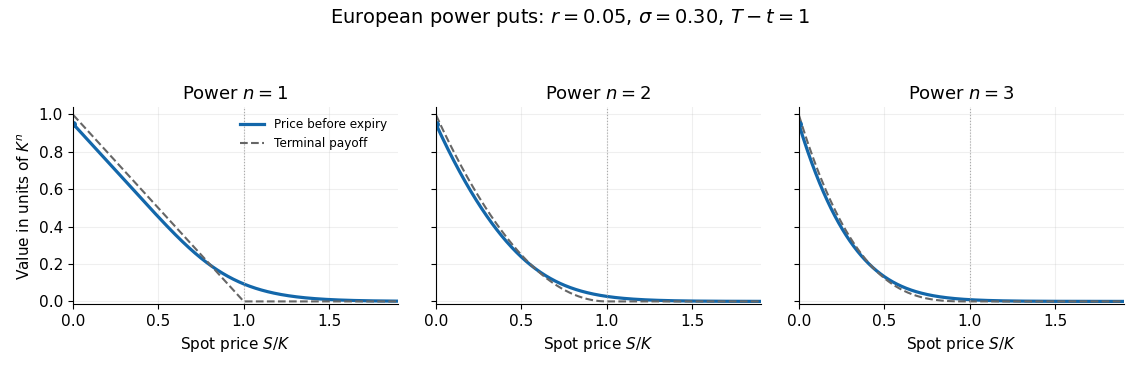

The solid curves use , , and ; the dashed curves show their terminal financial payoffs for comparison. Each price remains positive at and tends smoothly towards zero beyond it. At small , discounting gives a price below the undiscounted financial payoff; European exercise is permitted only at expiry.
Articles by others on the same topic
There are currently no matching articles.