Let be a real symmetric matrix with a positive-definite matrix. Its quadratic form satisfies the completing the square identityFor each fixed vector , the unique minimizing vector is , so the minimized value is . Also, is a positive-definite matrix exactly when is a positive-definite matrix, under the stated assumption on .[ref]
An original scalar example isHere , , , and the Schur complement is . Holding would give , but letting relax to reduces the quadratic form to . At the respective values are and . Eliminating a variable therefore changes the effective cost of the retained variable.
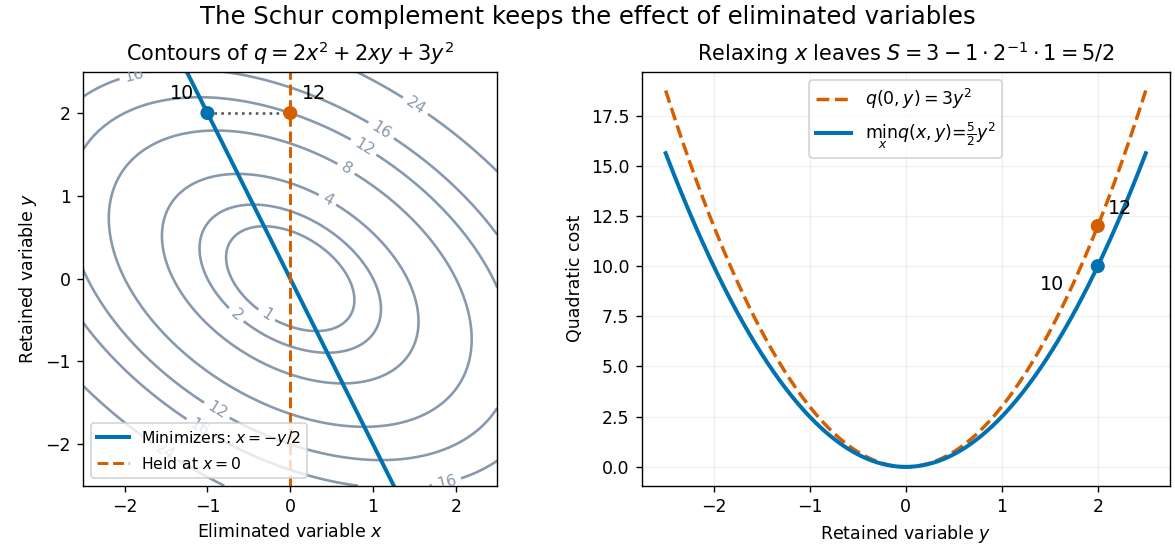

This interpretation supports quadratic optimization and the positive-definite symmetric matrix tests used in Cholesky decomposition. In a multivariate normal distribution, a covariance matrix also gives a conditional covariance through a Schur complement; the required probabilistic hypotheses are supplied by conditional multivariate normal distribution, rather than by the algebra alone.
Articles by others on the same topic
There are currently no matching articles.