A real matrix is symmetric when . It represents a self-adjoint operator in the standard Euclidean inner product.
The singular real symmetric matrices of size two form the double cone in these coordinates. Its complement has three connected components: is positive definite, is negative definite, and is indefinite. This follows also from the eigenvalues . The definite cones are convex. In the indefinite region, first move to zero, then move the nonzero planar vector within the punctured plane, proving path-connectedness. Continuous determinant and trace signs prevent joining different regions without crossing singular matrices.
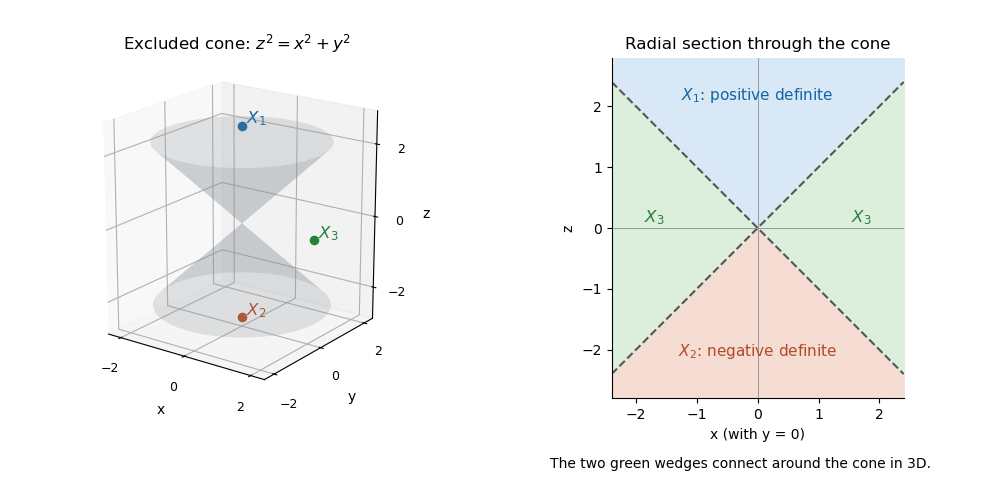
The determinant cone for real symmetric two-by-two matrices and a radial section
. The cone itself is excluded. The two indefinite wedges visible in the section belong to one connected region in the full three-dimensional space. Details.Let be fixed real symmetric matrices, with , , and a simple eigenvalue. Complete to an orthonormal eigenbasis with eigenvalues . Put and . Then . The symmetric eigenvalue residual bound produces an eigenvalue in Big O notation.
For real , the displayed symmetric matrix satisfies . If , choose with and . The eigenvectors and are orthonormal and have eigenvalues and . The half-angle description works even when , avoiding an artificial division by an off-diagonal entry. If , the matrix is zero and every direction is an eigenvector. The normalized matrix is reflection in the axis at angle .
If and , then . Hence their product is a symmetric matrix exactly when they commute. For example, and are symmetric but have nonsymmetric product . This criterion differs from asking whether an arbitrary matrix can be factored as a product of symmetric matrices.
Let be a real unit vector in -dimensional Euclidean space. Then is a rank-one orthogonal projection: , while for orthogonal to . Consequently the symmetric matrix has eigenvalue on the line spanned by and eigenvalue on its orthogonal complement. Any orthonormal basis of that complement completes to an orthonormal eigenbasis. ThusThe trace and determinant formulas remain valid when one of these eigenvalues is zero. When , all nonzero vectors have the same eigenvalue, and the chosen splitting is optional.
The displayed nonzero matrix is symmetric under transpose but not Hermitian. It is nilpotent, so all its eigenvalues are zero and it cannot be diagonalizable. Thus real-symmetric spectral conclusions require reality or a Hermitian hypothesis; complex transpose symmetry alone is insufficient.
Fix , put , , and . Any real symmetric matrix on three-dimensional Euclidean space has a unique decomposition with , and :The transverse restriction is a symmetric two-dimensional matrix, whose traceless matrix part has dimension two. Together the two scalars, two components of and two components of give the six parameters of .
A real symmetric matrix is positive definite when its quadratic form is positive on every nonzero vector. By the spectral theorem, this is equivalent to all its eigenvalues being positive. It has a unique symmetric positive-definite square root.
Two real symmetric matrices are coaxial when they share an orthonormal eigenbasis. Equivalently they commute. Degenerate eigenspaces can have several choices of shared axes.
A real symmetric matrix is a Hermitian matrix, so is real for every complex vector . If is an eigenvector, its eigenvalue is and is real. Then gives . Reality is used in changing conjugate transpose to transpose; complex symmetry alone does not imply real eigenvalues.
A real symmetric matrix has real eigenvalues, orthogonal eigenspaces for distinct eigenvalues, and an orthonormal basis of eigenvectors. From diagonalizability, apply the Gram-Schmidt process within each eigenspace; all its linear combinations stay in that eigenspace. This gives with an orthogonal matrix and real diagonal .
A real symmetric matrix is copositive if its quadratic form satisfies for every in the nonnegative orthant. Every positive semidefinite matrix and every symmetric nonnegative matrix is copositive, as is their sum. The converse fails for the Horn copositive matrix.
A real symmetric matrix whose quadratic form is positive at every nonzero vector in the nonnegative orthant. By compactness of the nonnegative unit sphere, this is equivalent to a positive uniform lower bound on that orthant. It need not be a positive-definite matrix.
The five-dimensional Horn copositive matrix has diagonal entries , entries on the edges of the five-cycle, and entries on the remaining pairs:For , a cyclic relabelling puts a smallest coordinate at . The identitythen proves that is a copositive matrix.
However, is outside the positive-semidefinite-plus-nonnegative cone. Set . Its quadratic form is zero. If with a positive semidefinite matrix and a symmetric nonnegative matrix, both and must vanish. Positivity of the first three coordinates of forces every entry of the leading block of to vanish. Applying the argument to all cyclic shifts of forces every entry of to vanish, since each pair of indices lies in a cyclic interval of length three. This would make a positive semidefinite matrix, but zero quadratic form of a positive semidefinite matrix would then give , whereas .
Every real symmetric matrix has an orthonormal basis of real eigenvectors. Equivalently, it admits an orthogonal diagonalization with real diagonal and an orthogonal matrix.
This is the finite-dimensional real-symmetric case of the spectral theorem.
Articles by others on the same topic



Can represent a symmetric bilinear form as shown at matrix representation of a symmetric bilinear form, or a quadratic form.