Every real symmetric matrix that is a positive-definite matrix has a unique Cholesky decomposition , where is a lower triangular matrix with positive diagonal entries.[ref]
DPOTRF (LAPACK 3.12.1) by LAPACK project. DPOTRF, LAPACK 3.12.1: Purpose, lower-triangular factorization; UPLO and INFO argument documentation
For a complex Hermitian positive-definite matrix, the corresponding factorization is , with the conjugate transpose and the diagonal of positive and real.[ref]ZPOTRF (LAPACK 3.12.1) by LAPACK project. ZPOTRF, LAPACK 3.12.1: Purpose, Hermitian factorization with conjugate transpose
The factorization turns a linear system into two triangular systems.For example, matching entries in givesChoose the positive square roots in order: , and . ThereforeThe second radicand, , is the scalar Schur complement remaining after eliminating the first variable. A positive diagonal of alone would not guarantee that this quantity is positive; Sylvester's criterion explains the relevant leading principal minors.
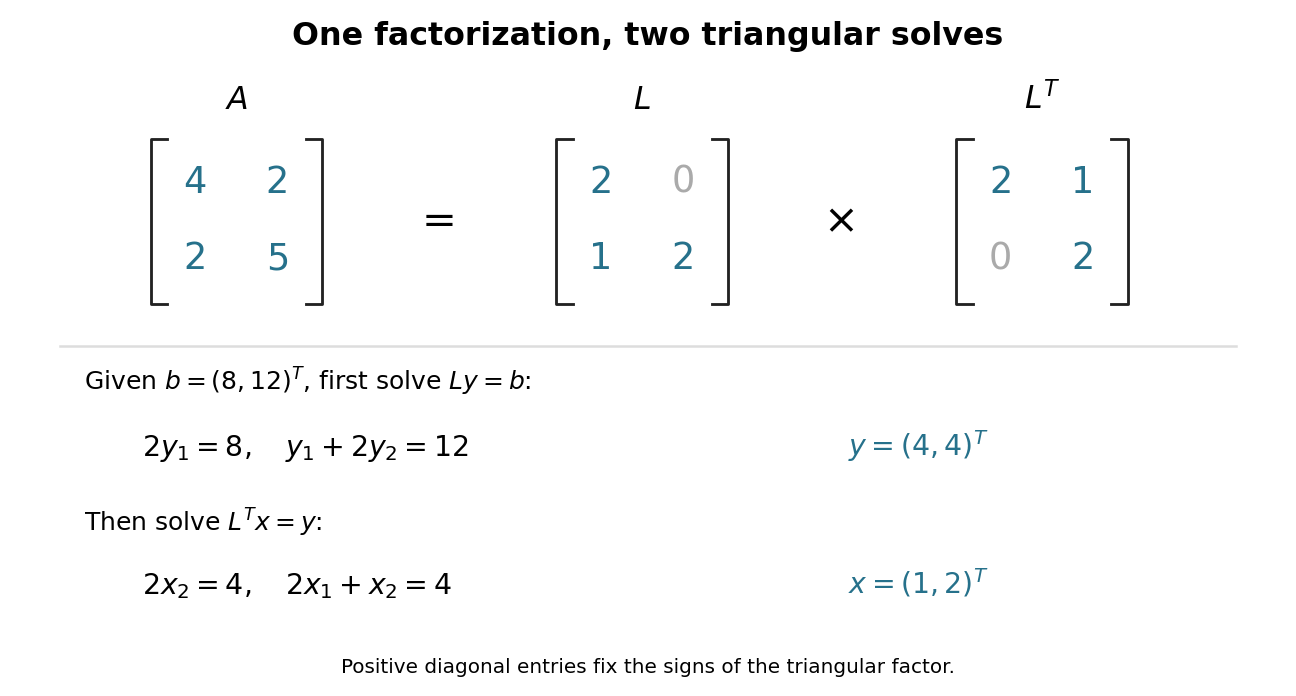
For that right-hand side, first use forward substitution to solve : and , so . Then use backward substitution in a triangular system to solve : and , giving . No matrix inverse is required. For several right-hand sides with the same , keep the same factor and repeat only these triangular solves.
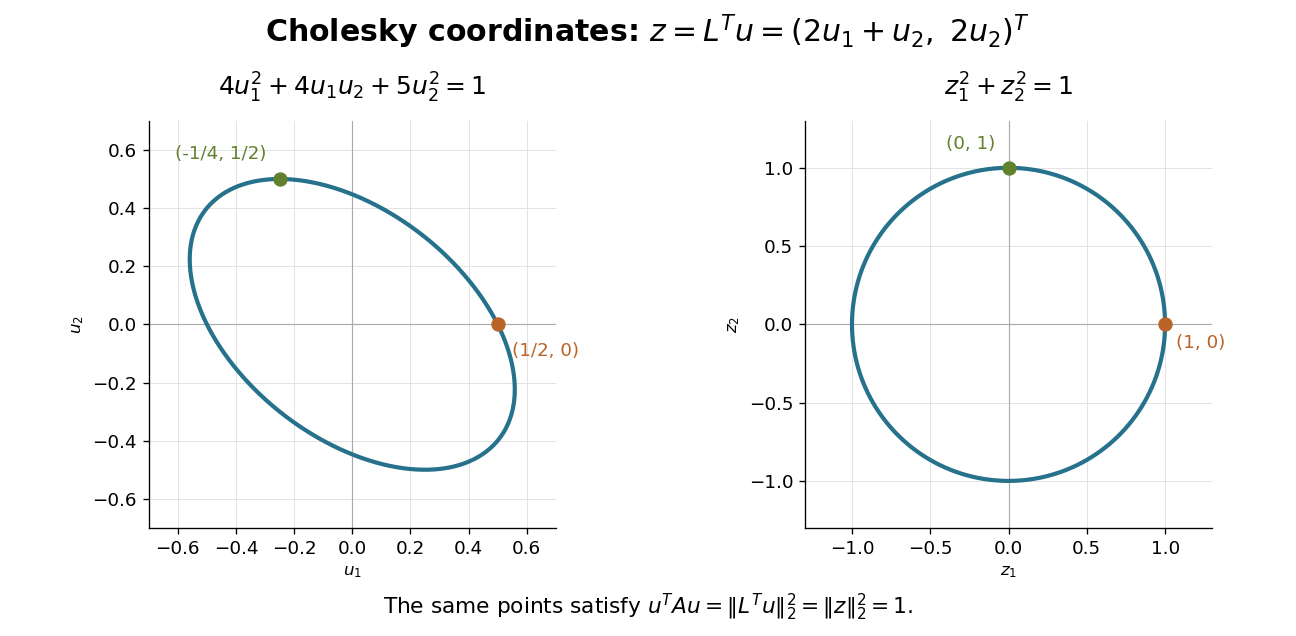
For any real vector , a Cholesky decomposition gives the quadratic form identitySince is an invertible matrix, this squared Euclidean norm is positive whenever . The factorization thus certifies positive definiteness and gives coordinates in which the quadratic form is a sum of ordinary squares. For the matrix above,The level set is an ellipse; the linear map sends it to the unit circle. The points and go to and , respectively.
The same factor works in the reverse direction for Gaussian random vectors. If has independent unit-variance, zero-mean Gaussian random variables as coordinates, has covariance matrix . In this example and : their variances are and , while their covariance is . This is a concrete way to generate specified correlations from independent draws.
A triangular factor is not generally a square root of a matrix in the sense . Here . The Cholesky decomposition uses the product with the transpose, which is also what makes the quadratic form a squared Euclidean norm.
André-Louis Cholesky developed his calculation in the setting of geodetic adjustment: measured angles and lengths must satisfy geometric relations, while corrections should be small. The manuscript reproduced in Claude Brezinski's study is titled Sur la résolution numérique des systèmes d’équations linéaires and ends with the date 2 December 1910 at Vincennes. The manuscript reports a 56-equation calculation adjusting altitudes in an Algerian triangulation network. Its date establishes when this written account existed, rather than an exact invention date.[ref]
La méthode de Cholesky by Claude Brezinski. Claude Brezinski, La méthode de Cholesky, printed pp. 210–211: geodetic least-squares corrections; p. 217: manuscript title and caution about invention date; §4, p. 229: reproduced manuscript's 56-equation adjustment and closing date
A related algebraic reason for the method's usefulness is that normal equations involve a Gram matrix. If a real matrix has linearly independent columns, thenso is a positive-definite matrix. That gives the structure needed by a Cholesky decomposition. The historical adjustment problem instead produces from independent constraint rows; the same argument applies to its transpose. In numerical least squares, explicitly forming normal equations squares the condition number of a full-column-rank design matrix; a QR decomposition can therefore be preferable for accuracy. Indeed, the extreme singular values give . The factorization remains useful when a positive-definite matrix is already the natural input.
Given a Cholesky decomposition , a rank-one Cholesky update computes a triangular factor of in operations without refactorizing the matrix from scratch.
Articles by others on the same topic



Cholesky decomposition is a mathematical technique used in linear algebra to decompose a symmetric, positive definite matrix into a product of a lower triangular matrix and its conjugate transpose. Specifically, if \( A \) is a symmetric positive definite matrix, the Cholesky decomposition states that: \[ A = L L^T \] where: - \( L \) is a lower triangular matrix with real and positive diagonal entries.