A quadratic form on a vector space over a field is a function satisfying whose polar bilinear form of a quadratic form is a bilinear form. In finite dimension, it is represented in coordinates by a homogeneous degree-two polynomial, or by with a suitable matrix .
When the characteristic is not two, one may choose to be a symmetric matrix and recover it from . In characteristic two, the symmetric-matrix restriction would lose examples: has an upper-triangular representing matrix , while for a symmetric matrix has no cross term. Its polar form is , an alternating bilinear form. The distinction matters when studying quadratic forms over finite fields.[ref]
A quadratic form over a field is an anisotropic quadratic form if forces . An isotropic quadratic form instead has a nonzero zero vector. This is a property of the form together with its coefficient field, rather than just the displayed polynomial.[ref]
Introduction to quadratic forms by Bill Casselman. Section 2, isotropic and anisotropic vectors, printed page 5
For example, is anisotropic over . If a nonzero rational solution had , then too; otherwise would be a rational square root of two. Over , however, is a nonzero zero vector. The coordinate change , gives , a hyperbolic plane of a quadratic form.
This example also separates anisotropy from positive definiteness: the rational form takes the positive value and the negative value , despite having no nonzero rational zero. In a Witt decomposition, an anisotropic remainder is what remains after all hyperbolic planes have been split off. Its Witt index is zero. In characteristic two, one must test vanishing of the quadratic form itself; properties of the associated polar bilinear form alone do not supply the same test.
For a finite-dimensional nonsingular quadratic form over a field of characteristic different from two, a Witt decomposition is an orthogonal splittingwhere is a hyperbolic plane of a quadratic form and is an anisotropic quadratic form. The integer is the Witt index. Both and the isometry class of the anisotropic part are determined by , although the particular subspaces realizing the splitting need not be unique.[ref]
Over , take . Set , and . Thenso . The one-dimensional remainder is anisotropic and the Witt index is one. This is an isometry of quadratic spaces, stronger than merely expressing the underlying vector space as a direct sum.
The construction starts from an isotropic vector, finds a partner with nonzero polar pairing, and splits off the hyperbolic plane they generate. Repeating the process ends when no nonzero isotropic vector remains. The decomposition makes the isotropic directions and the residual arithmetic obstruction visible separately.
The Witt index of a nondegenerate quadratic form on a finite-dimensional vector space is the largest dimension of a totally isotropic subspace: a linear subspace for which for every . In characteristic different from two, the Witt decomposition writeswhere is a hyperbolic plane of a quadratic form, is an anisotropic quadratic form, and is the Witt index. The anisotropic part has no nonzero vector on which the form vanishes.[ref]
For the real form , the subspace spanned by and is totally isotropic. Projection onto the two negative coordinates is injective on any totally isotropic subspace, giving the matching upper bound two. More generally, a real form of signature has Witt index .
The base field matters: has index zero over but index one over , using the line spanned by . In characteristic two, vanishing of the associated polar form on alone is insufficient; the condition remains . Over a finite field, the two nondegenerate types in dimension have Witt indices and .[ref]
The geometry of orthogonal groups over finite fields by Akihiro Munemasa. section 2, definition of Witt index and Theorem 2.11
Apply the product rule to the scalar quadratic form and transpose its last scalar term: . Only the symmetric part of contributes to its value or its derivative with respect to . A varying matrix also contributes the independent term . No assumption that is symmetric is needed. Repeating this rule and the chain rule computes mixed derivatives when vector and matrix arguments depend on separate parameters.
The quadratic form gradient gives . Since is invertible, this linear map is nonzero exactly when . The regular level set theorem therefore makes every nonzero point of a smooth point of dimension . If , the entire level set is smooth.
If and the level set contains a nonzero point, the form is an indefinite quadratic form. Its only singular point is the origin. To prove this rather than merely observe a vanishing derivative, use Sylvester's law of inertia to write with both sign spaces nonzero. The null vectors span the whole ambient space. Their straight-line curves through the origin lie in the cone. If a relatively open neighborhood of the origin in the cone were an embedded submanifold, its tangent space would contain all these directions and hence have dimension . It would then be open in the ambient space, impossible for the zero set of this nonzero quadratic form. Thus the smooth locus is .
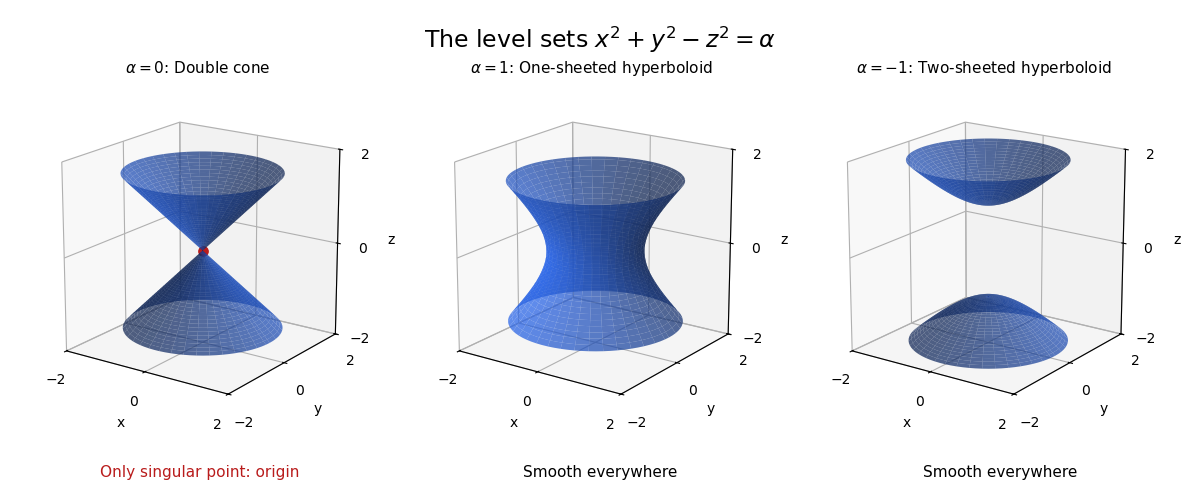
Three levels of an indefinite quadratic form in three dimensions
. Original diagrams and generic model calculations generated by the adjacent Python script. Details.For a real symmetric matrix with nonnegative eigenvalues, the finite-dimensional spectral theorem changes the equation to in an orthonormal eigenbasis. If and has positive rank, the positive-eigenvalue coordinates form an ellipsoid, while the zero-eigenvalue coordinates are arbitrary. The level set is therefore a cylinder over that ellipsoid, with axis directions given by the kernel of a linear map of . For rank two in three dimensions, it is an elliptic cylinder. At the level set is exactly the kernel of a linear map; for it is empty. This distinguishes a positive semidefinite matrix from a positive-definite matrix, whose positive level sets are bounded ellipsoids.
The displayed bilinear form is the polar form of a quadratic form. In odd characteristic of a field, recovers the quadratic form; in characteristic of a field two, different forms can have the same alternating bilinear form. Over , two such forms differ by a linear map to the field, giving the affine parametrization of binary quadratic refinements.
An integral quadratic lattice is a finite-rank free abelian group with a nondegenerate integral symmetric bilinear form. Its norm convention here is . A basis gives an integral Gram matrix; basis changes preserve its determinant up to multiplication by the square of a unit.
Every vector in an even lattice has even integral norm. The E8 lattice and the hyperbolic plane appearing in the K3 intersection lattice are examples.
The integral Gram determinant has absolute value one, equivalently the lattice equals its bilinear-form dual. The K3 intersection lattice is an indefinite example.
An integral quadratic lattice that is both an even lattice and a unimodular lattice. The K3 intersection lattice has signature , while the positive-definite E8 lattice has rank eight.
The positive-definite rank-eight even unimodular lattice can be realized as vectors in or whose coordinate sum is even, with the ordinary Euclidean inner product. Negating this form gives in the K3 intersection lattice.
Its symmetric matrix is . The line spanned by has eigenvalue and its orthogonal complement has eigenvalue . Thus for it is nondegenerate with inertia ; for it vanishes. This gives a useful explicit example for Sylvester's law of inertia.
Let be a quadratic form whose polar bilinear form of a quadratic form is nondegenerate, so . For a symplectic basis , defineThis does not depend on the symplectic basis. The hyperbolic plane has Arf invariant zero; has Arf invariant one and vanishes only at zero. Every such quadratic form is an orthogonal direct sum of hyperbolic planes, with one copy of the latter plane replacing a hyperbolic plane when the Arf invariant is one.[ref]
Bilinear Forms by Keith Conrad. Section 7, equation (7.11) and classification over finite fields of characteristic two
A useful basis-independent test isOn one two-dimensional summand with symplectic basis , write ; the four terms sum to . Multiplication over the orthogonal direct sum proves the formula and the invariance of its sign. Consequently the number of zeros is . For a fixed and , the numbers of binary quadratic refinements with Arf invariant zero and one are respectively and .
A binary quadratic refinement of a fixed nonsingular alternating bilinear form has polar form . The difference of two refinements is linear, so nondegeneracy gives the displayed unique parametrization by . For , refinements of plus and minus Arf invariant of a quadratic form have respectively and elements. Completing the square in the binary character sum gives .
The symplectic group over a finite field is transitive on each of the two quadratic types. The stabilizer of a refinement is its orthogonal group over a finite field. In the displayed parametrization, other refinements of the same type correspond to nonzero singular vectors, and refinements of opposite type to nonsingular vectors. Witt's lemma makes the orthogonal stabilizer transitive on each of these vector sets. Thus both type actions are two-transitive for , and a minus stabilizer is transitive on the plus orbit. For the minus orbit is a singleton.
Over a field of characteristic different from two, a quadratic homogeneous polynomial determines a unique symmetric bilinear coefficient tensor. An antisymmetric addition to its coefficient array gives zero contribution, so tensorial conditions on its coefficients must refer to this symmetric representative. In particular, the correspondence between quadratic geodesic first integrals and rank-two Killing tensors uses symmetric coefficients.
Write a real quadratic polynomial as , with symmetric. If is invertible, translation by removes the linear term. An orthonormal eigenbasis then makes the remaining quadratic form diagonal. Eigenvalue signs and the translated constant determine the real geometry, such as an ellipsoid or a one-sheet hyperboloid. A singular requires separate treatment of linear terms in its null directions; a center need not exist.
Two square matrices are congruent when for an invertible matrix . This is the transformation of the matrix of a bilinear form under change of basis, and also transforms a quadratic form under an invertible linear map on its coordinates. The matrices need not be symmetric. It differs from matrix similarity, which uses for a linear operator. For real symmetric matrices, completing the square diagonalizes the corresponding quadratic form by matrix congruence.
If is real symmetric positive definite and is real symmetric, let . The matrix is symmetric and has an orthonormal eigenbasis, represented by . Taking gives the two displayed congruences. The diagonal entries are determined by the generalized eigenvalue problem , since is diagonal with entries . Positive definiteness of the first form is essential to this construction.
A real quadratic form is positive definite when for every nonzero vector . In a basis that diagonalizes it, this is equivalent to every diagonal coefficient being positive.
A real quadratic form is indefinite when it takes both positive and negative values. For a real symmetric matrix representing it, this means that its eigenvalues include both signs. For example, has and ; a zero value at the nonzero vector does not imply positive semidefiniteness.[ref]
Bilinear Forms by Keith Conrad. Definition 6.21 and footnote 6, p. 40: definiteness and a nondegenerate indefinite example
A real symmetric matrix is indefinite when is an indefinite quadratic form. Equivalently, has both a positive and a negative eigenvalue, by the spectral theorem. A zero eigenvalue is permitted, so an indefinite matrix need not be an invertible matrix.
A ternary quadratic form is a quadratic form in three variables. A diagonal integral example is with integer coefficients .
Over a finite field of odd cardinality , a diagonal nondegenerate ternary quadratic form has a zero with : the sets and both have elements and must intersect. This gives a nonzero nonsingular zero. Over a local integer ring with these coefficients units, the Hensel lemma lifts it to an isotropic vector in the fraction field.
This ternary quadratic form has a nonzero zero over exactly when . Away from , the finite-field square-set intersection proof supplies a nonsingular residue zero, and Hensel lemma lifts it. At 5 use modulo 5; at 13 use . At 2 hold and apply the strong form of Hensel lemma to at : the function and derivative have valuations 3 and 1. At 7, the equation modulo 7 forces because 5 is not a square; reduction after dividing by 7 then forces . Any normalized integral nonzero solution would therefore have all coordinates divisible by 7, a contradiction.
A hyperbolic plane is a two-dimensional vector space with a quadratic form and a basis satisfying and , where is the polar bilinear form of a quadratic form. Equivalently, . This definition also applies in characteristic two. Over the real numbers, the identity gives one positive and one negative square, hence signature zero. The signature statement is specific to real quadratic forms.
The parallelogram law for a quadratic form isConversely, under the usual divisibility assumptions, a function satisfying this identity and the appropriate homogeneity comes from a symmetric bilinear form by polarization.
For an inner product space, taking gives the displayed squared-norm identity by expanding and cancelling the mixed inner products. It is the geometric ingredient that makes minimizing sequences converge in the Hilbert projection theorem.
A complex normed vector space has an inducing inner product exactly when its norm satisfies the parallelogram law. Define . Subtract two parallelogram identities to obtain . Taking gives doubling, and then replacing by the half-sum and half-difference gives additivity. Integer scaling and division give rational homogeneity; continuity gives real homogeneity. Thus is a symmetric real-bilinear form. The complex formula satisfies , because and . Symmetry gives conjugate symmetry of , and gives positive definiteness. The reverse implication follows by expanding squared norms. Completeness is needed only for the resulting inner product space to be a Hilbert space.
Over a field of characteristic different from two, the rank of a quadratic form is the rank of a linear map associated with its symmetric bilinear form, equivalently the matrix rank of a symmetric coefficient matrix. For an -dimensional vector space this is . A change of basis acts by matrix congruence, which preserves matrix rank.
For example, has rank two, although it vanishes at the nonzero vector . Its radical of a bilinear form is the -axis; an isotropic vector need not lie in that radical. In characteristic two, the polar bilinear form of a quadratic form can lose square terms: is nonzero but its polar form is zero. The rank of that polar form alone therefore does not record all quadratic information; conventions for quadratic rank in characteristic two require separate care.
A rank-one quadratic form is the square of a linear form up to a scalar. More generally, a bilinear expression is rank one because its coefficient matrix is the outer product .
The signature of a real quadratic form is the number of positive squares minus the number of negative squares in its diagonal normal form.
Over a field of characteristic other than two, a quadratic form recovers its symmetric bilinear form by
For a complex sesquilinear form , the values determine . In particular, expanding at and shows that for every implies . Over the reals this conclusion can fail for nonsymmetric bilinear forms, as a nonzero skew-symmetric form has zero diagonal.
A symmetric bilinear form is positive semidefinite when for every , and positive definite when equality is possible only for .
A Hermitian matrix is definite when either for every nonzero vector , or for every nonzero vector . These are the positive-definite matrix and negative-definite matrix cases. By the spectral theorem, all eigenvalues must have the same strict sign, so every definite matrix is invertible.
A positive semidefinite matrix permits zero eigenvalues and need not be definite. For example, is positive semidefinite but not definite, while is an indefinite matrix. Definiteness concerns the sign on every nonzero vector, not merely one diagonal entry or the determinant.
A real symmetric or complex Hermitian matrix is positive semidefinite when for every vector , equivalently when all its eigenvalues are nonnegative.
For positive block sizes, the real matrix is a positive semidefinite matrix exactly when . For test-vector block sums , its quadratic form is . This proves sufficiency; testing proves necessity. Zero sums in both blocks describe part of its kernel.
A real symmetric matrix admitting a finite sum of nonnegative rank-one matrices . It is both a positive semidefinite matrix and a nonnegative matrix, but these two properties alone need not imply membership in the completely positive cone in arbitrary dimension. This matrix notion is distinct from a completely positive map.
If is a real positive semidefinite matrix, then if and only if . Indeed by the principal square root of a positive semidefinite matrix, so a zero quadratic form puts in the kernel of and hence of .
For real positive semidefinite matrices , their product need not be symmetric, but its matrix trace is nonnegative:The equality uses the cyclic property of the matrix trace, and the last matrix is a positive semidefinite matrix. Consequently the Loewner order inequality implies whenever .
If is real symmetric and positive semidefinite, its principal square root isIt is symmetric and positive semidefinite, and is positive definite exactly when is.
Every invertible real matrix has the polar decompositionwhere is symmetric positive definite and is orthogonal.
Every invertible complex matrix has the unique polar decompositionwhere is a positive-definite Hermitian matrix and is a unitary matrix. Writing gives , which is Hermitian.
A real symmetric matrix is positive definite whenfor every nonzero real vector . It therefore defines the inner product and is invertible.
Let be a real symmetric positive-definite matrix, and let be a unit eigenvector with eigenvalue . The rank-one matrix update changes only the eigenvalue along , to . Symmetry makes the orthogonal complement invariant, and there because .
In detail, write with . ThenConsequently is a positive-definite matrix for , singular for , and has exactly one negative eigenvalue for . In dimension at least two the last case is indefinite. In dimension one it is negative definite instead: there is no nonzero orthogonal-complement direction. The distinction matters when classifying a stationary point of a quadratic form.
Every real symmetric matrix that is a positive-definite matrix has a unique Cholesky decomposition , where is a lower triangular matrix with positive diagonal entries.[ref]
DPOTRF (LAPACK 3.12.1) by LAPACK project. DPOTRF, LAPACK 3.12.1: Purpose, lower-triangular factorization; UPLO and INFO argument documentation
For a complex Hermitian positive-definite matrix, the corresponding factorization is , with the conjugate transpose and the diagonal of positive and real.[ref]ZPOTRF (LAPACK 3.12.1) by LAPACK project. ZPOTRF, LAPACK 3.12.1: Purpose, Hermitian factorization with conjugate transpose
The factorization turns a linear system into two triangular systems.For example, matching entries in givesChoose the positive square roots in order: , and . ThereforeThe second radicand, , is the scalar Schur complement remaining after eliminating the first variable. A positive diagonal of alone would not guarantee that this quantity is positive; Sylvester's criterion explains the relevant leading principal minors.
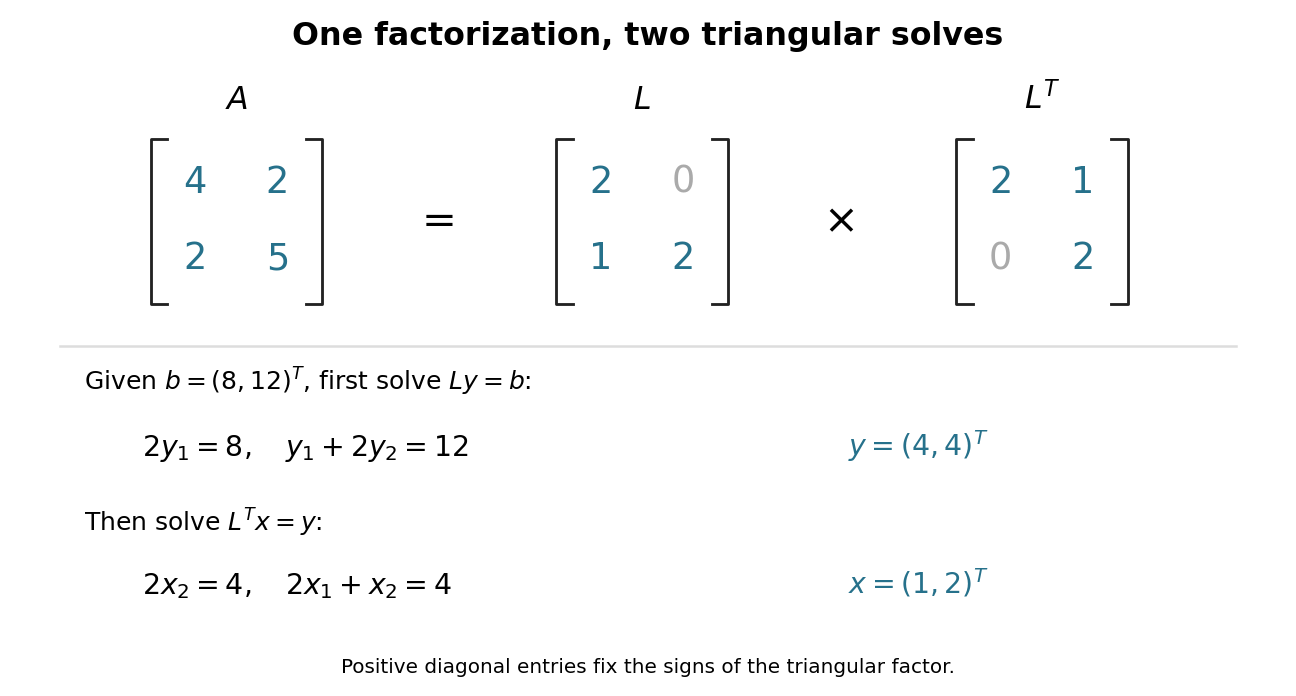
For that right-hand side, first use forward substitution to solve : and , so . Then use backward substitution in a triangular system to solve : and , giving . No matrix inverse is required. For several right-hand sides with the same , keep the same factor and repeat only these triangular solves.
For a real symmetric positive-definite matrix, the lower triangular matrix with positive diagonal in its Cholesky decomposition is its lower Cholesky factor; is the corresponding upper factor. If a full-column-rank matrix has a reduced QR decomposition with positive diagonal of , then , so is the upper Cholesky factor of .
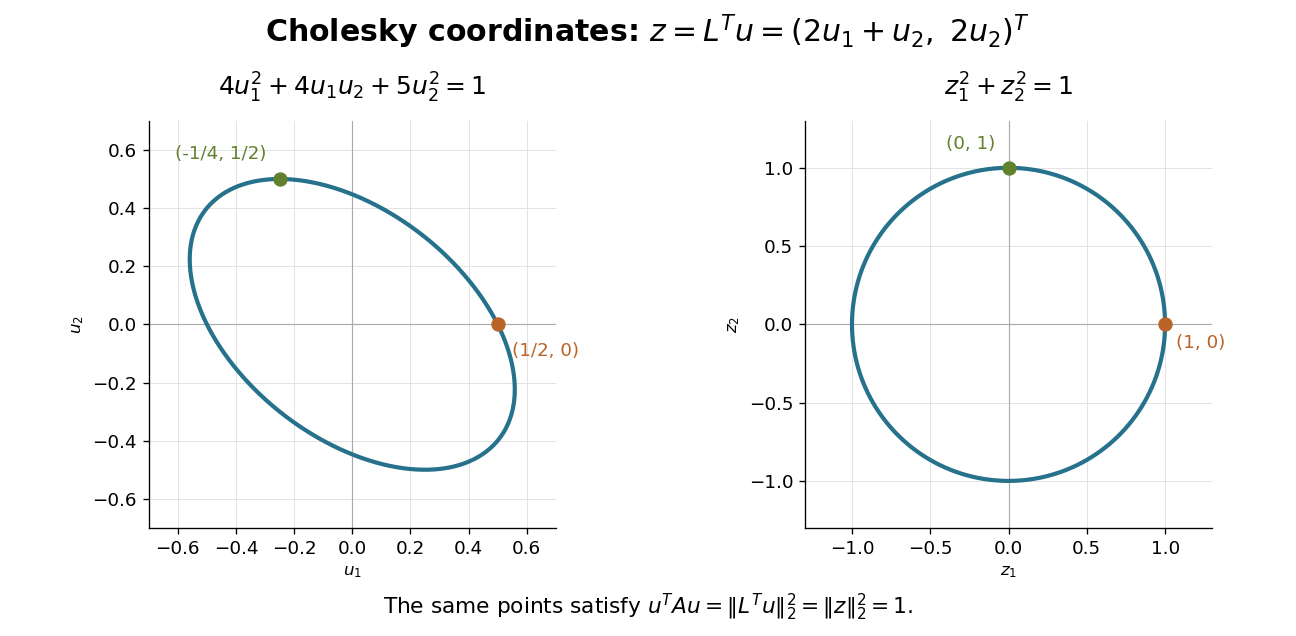
For any real vector , a Cholesky decomposition gives the quadratic form identitySince is an invertible matrix, this squared Euclidean norm is positive whenever . The factorization thus certifies positive definiteness and gives coordinates in which the quadratic form is a sum of ordinary squares. For the matrix above,The level set is an ellipse; the linear map sends it to the unit circle. The points and go to and , respectively.
The same factor works in the reverse direction for Gaussian random vectors. If has independent unit-variance, zero-mean Gaussian random variables as coordinates, has covariance matrix . In this example and : their variances are and , while their covariance is . This is a concrete way to generate specified correlations from independent draws.
A triangular factor is not generally a square root of a matrix in the sense . Here . The Cholesky decomposition uses the product with the transpose, which is also what makes the quadratic form a squared Euclidean norm.
André-Louis Cholesky developed his calculation in the setting of geodetic adjustment: measured angles and lengths must satisfy geometric relations, while corrections should be small. The manuscript reproduced in Claude Brezinski's study is titled Sur la résolution numérique des systèmes d’équations linéaires and ends with the date 2 December 1910 at Vincennes. The manuscript reports a 56-equation calculation adjusting altitudes in an Algerian triangulation network. Its date establishes when this written account existed, rather than an exact invention date.[ref]
La méthode de Cholesky by Claude Brezinski. Claude Brezinski, La méthode de Cholesky, printed pp. 210–211: geodetic least-squares corrections; p. 217: manuscript title and caution about invention date; §4, p. 229: reproduced manuscript's 56-equation adjustment and closing date
A related algebraic reason for the method's usefulness is that normal equations involve a Gram matrix. If a real matrix has linearly independent columns, thenso is a positive-definite matrix. That gives the structure needed by a Cholesky decomposition. The historical adjustment problem instead produces from independent constraint rows; the same argument applies to its transpose. In numerical least squares, explicitly forming normal equations squares the condition number of a full-column-rank design matrix; a QR decomposition can therefore be preferable for accuracy. Indeed, the extreme singular values give . The factorization remains useful when a positive-definite matrix is already the natural input.
Given a Cholesky decomposition , a rank-one Cholesky update computes a triangular factor of in operations without refactorizing the matrix from scratch.
A Hermitian matrix is a positive-definite matrix exactly when its leading principal minorsare all positive. The leading principal minor uses the first rows and the first columns in the same ordering. For the two-by-two Cholesky decomposition example, and , so the criterion proves positive definiteness without calculating eigenvalues.
The successive pivot elements before taking square roots are , with . Here they are and . In general, a leading triangular matrix factor has determinant equal to the product of its diagonal entries, soConversely, positive leading principal minors make each successive Schur complement pivot element positive, allowing the Cholesky decomposition to be constructed. The identity then proves positive definiteness; for complex matrices, replace the transposes by conjugate transposes. This gives a short inductive proof of the criterion.
For , the first minor is positive but . The second Cholesky radicand would be , and directly gives . Thus positive diagonal entries are insufficient. Replacing “positive” by “nonnegative” in just the leading-minor test is also insufficient for positive semidefiniteness: has leading minors , but its quadratic form is negative on .
The condition number of a problem measures how strongly relative perturbations of its input can amplify relative changes in its output. For an invertible matrix and a chosen operator norm, .
For a real symmetric positive-definite matrix,It measures the sensitivity of the linear system and controls convergence bounds for iterative solvers.
An symmetric tridiagonal Toeplitz matrix has one constant diagonal and equal constant subdiagonal and superdiagonal . Its eigenvectors are the discrete sine transform vectors , with eigenvalues .
For , the shifted skew-symmetric matrix , where has zero diagonal, superdiagonal , and subdiagonal , is a tridiagonal Toeplitz matrix. It is itself skew-symmetric only when over the real numbers or complex numbers. Its eigenvalues areAll such matrices share an orthonormal eigenbasis after the same diagonal unitary change from the discrete sine basis.
A real symmetric matrix is negative definite when for every nonzero real vector . Equivalently, is a positive-definite matrix and every eigenvalue of is negative.
Every real quadratic form is congruent to a diagonal form with entries , and the numbers of entries of each kind are invariant.
A vector can be included in a diagonal basis for a real quadratic form precisely when and either its quadratic value is nonzero or it lies in the radical of a bilinear form. A nonzero quadratic value gives the direct splitting and induction. A nonzero radical vector can be included in a radical basis. Conversely, an isotropic vector in a diagonal basis is orthogonal to every basis vector, and must lie in the radical.
A nondegenerate quadratic form over a number field is isotropic if and only if it is isotropic over every completion. Over , these are the real field and all P-adic numbers. It turns a rational existence problem into local tests; denominators can then be cleared for an integral homogeneous equation.
For a nondegenerate diagonal quadratic form , this product of quadratic Hilbert symbols is independent of diagonalization. Over a p-adic field, dimension, determinant square class and this invariant classify the form up to isometry. The product of the local invariants of a globally diagonalized form is one by the Hilbert reciprocity law; real places additionally record signature.
A subspace is totally isotropic for when for all . For a real nondegenerate bilinear form of inertia , its dimension is at most .
For a nondegenerate real quadratic form of inertia , projection of a totally isotropic subspace onto either its positive or negative coordinate subspace is injective: a vector with one projection zero would have strictly one-signed quadratic value unless it vanished. Thus its dimension is at most both and . This bound is attained by pairing one positive and one negative coordinate for each of independent null vectors.
A quadratic form of rank on is congruent to . Pair its nonzero coordinates into vectors , and include the radical of a bilinear form. Their span is a totally isotropic subspace and has dimension . The form vanishes on every vector of this subspace, not merely on its basis vectors.
Any quadratic forms on have a common nonzero zero when . Choose a totally isotropic subspace for the first form, of dimension at least . Restrict the remaining forms to it and repeat by induction. After stages at least one dimension remains. This elementary sufficient bound does not assert that is the best possible threshold.
For a real quadratic form on an -dimensional vector space, with rank and signature defined as positive minus negative index, the maximum dimension of a totally isotropic subspace is . Quotienting by the radical of a bilinear form leaves a nondegenerate form of indices . Projection of an isotropic subspace to each sign-coordinate space is injective, bounding its dimension by . The radical and vectors pairing one positive with one negative unit coordinate attain the bound .
Articles by others on the same topic

A quadratic form is a specific type of polynomial expression that involves variables raised to the second power, usually in the context of multiple variables.



Multivariate polynomial where each term has degree 2, e.g.:is a quadratic form because each term has degree 2:but e.g.:is not because the term has degree 3.
There is a 1-to-1 relationship between quadratic forms and symmetric bilinear forms. In matrix representation, this can be written as:where contains each of the variabes of the form, e.g. for 2 variables:
Strictly speaking, the associated bilinear form would not need to be a symmetric bilinear form, at least for the real numbers or complex numbers which are commutative. E.g.:But that same matrix could also be written in symmetric form as:so why not I guess, its simpler/more restricted.