Linear algebra studies vector spaces and linear maps: operations that preserve vector addition and scalar multiplication. For a linear map , the defining rule is , where are vectors and belong to the underlying field. The vectors might be arrows, lists of measurements, or polynomials. What matters is that their linear combinations make sense and that the same rule governs their transformation.
A concrete linear map is . Its two outputs record a sum and a difference. Since and , we immediately obtain . Knowing the outputs of the basis vectors determines the output of every vector; a matrix stores exactly that information in its columns.
The attraction of linear algebra is that one small collection of ideas answers several different questions. A system of linear equations asks which inputs produce a prescribed output. The image of a linear map describes the attainable outputs, while the kernel describes the invisible input changes. A basis gives every vector an address, and change of basis lets us choose addresses that make a linear map easier to understand. This shared language turns a collection of separate calculations into a picture of what is possible and how much freedom remains. Gilbert Strang's MIT course emphasizes these connections and their usefulness across other disciplines.[ref]
https://ocw.mit.edu/courses/18-06-linear-algebra-spring-2010/. Strang, MIT 18.06: Linear Algebra
The initial table of content was limited to the first level because it is larger than 1000 articles. There are 1212 articles in total. Expand a branch to load its children.
Two vectors spanning a hyperbolic plane. For an alternating bilinear form, choose ; then their span is nondegenerate. For a quadratic form with polar form , require also . The analogous definition for a Hermitian form uses two isotropic vectors of pairing one. Extending such pairs to adapted bases is useful for constructing form-preserving maps.
A Cartesian basis is an ordered basis of unit vectors along the mutually perpendicular axes of a Cartesian coordinate system. It is an orthonormal basis of a real Euclidean space: , with the Kronecker delta. In the plane, the familiar standard basis is , ; the vector is . A rotated pair of perpendicular unit vectors is also a Cartesian basis, even though its basis vectors have different standard basis entries.
The advantage is that coordinates can be measured separately by dot products, and the squared norm is the sum of their squares:These are the real Euclidean space instances of the orthonormal basis expansion.[ref]
Linear Algebra Done Right by Sheldon Axler (4th edition). §6B, Definition 6.27, printed p. 199, and Theorem 6.30(a–b), printed p. 200
An orthogonal basis only requires perpendicular basis vectors; their lengths need not be one. For example, are orthogonal, but has coordinates , while its dot products with them are . For an orthogonal basis , the coordinate along is . Dividing each nonzero basis vector by its norm makes it a unit vector without changing its direction. Unit length alone does not imply orthogonality: and are both unit vectors but have dot product .
The examples below show why these distinctions matter: rotating a Cartesian basis changes the coordinate vector while keeping lengths easy to compute; using nonperpendicular basis vectors still gives unique coordinates, but requires the dual basis or a matrix inverse to extract them.
Rotate the standard basis through using the rotation matrix whose columns are the new basis vectors:Here and , so is an orthogonal matrix with , where denotes transpose and is the identity matrix. For the same vector , its coordinate vector in this Cartesian basis isThus and : travel forwards along and a little backwards along to reconstruct . The orthogonal projections onto the two axes give these signed coordinates because the measuring vectors are both perpendicular and of unit length.
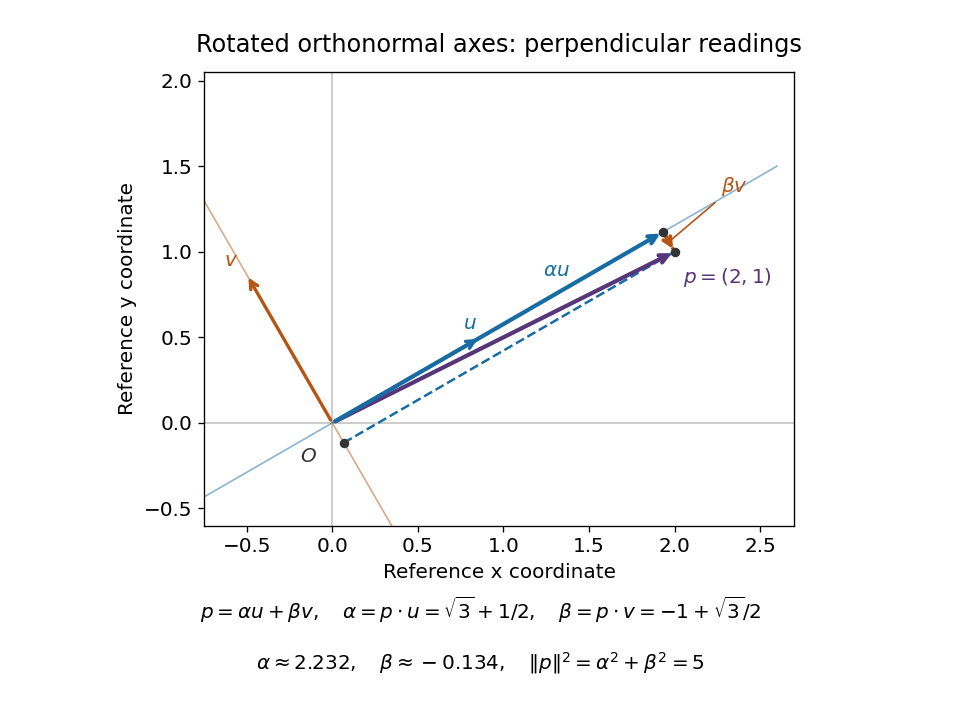
The squared norm remainsThis is useful when choosing axes aligned with a geometric feature: the coordinates change but distances and dot products retain the same sum-of-products formula. The two directions of the change of basis must be kept straight: reconstructs the vector in old coordinates, , and extracts its new coordinates. Applying to the old coordinate vector instead would actively rotate the vector.
A short proof explains both formulas. If , multiplication by gives . Then . Perpendicular unit-length columns make the matrix inverse equal the transpose; this is the computational convenience supplied by a Cartesian basis.
Keep the same origin and the same vector , but use the nonperpendicular basis vectors and . They form a basis because the column matrix has nonzero determinant:The reconstruction is . Its coordinates are read along lines parallel to the other axis, producing a parallelogram. These lines need not be perpendicular to the axis being measured. In contrast, the dot products are and ; treating those as coordinates would reconstruct , a different vector.
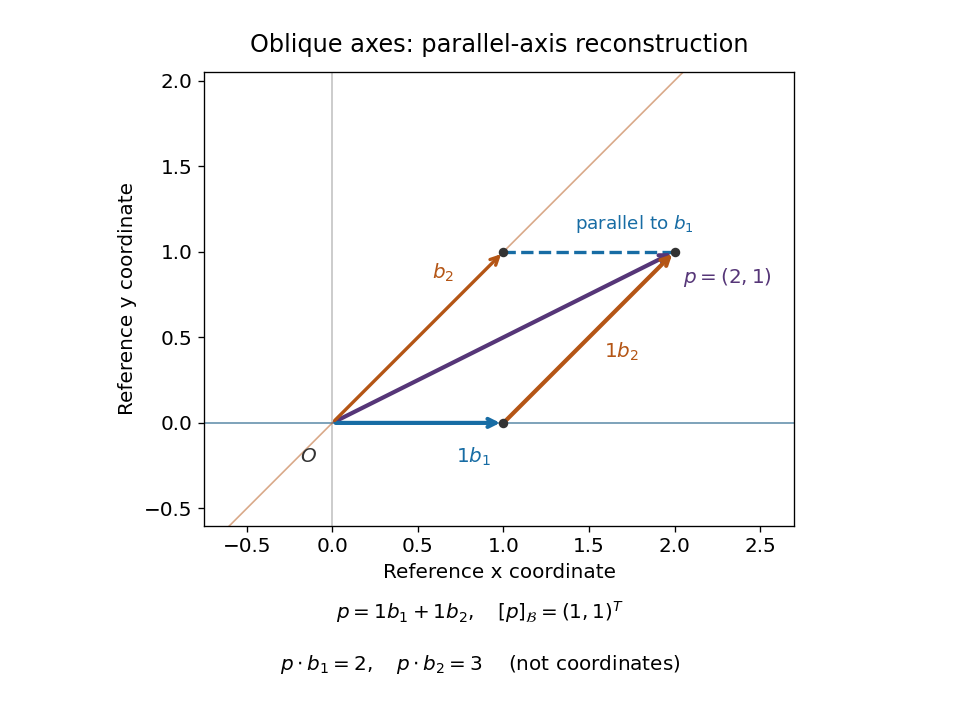
The dual basis supplies the right measuring rules for any basis.[ref]
Linear Algebra Done Right by Sheldon Axler (4th edition). §3F, Definition 3.112 and Theorem 3.114, printed p. 106: dual basis and coefficient extraction
Here these coordinate functionals are and , the rows of . They give . Equivalently, their representing vectors , satisfy and extract the coordinates as . These are Riesz dual basis in an inner product space representatives, rather than the original basis vectors.The Gram matrix records how the nonperpendicular directions interact:For any real basis represented by a square invertible matrix , writing gives these identities immediately. One can recover the coordinates either as or by solving . In this example, if , the squared norm is , not . Oblique coordinates remain useful when natural directions are not perpendicular, but the Gram matrix must accompany them when computing lengths or dot products.
A Cartesian frame combines a chosen origin point with a Cartesian basis , including its ordering as an ordered basis. A point has coordinate vector when . The basis supplies measuring directions and unit lengths; the coordinate vector is the resulting tuple of numbers; the Cartesian frame additionally fixes where measurement starts. A vector already belongs to a vector space with a zero vector, so expressing it in a basis requires no additional choice of spatial origin.
For example, keeping the standard basis but moving the origin from to changes the coordinates of the physical point from to . This happens because is a different displacement vector. By contrast, the two diagrams above keep fixed and change only the basis. In a fixed reference Cartesian frame, a new frame with origin column and basis-column matrix describes points by ; the new coordinates are when is an orthogonal matrix.
A bilinear form takes two vectors in a vector space over a field and returns a scalar in . Its defining property is separate linearity: holding either input fixed gives a linear functional of the other. For scalars and vectors ,This is a scalar-valued bilinear map; the chosen field is part of the definition.[ref]
Separate linearity does not mean that is a linear map on the vector space with componentwise vector addition and scalar multiplication. Over the real numbers, , whereas a linear map on the pair would give . The simplest example is on the one-dimensional vector space : fixing gives , but doubling both and quadruples their product.
A bilinear form measures how two inputs interact. The dot product measures alignment; a symmetric bilinear form can describe a quadratic form; an alternating bilinear form can measure signed area. A nondegenerate bilinear form turns each vector into a unique linear functional and so connects geometry with the dual space. The same short definition therefore supports lengths, bilinear orthogonal complements, and symplectic vector spaces, depending on the additional properties imposed.
Over the complex numbers, a bilinear form is linear in both inputs without conjugating either scalar. A Hermitian form instead is a sesquilinear form and conjugates when its inputs are exchanged. For complex matrices, the adjoint used with Hermitian forms and matrix C-star algebras is the conjugate transpose, whereas a bilinear form uses the ordinary transpose . For example, has , while the Hermitian form has .[ref]
Bilinear Forms by Keith Conrad. §1: examples and the Hermitian distinction
On square matrices over a field, the trace of a product is a symmetric bilinear form. Pairing with the matrix unit reads off entry , proving nondegeneracy. For real matrices of size at least two it is not positive-definite: a planar rotation block squares to and has self-pairing . On real diagonalizable matrices its self-pairing is the sum of the squares of the real eigenvalues. This matrix pairing differs from the trace pairing of a field extension.
Choose an ordered basis of a finite-dimensional vector space. The matrix of a bilinear form records all pairings of basis vectors, with . Writing and , separate linearity giveswhere the last expression uses the coordinate vectors of . Conversely, every matrix defines a bilinear form by this formula.[ref]
For a concrete bilinear form on , takeThen but : a bilinear form need not be a symmetric bilinear form. For and , first compute , then . Reversing the inputs gives and .
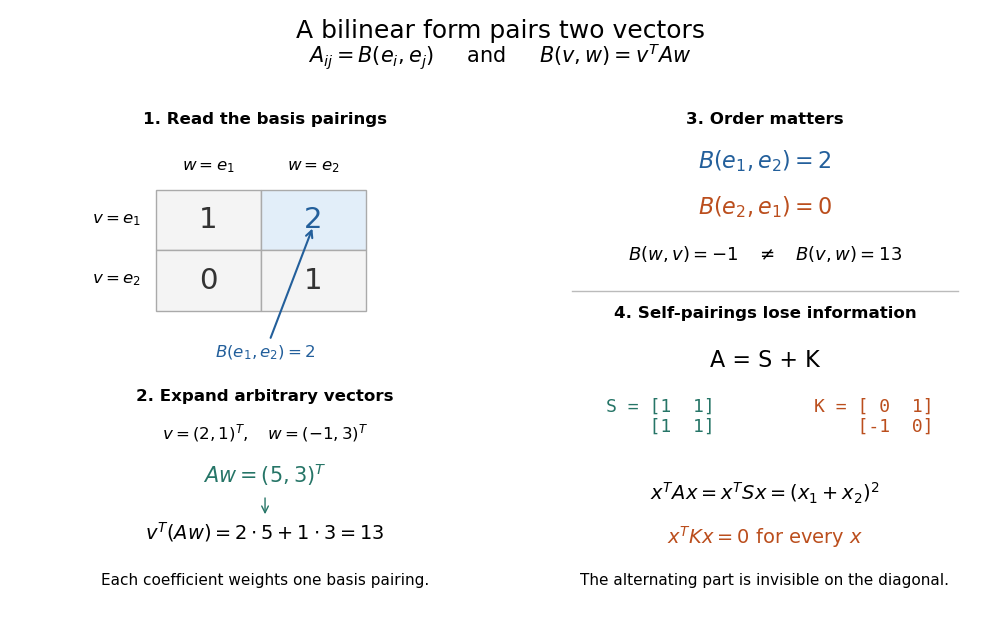
Under change of basis, let the columns of an invertible matrix be the new basis vectors in old coordinates. Thus and , soThis is matrix congruence, rather than the matrix similarity for an endomorphism. Both inputs have changed coordinates, which explains the two factors of . For the displayed and , direct multiplication gives ; its entry is .[ref]
Over a field whose characteristic is not two, a bilinear form has a unique decomposition into a symmetric bilinear form and an alternating bilinear form :Adding and subtracting the equations and both proves uniqueness and gives these formulas. In matrix notation, has matrix and has skew-symmetric matrix .[ref]
The diagonal values alone do not determine a general bilinear form, because for every vector. For the matrix of a bilinear form in the example above,Thus two different bilinear forms, represented by and its symmetric matrix part, have exactly the same quadratic form. To recover a bilinear form from its diagonal, one needs extra information such as the hypothesis that it is a symmetric bilinear form.
A bilinear form is symmetric when for every pair of vectors . Equivalently, its matrix of a bilinear form in any basis is a symmetric matrix, since . Symmetry makes the relation reciprocal, giving the bilinear orthogonal complement a geometric interpretation.
Over the real numbers, set . The polarization identityrecovers the symmetric bilinear form from its quadratic form: expand and use symmetry to combine the two cross terms. For , take and . Then , , and , so . The same formula works whenever the characteristic is not two.[ref]
https://www.ma.imperial.ac.uk/~anskor/LINEAR.PDF. Skorobogatov, Linear Algebra and Matrices, p. 12: recovering a symmetric form from the diagonal
Three real diagonal matrices show how much variety symmetry allows. The identity matrix gives the positive-definite bilinear form . The matrix gives and is nondegenerate despite the isotropic vector . The matrix gives and is a degenerate bilinear form with radical of a bilinear form . Their level sets make the distinction visible: a circle, two branches of a hyperbola, and two parallel lines for .
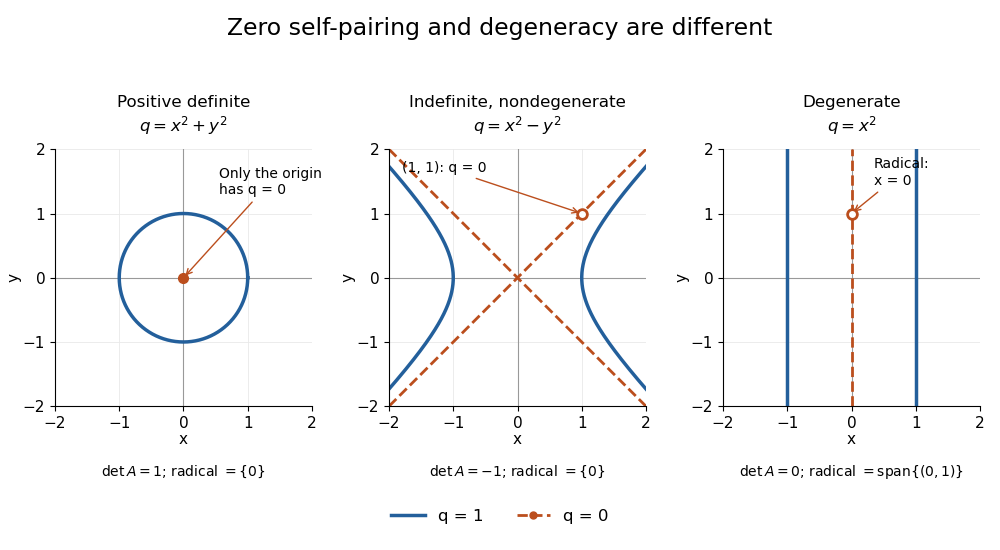
Unit and zero level sets distinguish positive, indefinite nondegenerate, and degenerate symmetric forms
. Details. The inertia of a bilinear form records the numbers of positive, negative, and zero directions after matrix congruence diagonalization. By Sylvester's law of inertia, these counts survive change of basis; the three examples have inertia of a bilinear form , , and . Historically, Sylvester stated this invariance in an 1852 paper on reducing real quadratic forms to sums of positive and negative squares. Ghys and Ranicki reproduce his statement and distinguish it from his subsequent 1853 proof.[ref]
https://arxiv.org/pdf/1512.09258. Étienne Ghys and Andrew Ranicki, Signatures in algebra, topology and dynamics, §1.2: Sylvester's statement and proof
A real symmetric bilinear form is positive-definite when for every nonzero vector. It defines an inner product and the associated norm . Symmetry is part of this definition: positive diagonal values by themselves do not imply symmetry.[ref]
The identity matrix gives and . For this is , giving norm . A weighted example, , gives norm : the first coordinate costs twice as much in length. Such inner products let geometry assign different weights to different directions.
Every positive-definite bilinear form is nondegenerate: a vector in its radical of a bilinear form has , so positivity forces . The converse fails, as shows. Even positivity of the associated quadratic form does not force a general bilinear form to be symmetric: has but and .
The complex Killing form is not positive-definite on the entire complex Cartan subalgebra; its restriction to the Euclidean subspace of a Cartan subalgebra is a real positive-definite form.
The strict positivity of a quadratic form on every nonzero vector. A real symmetric matrix has positive definiteness exactly when its associated quadratic form does, making it a positive-definite matrix. A Hermitian form is positive definite when its value on is real and strictly positive for every nonzero vector.
Think of a positive-definite quadratic form as an energy cost for a displacement: every direction costs something, and zero cost identifies the origin. For example, the real symmetric matrixis a positive-definite matrix because the two squares can vanish together only at . The mixed term couples the coordinates, but cannot overwhelm their positive contributions: and . The graph is a bowl, and its positive level sets are ellipses with axes along the eigenvectors, rather than along the original coordinates.
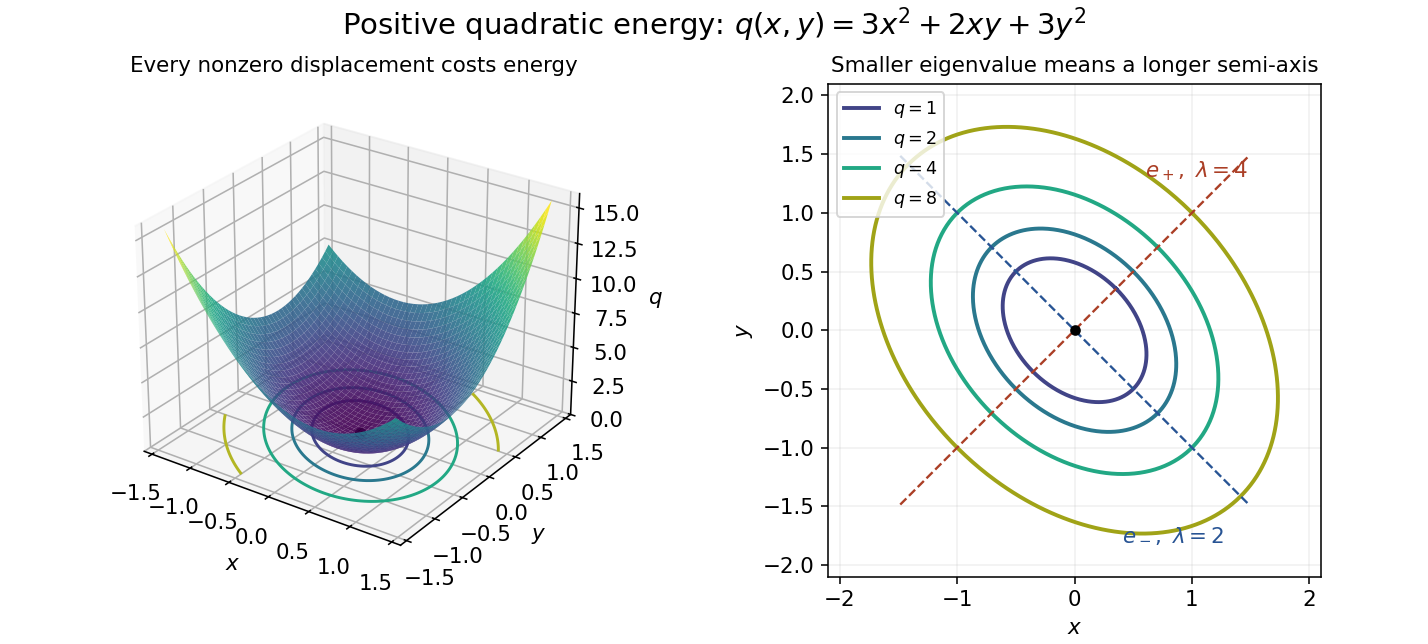
Positive quadratic energy bowl and elliptical level curves
. Details. The real and complex settings require different symmetry assumptions. For a real symmetric matrix use with ; for a complex Hermitian matrix use with , where is the conjugate transpose. The latter expression is real, so strict positivity is meaningful. A complex quadratic form such as has no such positivity: it vanishes at and takes negative real values at . A Hermitian form uses complex conjugation, which changes this example to .
For a real matrix without a symmetry hypothesis, its quadratic form depends only on its symmetric part of a matrix:Positive eigenvalues of alone do not establish positive definiteness of this quadratic form. For example, has both eigenvalues equal to , yet . The relevant test is positivity of the symmetric part of a matrix, not the spectrum of an arbitrary matrix.[ref]
For a real symmetric matrix , completing the square gives, when ,Thus is a positive-definite matrix exactly when and . For necessity, test first, then ; for sufficiency, the displayed two positive squares give the result. These are the first two leading principal minors in Sylvester's criterion. A positive determinant alone is insufficient: has determinant but is a negative-definite matrix.
The eigenvalues provide an equivalent test under the same real-symmetric hypothesis:The spectral theorem for real symmetric matrices supplies coordinates in an orthonormal basis in which . More generally, a complex Hermitian matrix has an orthonormal eigenbasis and , so it is a Hermitian positive-definite matrix exactly when every eigenvalue is positive. This is a short proof outline: test the eigenvectors for necessity, and sum the positive squared absolute values for sufficiency.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. Appendix A.5.2, pp. 646–647: symmetric eigenvalue decomposition and definiteness
For a real positive semidefinite matrix, the condition is instead for all vectors, equivalent here to , , and . If , the same completing the square proves this; if , nonnegativity forces and leaves with . Merely replacing the strict inequalities on the leading principal minors by nonstrict ones fails: has both leading principal minors zero yet gives . An indefinite quadratic form takes both positive and negative values; its real symmetric matrix has eigenvalues of both signs.
Vary the coupling in the opening example. The eigenvectors and form a fixed orthonormal eigenbasis, with eigenvalues and . Writing a vector as givesFor , both directions cost energy and is a positive-definite matrix. At , the quadratic form is : the entire line spanned by has zero energy, and is a singular positive semidefinite matrix. At , the flat line is instead spanned by . For , the quadratic form is an indefinite quadratic form; one direction lowers the energy without bound as its displacement grows. At , for instance, while .
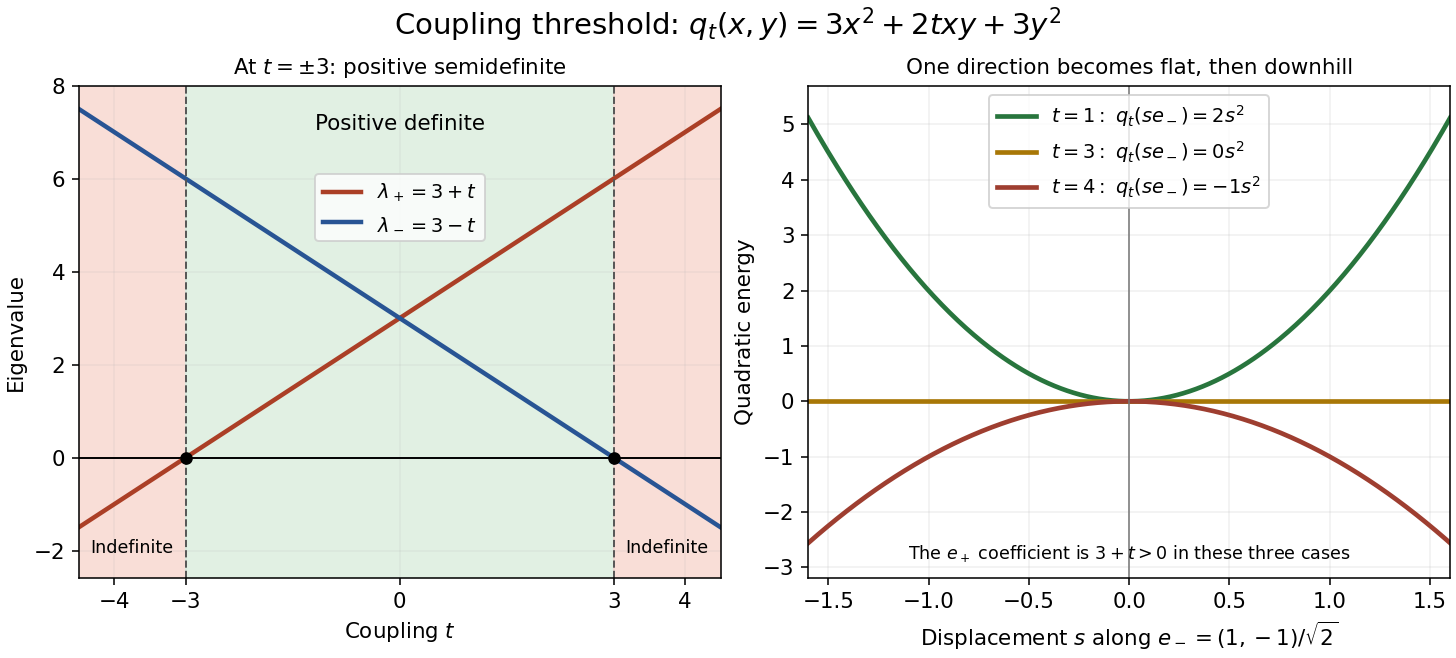
Eigenvalues and directional energies across the positivity threshold
. Details. The geometric transition is precise. For , is an ellipse. At , it consists of the two parallel lines , extending freely in the zero-energy direction. For , it is a hyperbola. The boundary case retains nonnegative energy but loses both the bounded positive level sets and the unique zero-energy vector.
For a real positive-definite matrix in finite dimension, write by the spectral theorem for real symmetric matrices. In the coordinates in an orthonormal basis , the positive level set becomesThis is an ellipsoid, with semi-major and semi-minor axes in two dimensions forming an ellipse; each semi-axis has length and direction given by the corresponding eigenvector. In the opening example, the shorter semi-axis is along , while the longer is along . A stiffer direction, meaning a larger eigenvalue, reaches the same energy at a smaller displacement. The ratio of longest to shortest semi-axis is , the square root of the spectral condition number of a positive-definite matrix.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. §2.2.2, p. 30, equation (2.3): ellipsoids and semi-axis lengths; the book uses the inverse quadratic coefficient matrix
Strict positivity matters because givesHence a fixed positive level set cannot extend arbitrarily far. The Cholesky decomposition gives another view: , so the ellipsoid is the inverse image of a sphere under an invertible linear map. A singular positive semidefinite matrix has a nonzero kernel; adding a kernel vector preserves its quadratic form, so any nonempty positive level set is unbounded. These statements concern finite dimension; the positive definite symmetric operator entry explains why strict positivity alone need not give a uniform lower bound on an infinite-dimensional Hilbert space.
Let be a real positive-definite matrix and minimize the displayed quadratic function over all of . Its gradient is , so its only stationary point solves the linear system . The matrix is an invertible matrix, making this solution exist and be unique. Completing the square around that solution proves the stronger global statement:The quadratic function is strictly convex, and its level sets above the minimum are translated ellipsoids. Positivity therefore turns solving a linear system into locating the bottom of a bowl.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. §3.1.4, Example 3.2, p. 71: a quadratic function is strictly convex exactly when its symmetric coefficient matrix is positive definite
For the opening matrix , take and . Then , , and . Every displacement raises the value by ; along the unit eigenvectors and the increases are respectively and for displacement or .
For a singular positive semidefinite matrix, a solution of is still a global minimizer, but adding any kernel vector gives another. If is outside the image of a linear map defined by , some kernel vector has , and is unbounded below. For an indefinite quadratic form, a negative eigenvalue gives a direction along which the quadratic term tends to regardless of . Thus a stationary point alone does not establish a minimum. The same energy-difference identity extends to the quadratic variational principle for a symmetric positive operator, with additional existence hypotheses in infinite dimension.
On real by matrices with , split into traceless symmetric matrices, skew-symmetric matrices and scalar matrices. These summands are orthogonal for the displayed symmetric bilinear form. The form is positive on the first summand, negative on the second and negative on the scalar identity direction. Its inertia of a bilinear form is , its rank is and its signature is . Indeed , and .
For a field of characteristic different from two, is the group of nonsingular symmetric bilinear forms modulo metabolic forms, with orthogonal sum as addition. A metabolic form has a half-dimensional totally isotropic subspace. Such a form is equivalent to a sum of hyperbolic planes, hence represents zero.
A bilinear form is nondegenerate when its left radical and right radical are both zero: every nonzero vector can be detected by some pairing, whichever input slot it occupies. On a finite-dimensional vector space, either condition implies the other, and the following tests are equivalent:Here is the matrix of a bilinear form, and is the dual space. The linear map has matrix in the chosen basis and its dual basis, so its kernel is the right radical. The map has matrix . An invertible matrix has zero kernel on both sides, proving the finite-dimensional equivalence. In infinite dimensions, zero left radical and right radical imply these maps are injective, but do not generally make them surjective.[ref]
For the real symmetric bilinear form , the determinant is . Its isotropic vector has zero self-pairing but pairs to with , so it is detected. The alternating bilinear form with matrix has determinant and detects every nonzero vector even though all self-pairings vanish. Neither zero self-pairings nor the absence of positive definiteness implies degeneracy.
Nondegeneracy is useful because it turns a linear functional into a unique vector. For , the linear functional is ; solving for that representing vector amounts to solving an invertible system of linear equations. The analogous identification underlies bilinear orthogonal complements and the dual isomorphisms induced by a nondegenerate pairing.
A bilinear form with zero left and right radicals induces injective linear maps and . Finite dimensions force , so both maps are isomorphisms. For any other bilinear form , composing its maps to the dual spaces with these inverse isomorphisms gives unique endomorphisms with . In bases with invertible pairing matrix and coefficient matrix , and .
A symplectic vector space is a vector space equipped with a nondegenerate bilinear form that is an alternating bilinear form: for every vector . This implies . When the characteristic is two, that latter equation alone does not imply the alternating condition. A symplectic vector space of finite dimension has even dimension: splitting off a hyperbolic pair leaves a smaller nondegenerate bilinear form, and repeating gives a decomposition into two-dimensional planes.
For a finite-dimensional symplectic vector space, the symplectic adjoint of a linear map is the unique linear map satisfying the displayed identity. Existence and uniqueness follow because the nondegenerate bilinear form identifies the vector space with its dual space. If has matrix in a basis, then . Thus and , and membership in the symplectic Lie algebra is equivalent to . This operation is linear over the ground field; it does not involve complex conjugation. It preserves diagonalizability and the property of being a nilpotent linear map, since it is conjugate to matrix transpose.
A linear map is symplectic when it pulls back the target symplectic form to the source form. Nondegenerate bilinear form makes such a map injective. In equal finite dimensions it is an isomorphism. The automorphisms form the symplectic group and preserve the symplectic orientation on the ambient space and on every symplectic subspace.
A subspace of a symplectic vector space is symplectic if the restricted symplectic form is nondegenerate. It has a symplectic orthogonal complement and the ambient space is the direct sum of those two subspaces.
Let be a symplectic orthogonal complement splitting into two symplectic subspaces of dimension two. In symplectic bases, the graph of a function pulls back the symplectic form to . It is a symplectic subspace exactly when . Its symplectic orientation agrees with the orientation transported from exactly when . When , the transverse oriented pair has negative intersection sign, whereas two distinct complex lines in a compatible complex two-space have positive intersection sign.
If preserves a nondegenerate bilinear form that is alternating and satisfies on a finite-dimensional vector space over a field of characteristic different from two, thenThe two eigenspaces are orthogonal for , since . Each restricted form is nondegenerate: a vector annihilating its own eigenspace also annihilates the other and hence all of . Both dimensions are even, say and . Consequently as an integer obtained from the eigenspace dimensions. Over the real numbers this gives the congruence .
The symplectic orthogonal complement of a subspace is . The nondegenerate bilinear form gives . An isotropic subspace of a symplectic vector space satisfies ; a Lagrangian subspace satisfies equality.
A subspace of a symplectic vector space is isotropic when . It has at most half the dimension of ; equality makes it a Lagrangian subspace. This use of isotropic concerns an alternating bilinear form, rather than an isotropic quadratic form.
A symplectic basis organizes a nondegenerate alternating bilinear form into independent pairs. Let be a finite-dimensional vector space over a field , with a nondegenerate bilinear form satisfying for every vector . Its dimension is even, say , and a symplectic basis is an ordered basis such thatHere is the Kronecker delta. Each is a hyperbolic pair; different pairs have zero mutual pairing. These conventions apply in every characteristic. In characteristic two, , but the condition is still essential: a symmetric bilinear form need not be an alternating bilinear form. The existence theorem and the characteristic caveat are given in Bilinear Forms by Keith Conrad (Keith Conrad, Bilinear Forms, §1, Theorem 1.6; §5, Theorems 5.1 and 5.4 and Definition 5.3).
The benefit is a common coordinate language for every symplectic vector space of the same finite dimension over the same field. The span of all , and separately of all , is a Lagrangian subspace; each paired span is a symplectic subspace. In Hamiltonian mechanics, the corresponding pairing of position and momentum coordinates describes phase space and canonical transformations. On a symplectic manifold, a symplectic basis describes one tangent space; Darboux coordinates additionally describe a whole local neighborhood.[ref]
Symplectic Geometry. §1.1, pp. 82–83: paired bases and Lagrangian spans; §1.5, pp. 90–91: Darboux coordinates
Write vectors in a symplectic basis as and . Their coordinate vectors and the matrix of a bilinear form areHere is the identity matrix, and denotes transpose. The ordering matters: interleaving the basis as instead gives a block diagonal matrix with blocks . Some conventions reverse every , giving instead. Always check the displayed pairing convention.[ref]
Symplectic Geometry. §1.1, p. 83: e-then-f basis and its block matrix; the coordinate formula follows by bilinearity
Over the real numbers, each summand is the signed area of a parallelogram in the coordinate plane. For and , the two signed areas are and , so although the vectors are linearly independent. The cancellation concerns the symplectic form; it does not assert that their dot product vanishes. Over a general field, the same determinant formula is algebraic, without a signed geometric interpretation.
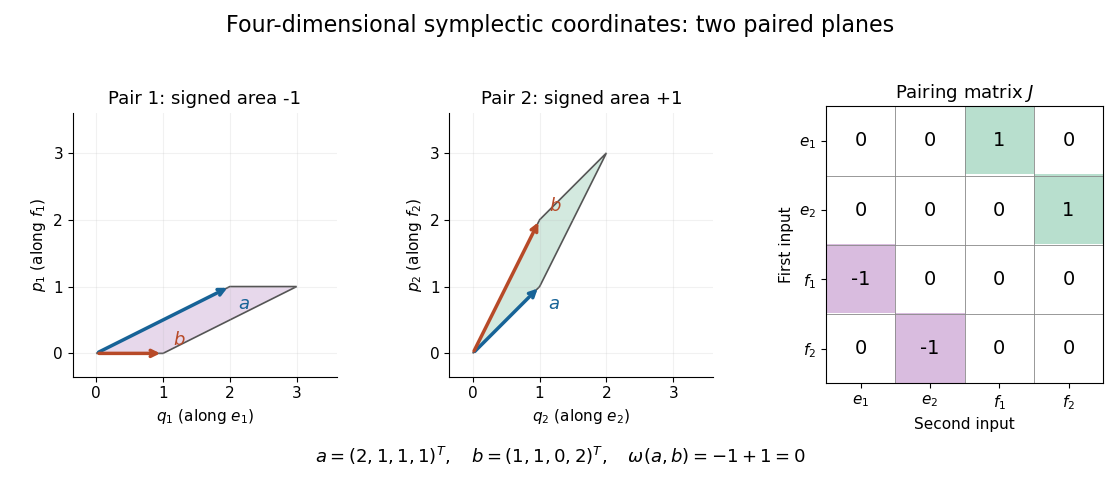
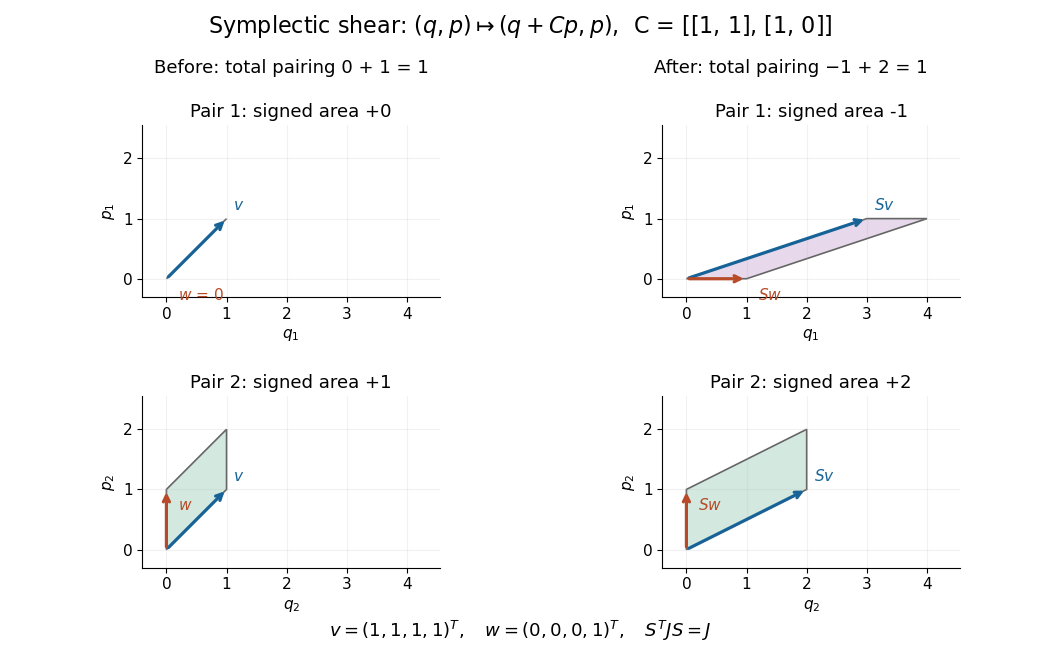
On , use the standard basis and the alternating bilinear form with matrix above for . A second symplectic basis isFor instance, , while and the cross-pairings vanish. The change of basis matrix, whose columns are these new basis vectors in , isThe symmetric matrix makes , so is a symplectic matrix. Explicitly, multiplying the blocks gives a lower-right block ; the other blocks agree with . For a fixed vector, change of basis means , henceTheir symplectic form gives in , and in . The separate coordinate-plane contributions change, but their sum does not.
The same matrix also represents an active symplectic linear map: keeping one basis fixed, it sends to . The following diagram shows this active interpretation over the real numbers. Its preserved total pairing is precisely the test used for linear canonical transformations.
Construct a symplectic basis two vectors at a time. Choose ; the nondegenerate bilinear form supplies with , and set . For any vector , remove its paired components byThen . Thus, for , the symplectic orthogonal complement gives a direct sum ; its restricted bilinear form remains nondegenerate. Repeat there until no vectors remain, then put all before all . This proves even dimension and existence together. Only the nonzero pairing is divided out, so the construction also works in characteristic two. The pair-splitting argument is described in Bilinear Forms by Keith Conrad (Keith Conrad, Bilinear Forms, §5, proof of Theorem 5.1 and Theorem 5.4).
If is a nondegenerate bilinear form on a finite-dimensional vector space and is any bilinear form, there is a unique linear map such thatThe right radical of is .
A real bilinear form on a normed vector space is coercive when there is one constant such thatThe lower bound uniformly controls every direction in the chosen norm. Unlike the upper bound defining a bounded bilinear form, it forces positive diagonal values at every nonzero vector. No symmetry is assumed. For complex Hilbert spaces, the usual analogue uses a sesquilinear form and ; it is not the same assertion for a complex bilinear form.
A concrete bounded and coercive example on , with the Euclidean norm, isIts quadratic form isThe best lower constant is , attained at . Nevertheless, and , so coercivity does not imply a symmetric bilinear form. The symmetric part of a matrix determines , while the skew-symmetric matrix part changes mixed pairings without changing . This is the symmetric and alternating parts of a bilinear form decomposition.[ref]
For the upper constant, direct multiplication gives . Its eigenvalues are , so the optimal upper constant, the spectral norm, is . The two constants answer different questions: how large a mixed pairing can be, and how small a self-pairing can be relative to squared norm.
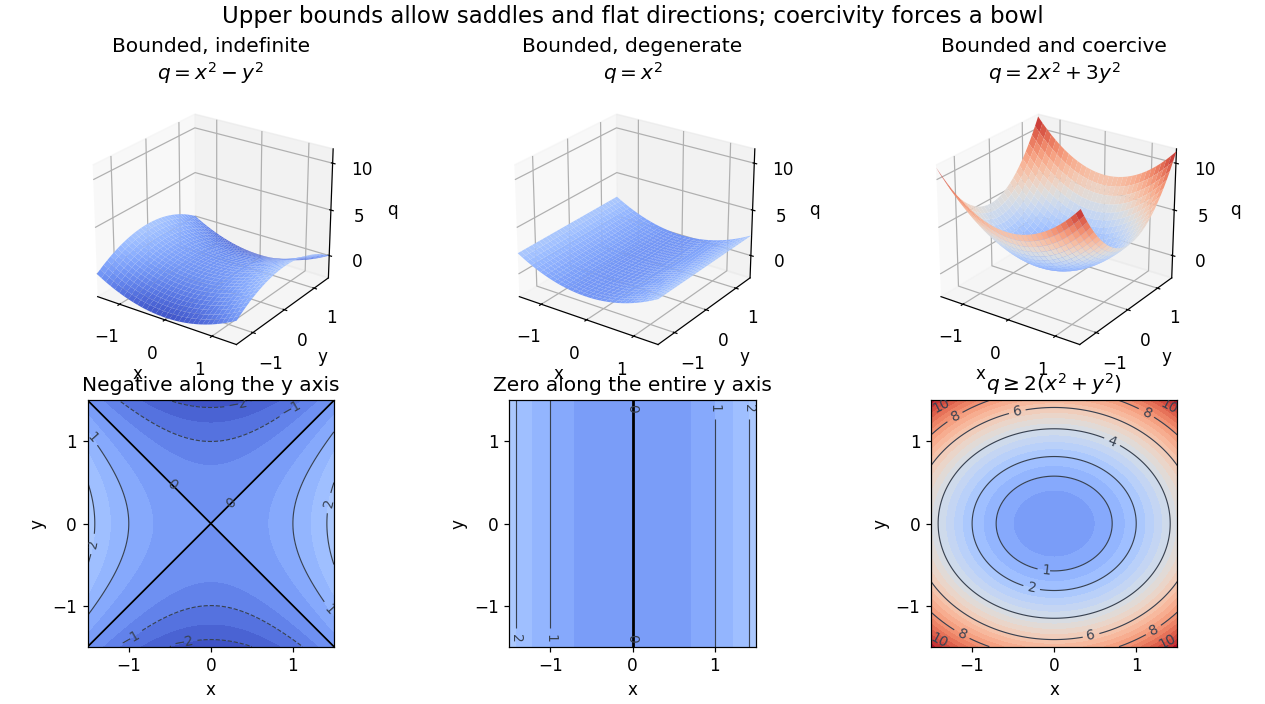
Bounded saddle and flat-direction quadratic forms contrasted with a uniformly coercive bowl
. Details. The plotted quadratic forms show the mechanism: descends in one direction, leaves one direction uncontrolled, and controls both. These are self-pairings; their level sets cannot reveal the skew-symmetric matrix part. Calling a quadratic energy here refers to this diagnostic quantity, not to a claim that a nonsymmetric equation comes from minimizing an energy functional.
On a real finite-dimensional vector space with any norm, strict positivity for every nonzero does imply coercivity. Indeed the quadratic form is continuous, and its positive minimum on the compact unit sphere supplies . If is also a symmetric bilinear form, this is positive definiteness. For general , it is the symmetric and alternating parts of a bilinear form decomposition that isolates the positive part. Switching between equivalent norms preserves coercivity, but usually changes its constant.
The infinite-dimensional vector space distinction is explicit on the real l2 sequence space:The Cauchy-Schwarz inequality gives boundedness with , and for every nonzero vector. But with , so no positive works. On the span of , the best lower constant is : each finite restriction is coercive, but the control disappears as grows. Strict positivity is therefore weaker than a uniform lower bound.
The practical payoff is a stability estimate for a weak formulation. Assume is a real Hilbert space, is both a bounded bilinear form and a coercive bilinear form, and the load is a bounded linear functional. The Lax-Milgram theorem gives a unique satisfying for all , including nonsymmetric .[ref]
Introduction to Finite Element Methods by Christian Clason. §2.2, Theorem 2.7, pp. 20–21, equation (2.9): hypotheses, unique solvability and load bound
The dual norm measures load size. Testing with gives the short energy estimateFor the bound holds directly; otherwise divide by . Subtracting the equations for two loads and using the same argument gives . Thus a positive lower constant limits the response to load errors. The upper bound and completeness of the Hilbert space enter the existence theorem; the estimate itself uses the lower bound and the load's dual norm.For the displayed matrix , take . Then for every means , not , with this ordering of the bilinear form. Since ,For , the exact response is and . For , it is , with norm . The actual maximal amplification is the operator norm : the coercivity estimate is valid but need not be sharp for a nonsymmetric bilinear form.
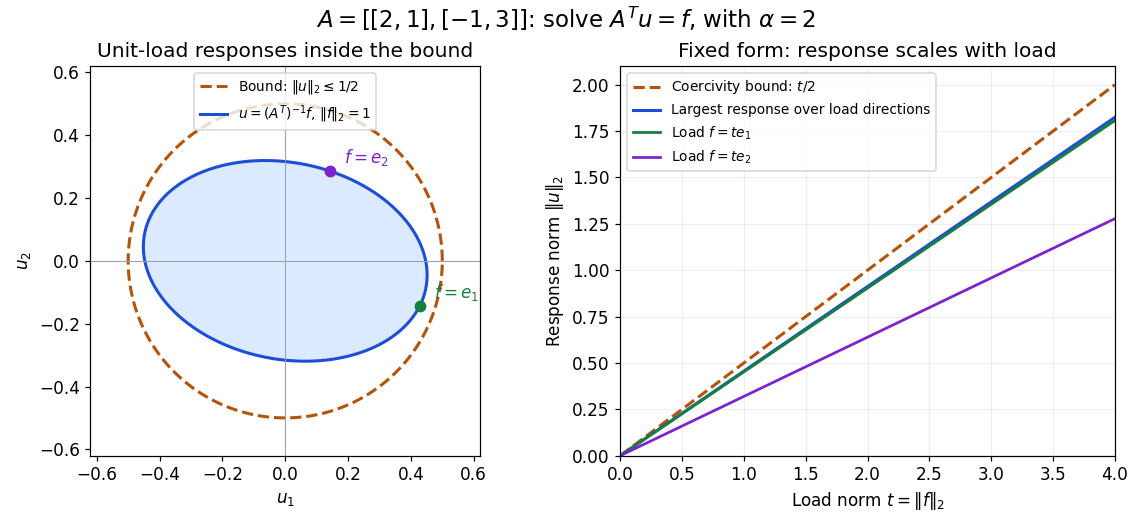
Solutions for unit loads lie inside the coercivity bound, and response grows at most linearly with load norm
. Details. Consider on real functions with , where . The pointwise estimate in the Endpoint Poincaré inequality gives with . If , then . Thus the form is a coercive bilinear form even though the potential can change sign. For on , , yielding the explicit constant .
A bilinear form is degenerate if some nonzero vector pairs to zero with every vector on at least one side. For a symmetric bilinear form or an alternating bilinear form, this says its radical of a bilinear form contains a nonzero vector. On a finite-dimensional vector space, it is equivalent to a singular matrix of a bilinear form, or .
For , . The nonzero vector is invisible to every pairing, and changing never changes . The quadratic form therefore has two parallel lines as its unit level set. This is a lost direction, a stronger condition than being an isotropic vector: with , but .
For a symmetric bilinear form or an alternating bilinear form, the radical is the linear subspaceThese vectors are invisible to all pairings, and the bilinear form is nondegenerate exactly when this linear subspace is . In coordinates, for both kinds of bilinear form, since or . Thus has radical of a bilinear form .
Passing to the quotient vector space removes precisely the invisible directions. The rule is well-defined because adding a vector in the radical of a bilinear form to either input changes no pairing, and the resulting bilinear form is nondegenerate. For , this quotient vector space retains just the direction and its form is ordinary multiplication.[ref]
https://www.math.ucla.edu/~rse/oldbook/Kniga.pdf. Elman, Karpenko and Merkurjev, The Algebraic and Geometric Theory of Quadratic Forms, §1: radical and nondegenerate quotient
For a general bilinear form, distinguish the left radical of a bilinear form from the right radical of a bilinear form; they can be different linear subspaces even though their dimensions agree in finite dimensions.
The left radical is . If is the matrix of a bilinear form, this condition is , so its coordinate vectors form . For , the bilinear form has left radical .
The right radical is . If is the matrix of a bilinear form, this condition is . For from the left radical example, the right radical is . The left radical and right radical differ here because the bilinear form is neither symmetric nor alternating. For a symmetric bilinear form or an alternating bilinear form, reversing a zero pairing preserves zero and the two linear subspaces coincide.
A bilinear form on a real normed vector space is bounded when one constant satisfiesThis is an upper bound on the magnitude of every pairing. It says nothing about the sign of and does not require a symmetric bilinear form. The chosen norm is part of the hypothesis. Boundedness is equivalent to joint continuity, as shown by the boundedness criterion for a bilinear form.[ref]
For example, on with the Euclidean norm, the bilinear formsboth satisfy the upper bound with , by the Cauchy-Schwarz inequality. Yet their quadratic forms are and : the former takes negative values and the latter vanishes at the nonzero vector . Thus neither is a coercive bilinear form. The latter is also a degenerate bilinear form, whereas is nondegenerate. Boundedness controls size, not positivity or loss of directions.
Every bilinear form on a real or complex finite-dimensional vector space equipped with any norm is bounded. In coordinates, write using its matrix of a bilinear form. The Cauchy-Schwarz inequality gives , with the spectral norm; finite-dimensional equivalence of norms transfers this to the chosen norm. The conclusion concerns each fixed norm and fixed bilinear form: it does not supply a single constant for an arbitrary family of matrices or changing dimensions.
On an infinite-dimensional vector space, the upper bound is an additional condition. Equip the finitely supported sequences with the norm inherited from the l2 sequence space and setEach pairing is a finite sum, so this is a well-defined bilinear form. For the basis vector , however, and ; no finite works. It is even a coercive bilinear form with , since . Consequently coercivity alone does not imply boundedness on a normed vector space. This example uses , which is not a Hilbert space; it does not define this pairing on all of the l2 sequence space.
A bounded bilinear form defines a bounded linear operator by , where is the continuous dual space. Its operator norm is the smallest admissible :This converts an upper bound for pairings into an upper bound for a linear map taking an unknown vector to a linear functional.
Let be a bounded real measurable coefficient on an open set. Nonnegativity of clearly makes its gradient form nonnegative. Conversely, if on a set of positive measure, choose an interior Lebesgue point where . For a nonconstant compactly supported smooth function , set . Change variables and use the Lebesgue differentiation theorem to obtain , a contradiction. Thus the linear operator represented by is monotone exactly when almost everywhere.
For a finite real scalar matrix and unit vectors in a real Hilbert space, , with a universal constant. One valid bound is . Expand using odd tensor powers with coefficient magnitudes summing to , then apply the Gaussian sign identity . Taking converts the expectation back to the original inner product. Complex scalars admit a universal bound twice this real bound by separating real and imaginary parts.
Every bounded linear operator into a Hilbert space is an absolutely summing operator, with . For simple functions on a common disjoint partition, apply the Grothendieck inequality to the vectors and norming vectors of the images. The scalar sign or phase supremum is the weak 1-norm of the family. Approximation by simple functions proves the general result.
If the closed span of the Rademacher functions were a complemented subspace of , compose a projection with the inverse of its l2 sequence space parametrization. The Grothendieck theorem for L1 to Hilbert operators would make this map an absolutely summing operator. Its composition with the parametrization would make the identity on the infinite-dimensional l2 sequence space absolutely summing, contradicting its coordinate-vector test.
A bilinear form on a normed vector space is continuous exactly when it is bounded. For the nontrivial direction, continuity at gives such that whenever and ; scaling nonzero into these balls gives .
A bilinear form is alternating if for every vector . Expanding gives , hence . If the characteristic is not two, the converse follows from by dividing by two. In characteristic two, the relation is just symmetry and does not force zero self-pairings: on has .[ref]
https://webspace.maths.qmul.ac.uk/p.j.cameron/notes/linalg.pdf. Peter J. Cameron, Notes on Linear Algebra, §§9.1–9.2: alternating forms in arbitrary characteristic
The matrixgives an alternating bilinear form over every field. Over the real numbers, its value is the signed area of the parallelogram with sides : , and swapping the sides gives . Every self-pairing is zero, yet , so this bilinear form is nondegenerate. Directly, pairing with gives , and pairing it with gives ; both vanish only when .
In characteristic different from two, a skew-symmetric matrix of odd integer size has zero determinant, since . Thus an alternating bilinear form on a finite odd-dimensional vector space is a degenerate bilinear form. The stronger statement that the rank of an alternating bilinear form is even holds in all characteristics: splitting off a two-dimensional block with matrix repeatedly proves it. A nondegenerate alternating bilinear form defines a symplectic vector space, the linear setting for signed area rather than squared length.
For a bilinear form on a finite-dimensional vector space, the displayed right bilinear orthogonal complement is a subspace. Nondegeneracy identifies the ambient space with its dual and gives . If the form is symmetric or alternating, orthogonality is reciprocal and . For a general nonsymmetric form, left and right complements must be distinguished. A restricted symmetric or alternating form has radical of a bilinear form ; quotienting by that radical of a bilinear form gives a nondegenerate induced form.
For a bilinear form on a finite-dimensional vector space , let send to . Under the bidual evaluation map, is the annihilator of a vector subspace , so . The rank-nullity theorem on now gives the displayed equality. In particular the sum of dimensions is at least . If , the dimension formula for a sum of subspaces forces . The exact formula records the extra dimensions contributed by the left radical , and does not assume an inner product.
A linear bijection between spaces carrying compatible bilinear forms, Hermitian forms or quadratic forms is an isometry of a space with a form when it preserves the specified form. Preserving the polar form alone need not preserve a quadratic form in characteristic two. Subspaces may have degenerate restricted forms even when the ambient form is nonsingular.
A vector is anisotropic for a quadratic form if , and for a Hermitian form if . The complementary zero-value condition is isotropy. For a symmetric bilinear form in odd characteristic of a field, this agrees with the associated quadratic form. A nondegenerate alternating bilinear form has all self-pairings zero, so nondegeneracy must not be confused with the existence of anisotropic vectors.
An isometry of a space with a form between subspaces of a finite-dimensional nonsingular classical space extends to an ambient isometry. This includes alternating bilinear forms in all characteristics, symmetric bilinear forms in characteristic different from two, Hermitian forms with nontrivial involution, and quadratic forms with nonsingular polar form. No nonsingularity of the restricted subspace is required. Bare nonalternating symmetric bilinear forms in characteristic two require additional hypotheses and must not be confused with quadratic spaces.
The inertia of a real symmetric bilinear form is the triple giving the numbers of positive, negative, and zero squares in a diagonalization. Sylvester's law of inertia makes it independent of the chosen basis.
For a real symmetric bilinear form, let and be the dimensions of its positive and negative diagonal subspaces. This pair gives the first two components of the inertia of a bilinear form and is independent of basis by the Sylvester's law of inertia. For a nondegenerate form their sum is the full dimension; otherwise the nullity is an additional invariant. Another convention calls the difference the signature of a quadratic form. The pair convention describes the positive and negative harmonic spaces of the real de Rham intersection form in dimension four.
A sesquilinear form on a complex vector space is a map which, with the convention used throughout this article, is a linear map in its first argument and a conjugate-linear map in its second. For vectors and complex numbers , the defining identities areThe bars denote complex conjugation. No symmetry or positivity is required. Some authors choose the opposite convention; every formula here keeps the first argument linear.[ref]
For a basis of a finite-dimensional vector space, write , , and . Expanding by the two identities givesEvery complex matrix gives a sesquilinear form this way. The superscript means transpose, not conjugate transpose. Equivalently, the scalar is , where . This is the convention used for the matrix of a Hermitian form when symmetry is imposed. The coordinate formula follows directly by expanding the basis coefficients.[ref]
https://sites.math.washington.edu/~burke/crs/554/lectures/b-lecture4.pdf. Burke, Linear Analysis, Lecture 4, coordinate expansion for sesquilinear forms
For a concrete example on , let . Its matrix is : but , so it is not a Hermitian form. Also , so even real diagonal values cannot be assumed for an arbitrary sesquilinear form. By comparison, the bilinear form satisfies and has ; it cannot supply positive squared lengths on this complex vector space.
The effect of changing the complex argument of a multiplier is particularly revealing. For real numbers , sesquilinear forms satisfyThus a common change of complex argument cancels from the diagonal, whereas the two arguments rotate the output in opposite directions. Conjugating one argument is what replaces the scaling of a bilinear form by the nonnegative scaling needed for a Hermitian inner product. This mechanism also works in function spaces: for complex continuous functions on , obeys the same identities, letting integration measure overlap rather than merely multiply coefficients.
For a Hermitian form or a Hermitian form over a quadratic finite field, the displayed subspace is the orthogonal complement of . If the form restricts nondegenerately to a finite-dimensional , its invertible Gram matrix supplies, for each , a unique with . Consequently . When the form on is nondegenerate, its restriction to is too: a radical vector there is orthogonal to both summands and hence is zero.
A Hermitian form is a sesquilinear form on a complex vector space satisfying conjugate symmetry,Hence is a real number for every vector. In a basis, the matrix of a Hermitian form has and obeys , equivalently : it is a Hermitian matrix. The coordinate rule remains . Conjugate symmetry does not imply positivity.[ref]
https://sites.math.washington.edu/~burke/crs/554/lectures/b-lecture4.pdf. Burke, Linear Analysis, Lecture 4, Hermitian symmetry
The diagonal contains more information than might be expected. For any complex sesquilinear form , put . Expanding four expressions gives the complex polarization identity in the linear-first convention:This is an algebraic identity, with no positivity assumption. If every is real, interchanging preserves the first difference and negates the second: use for . The identity then gives . Thus a complex sesquilinear form is a Hermitian form if and only if all its diagonal values are real. Testing only the basis vectors is insufficient: the off-diagonal example in sesquilinear form has zero diagonal entries in its matrix but a nonreal value at .
Consider the indefinite Hermitian formIts values at are . Moreover and are nonzero isotropic vectors: , yet . These vectors do not belong to the radical of a Hermitian form, and the usual Cauchy-Schwarz inequality would incorrectly require . An indefinite Hermitian form records signed geometry rather than defining a norm by .
There is a separate boundary case: is a positive semidefinite Hermitian form, since , but . Its radical of a Hermitian form is the entire second coordinate line. Positive definiteness is exactly the additional condition in a Hermitian inner product. The three examples below show why these distinctions matter: on the real slice , has an ellipse as its unit level, has hyperbolas, and has two parallel lines. These are slices of the complex examples, not drawings of their full four-dimensional domains.
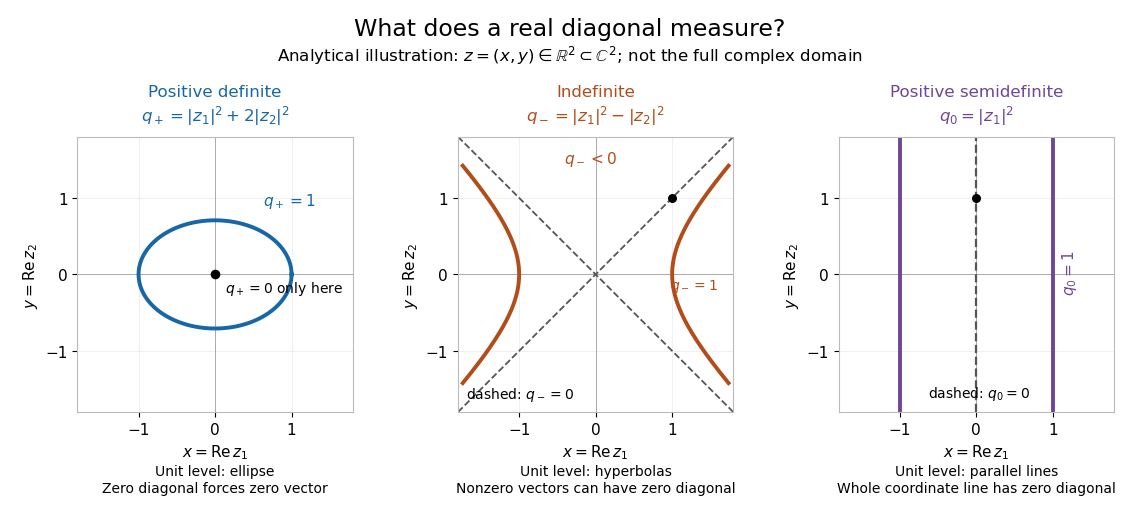
Analytical illustration: real slices of positive definite, indefinite, and positive semidefinite Hermitian forms
. Details. A Hermitian inner product is a Hermitian form on a complex vector space which has positive definiteness: for every nonzero vector . It is precisely a complex inner product. Only with this definiteness condition doesdefine a norm rather than a seminorm or an expression that may not be real. The standard Hermitian inner product on is ; positive weights give , with squared norm .[ref]
https://linear.axler.net/InnerProduct.pdf. Sheldon Axler, Linear Algebra Done Right, third edition, §6.A, definitions 6.3 and 6.9 and examples 6.4
A Hermitian inner product need not have a real matrix. For instance, with the linear-first coordinate convention,The last expression proves positive definiteness without a lengthy calculation of eigenvalues. For it gives , while for it gives . These unequal values expose why a silent switch to would change this particular Hermitian inner product: with these same entries it gives at . All entries must keep their roles from the matrix of a Hermitian form.
The Cauchy-Schwarz inequality for a Hermitian inner product statesEquality holds exactly when are linearly dependent, including when either is zero. For a nonzero , outline the proof by setting and . Then , and the Pythagorean theorem givesNonnegativity proves the inequality, while positive definiteness makes equality equivalent to . The scalar has no extra conjugate because the first argument is linear.[ref]
https://linear.axler.net/InnerProduct.pdf. Axler, Linear Algebra Done Right, third edition, orthogonal decomposition 6.14 and Cauchy-Schwarz inequality 6.15
The Cauchy-Schwarz inequality also holds for a positive semidefinite Hermitian form, but equality need not imply linear dependence: for , the independent vectors and give . Equality then describes dependence after passing to the quotient vector space by the radical of a Hermitian form. The indefinite Hermitian form in Hermitian form shows that conjugate symmetry alone does not even guarantee the inequality.
For a worked orthogonal projection, take , and . Then , and , with and for the squared norms. The residual is perpendicular in this Hermitian inner product even though its ordinary real dot product with is . For complex , the same orthogonal projection uses ; rotating multiplies by , while rotating multiplies by . This combines geometric decomposition with sensitivity to the relative complex arguments of the multipliers.
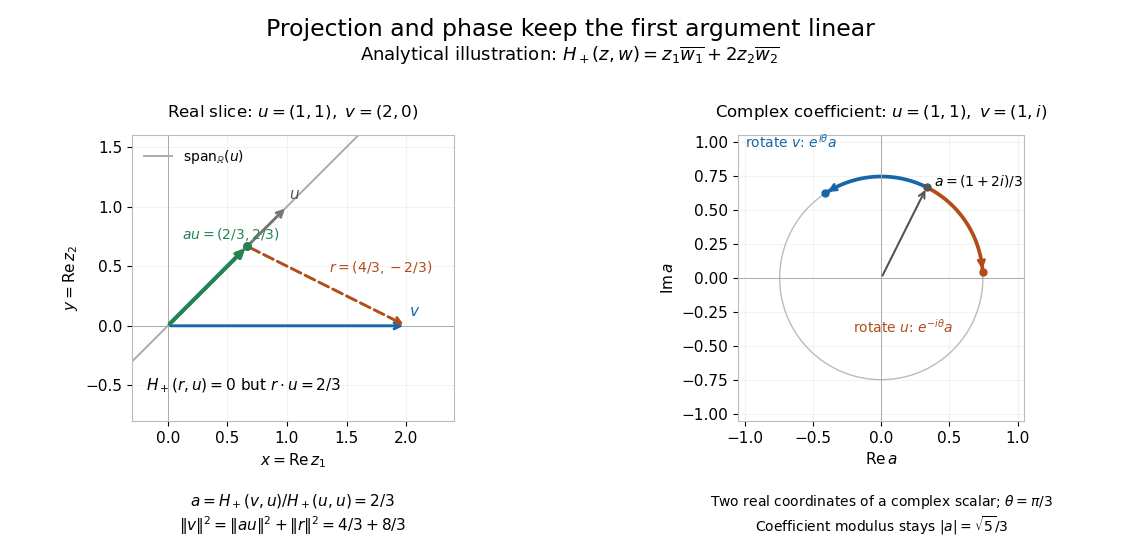
Analytical illustration: weighted orthogonal projection on a real slice and opposite changes of complex argument of its projection coefficient
. Details. A Hermitian inner product therefore supplies more than a positive diagonal: orthogonality, orthogonal projection onto a span, and the triangle inequality for its norm make approximation and distance meaningful. For the function space of complex continuous functions on , has positive definiteness, because a nonzero continuous function has positive modulus on a small interval. The same construction turns overlap under integration into lengths and best approximation in finite-dimensional vector subspaces.
Each basis of a finite-dimensional complex vector space determines a unique complex inner product making that basis orthonormal. In coordinates it is , with the first argument linear. The formula is sesquilinear, has conjugate symmetry, and satisfies , which is positive unless . Expanding any inner product in the given basis proves uniqueness. Its codomain is the complex numbers; only its diagonal values are necessarily real. The resulting identification with the dual space is conjugate-linear, not complex-linear.
Exchanging the arguments of a Hermitian inner product takes its complex conjugate. This property, together with sesquilinearity and positive definiteness, distinguishes a complex inner product from a general bilinear pairing.
Over the finite field , a sesquilinear form relative to is linear in its first argument and conjugate-linear in its second. It is Hermitian when . Its diagonal values belong to ; it is nondegenerate when for every forces . This definition applies in characteristic two as well.
In a two-dimensional nondegenerate Hermitian form over a quadratic finite field, choose an orthonormal basis and with . Then is an isotropic vector. Choose with , and choose with . The vector satisfies and . Thus give the displayed matrix, including in characteristic two. Iterating on nondegenerate orthogonal complement for a sesquilinear form leaves only a unit-norm line in odd dimension.
A nondegenerate Hermitian form over a quadratic finite field has an orthonormal basis. If all diagonal values vanished, evaluating would give for every , contradicting quadratic finite-field norm and trace surjectivity and nondegeneracy. Thus some has nonzero norm; rescaling using the field norm makes it one. Its orthogonal complement for a sesquilinear form is nondegenerate, so induction completes the basis.
Integrate a polynomial times the conjugate of another over the product of unit circles, with normalized product angular measure. Fourier orthogonality makes the monomials an orthonormal basis of the polynomial vector space. The Hermitian form is positive definite because the squared norm is the sum of squared absolute values of the finitely many coefficients. No completion or infinite series is needed to obtain this algebraic basis.
The radical of a Hermitian form is the vector subspace orthogonal to the entire space. The form descends to the quotient vector space by its radical: adding a radical vector to either argument does not change the value. For a positive semidefinite Hermitian form, the Cauchy-Schwarz inequality identifies this radical with its zero-norm vectors, so the quotient form is positive definite. This conclusion does not hold for a general indefinite Hermitian form: a zero-norm vector need not belong to its radical.
A Hermitian form is positive semidefinite when for every vector. It need not define an inner product, because a nonzero vector may have zero squared norm. The Cauchy-Schwarz inequality still holds: applying nonnegativity to and minimizing the quadratic expression in gives when ; when , varying forces . Thus its zero-norm vectors are exactly the radical of a Hermitian form. Quotienting this radical of a Hermitian form gives a positive inner product; taking its Hilbert space completion then gives a Hilbert space. This is the final positivity step in the Gupta-Bleuler null-state quotient.
An indefinite Hermitian form takes both positive and negative values on for nonzero vectors. For example, is indefinite. It is not a positive inner product defining a Hilbert space, and a nonzero vector can have zero norm without being orthogonal to all vectors. A positive semidefinite restricted form becomes a positive inner product only after quotienting its radical of a Hermitian form.
For a basis , the matrix of a Hermitian form has entries . With the convention that is linear in its first argument, coordinate columns satisfy .
A vector space over a field is a set equipped with vector addition and scalar multiplication satisfying the vector space axioms. Its vectors can represent directed displacements, lists of measurements, polynomials, or entire functions. The common structure is that adding two elements and multiplying an element by a scalar remain meaningful operations inside the same space.
For example, uses coordinatewise addition and scaling. Withwe have . Moving twice along and once along reaches the same vector as five horizontal and four vertical steps. The two descriptions refer to different bases of the same space. A basis makes such descriptions unique; a spanning set makes them possible.
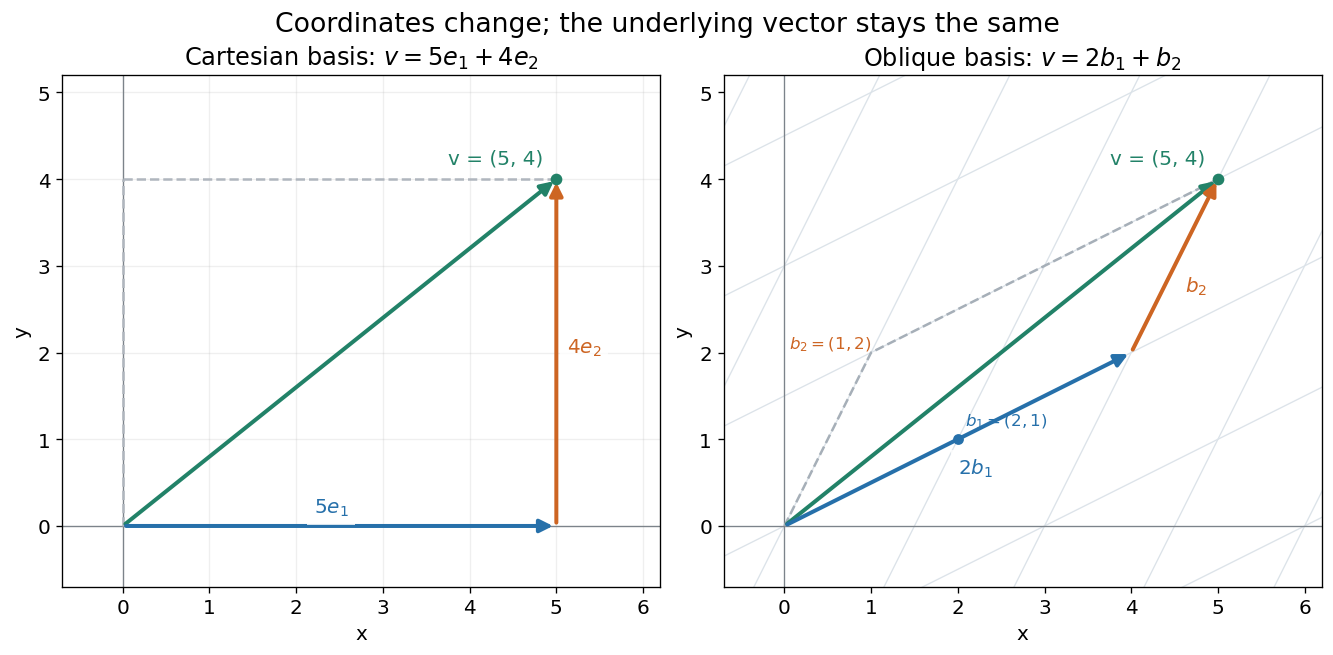
The space of real polynomials of degree at most two has basis : the polynomial is the linear combination with coordinates . The zero vector here is the zero polynomial, and addition combines coefficients. A derivative is a linear map on this space; its matrix records how it acts on the three basis vectors. The same coordinate machinery therefore handles both geometric motion and operations on functions.
The choice of field matters. The complex numbers form a one-dimensional vector space over with basis , but a two-dimensional vector space over with basis . The question "how many independent directions?" has an answer only after the allowed scalars are specified. Likewise, polynomials of degree exactly two do not form a vector space: subtraction can remove the leading term, and the zero polynomial is absent.
The usefulness of the abstraction is that a linear map is determined by its values on a basis. Once those images are known, linear combinations give its action on every vector. The rank-nullity theorem relates the number of attainable outputs to the number of invisible input directions, while change of basis lets us choose coordinates suited to the problem. Eigenvectors, for example, choose directions on which repeated application of a linear operator becomes scalar multiplication.
A historical source is Hermann Grassmann's Die lineale Ausdehnungslehre (1844). Its full title advertises applications to other branches of mathematics, statics, mechanics, magnetism and crystallography; the original edition is digitized by ETH-Bibliothek. This gives an early setting for treating geometric quantities algebraically across different applications, rather than attributing the modern axiom list to that title alone.[ref]
https://www.e-rara.ch/zut/content/titleinfo/1169335. Grassmann, Die lineale Ausdehnungslehre, Leipzig, 1844; ETH-Bibliothek Rar 5128
For a nonzero vector space with an infinite field or infinite basis, cardinality is the displayed maximum, since vectors are finite linear combinations of basis vectors. Over a finite field, infinite underlying size forces infinite dimension. Over a countably infinite field, every positive finite dimension is already countably infinite. The theory of infinite underlying spaces is therefore categorical in every infinite cardinal for a finite field, but only in uncountable cardinals for a countably infinite field.
A module over a division ring has the usual basis and linear independence theory of a vector space, with the side of scalar multiplication specified. For a right module, a finite relation has the form . Every nonzero endomorphism of a one-dimensional right module is invertible. If is a simple module on the left over , evaluation makes it a right vector space over the opposite ring , a division ring by Schur's lemma. This is the scalar structure used by the Jacobson density theorem.
The complexification of a real vector space allows complex scalar coefficients while preserving its real linear relations. It can be constructed as the tensor product , or as formal sums with . A real basis of becomes a complex basis of , so its complex dimension equals the original real dimension. Every real linear map extends uniquely by complex linearity. In particular a real representation extends by viewing its real matrices as complex matrices. Complexifying the realification of a complex representation produces the original complex representation together with its complex conjugate; the coordinate change exhibits the two blocks.
Addition makes an Abelian group: for all , and , there is a zero vector , and every has an additive inverse . Scalar multiplication satisfies, for ,Both operations take values in . These requirements make manipulating linear combinations independent of how sums are grouped or expanded.
A sequence space is a vector space of scalar sequences, closed under coordinatewise addition and scalar multiplication. Examples include the l-p sequence space, the l-infinity sequence space and spaces of convergent sequences.
On , is a norm, bounded above by . The partial-sum map is an isometric linear embedding into the space of convergent sequences with the supremum norm. Its range contains every eventually constant sequence: take successive differences of such a sequence to obtain a finitely supported element of . These sequences are dense in , so the completion of a normed space is .
The range is proper: partial sums of the alternating harmonic series converge but their successive differences do not belong to . The finite truncations of these differences are -Cauchy and cannot have a limit in . Thus this normed version of is incomplete, despite the completeness of its usual norm.
The zero vector of a vector space is its additive identity: for every vector . It is unique, because if is another such identity then . Distributivity gives , so after cancellation. In a coordinate vector space it has every coordinate zero.
A vector space with scalar field is equivalently a torsion-free divisible Abelian group. An embedding of such groups automatically respects rational scalar multiplication because solutions to are unique.
For complex vector spaces, an antilinear map satisfies . It is linear over the real numbers and conjugates complex scalar multiplication. This differs from two conjugate linear operators, which are related by similarity rather than conjugate-linearity.
An antilinear endomorphism with square equips a complex vector space with a quaternionic structure: complex multiplication supplies the quaternionic generator and supplies , satisfying . Such a space has even complex dimension. There is no invariant complex line, because would imply . In dimension four the invariant complex two-planes are quaternionic lines, forming . This is the Euclidean reality structure on twistor space used in twistor theory.
An antiunitary operator between complex Hilbert spaces is a surjective antilinear map satisfying the displayed inner product identity. It preserves norms but conjugates scalars. In a chosen orthonormal basis it is , with a unitary operator and coefficientwise complex conjugation. Conversely any such is antiunitary. Antilinearity by itself does not preserve norms.
A vector space over the field of complex numbers. A complex-linear map preserves addition and multiplication by complex scalars.
For real vectors of equal length and equal sum, write when for every proper initial segment; the downward arrow means decreasing rearrangement. Majorization compares how unevenly a fixed total is distributed. The uniform probability vector is majorized by every probability vector, while majorizes every probability vector. The order controls exact pure-state entanglement conversion in Nielsen's pure-state conversion theorem.
For decreasing positive sequences in , write if every initial partial sum of is at most the corresponding partial sum of and the finite total sums agree. The finiteness requirement matters: equality of two divergent totals interpreted as infinity is too weak to guarantee a doubly stochastic realization of summable-sequence majorization.
Decreasing strictly positive summable sequences with equal totals and admit an infinite doubly stochastic matrix realizing the displayed relation. Choose with and average the pair to obtain and . The remaining decreasing sequence majorizes the remaining target sequence: short initial sums contain values at least , and longer sums are the old sums minus . Repeat on the tail, freezing one normalized finite-support row at each stage. Limit column sums are at most one; Tonelli's theorem, equal finite totals and strict positivity of every force every column sum to equal one.
If is a finite field, a vector space of finite dimension over has elements. Every infinite-dimensional vector space over is an infinite elementary abelian -group under addition.
For infinite spaces over a field of size , two-variable types are determined by the kernel of the linear map sending to . Its ranks give the zero pair, one-dimensional directions and the independent-pair type. All types are isolated by finite formulas. Quantifier elimination makes the Lindenbaum algebra their full power-set Boolean algebra. The one-variable algebra has just the zero and nonzero atoms, hence four Elements.
A subset of is a finite-field Kakeya set when it contains an affine line in a vector space in every one-dimensional direction. The line position may depend on the direction. The polynomial method in combinatorics yields the finite-field Kakeya polynomial bound on its cardinality.
For odd characteristic, the union of the lines contains a line of every finite slope. For fixed , completing the square shows that it comprises the values of for which is a square, including zero. Adding the vertical line completes the directions and gives cardinality . This is a finite-field Kakeya set whose density tends to one half.
For a finite-field Kakeya set , a smaller cardinality would give a nonzero polynomial of total degree of a polynomial at most vanishing on , by the dimension of a bounded-total-degree polynomial space. Its restriction to each complete affine line in a vector space has roots of a polynomial and degree less than , hence vanishes identically. The top homogeneous polynomial part then vanishes in every direction. A polynomial of degree less than in each variable cannot vanish everywhere on unless it is zero, giving a contradiction. For the prime field, this is the polynomial nonvanishing below the field size.
The linear span of a subset of a vector space is the set of all finite linear combinations of elements of . It is the smallest vector subspace containing : every vector subspace containing the original vectors must contain their sums and scalar multiples.
In , the linear span of is a line, the linear span of is the plane , and adding gives all of . Adding to the first set changes none of its attainable vectors, because it is already a scalar multiple of . Thus a spanning set can contain redundant generators; linear independence identifies when this redundancy is absent. In an infinite-dimensional space, an algebraic linear span still uses finite sums; a closed linear span can also include limits in a specified norm.
In a normed vector space, the closed linear span of is the closure of its linear span in the norm topology. It includes limits of finite linear combinations. In a Hilbert space, an infinite orthonormal basis spans in this closed sense, allowing norm-convergent series in addition to finite sums.
Let be the closed span of these vectors in the real l2 sequence space. A vector is orthogonal to exactly when . The characteristic roots are ; one grows geometrically and the other, , lies in . Square summability eliminates the growing solution, so . Hence is a closed hyperplane, namely the kernel of the bounded functional . This combines a recurrence with density by annihilators.
For a vector subspace , the quotient vector space consists of cosets , with vector operations induced from .
For a linear map and an invariant subspace , the rule defines a linear map on the quotient vector space . Indeed, two representatives differ by an element of , so their images also differ by an element of . Conversely, this rule is well-defined only if , by comparing every with zero.
For a vector subspace of , its codimension is the dimension of the quotient vector space . This definition also applies when is infinite-dimensional. If is a direct sum, the map is a linear isomorphism from to , so . In particular, the kernel of a nonzero linear functional has codimension one: normalize and write .
For fixed , the parallel affine lines are precisely the cosets of the indicated quotient vector space. Changing representatives adds a multiple of , so and are well-defined. The zero is the whole line , not a single point. If is a basis, the two line classes form a basis of the quotient by spanning and independence modulo .
A vector subspace is a nonempty subset of a vector space closed under vector addition and scalar multiplication, and is therefore itself a vector space. Equivalently, whenever belong to the subset, so does for all allowed scalars . In particular it contains the zero vector.
For example, the plane is a vector subspace, with basis . Indeed every element is . The parallel plane misses the zero vector and is an affine subspace instead. Homogeneous constraints produce vector subspaces: is the kernel of the linear map . This lets us describe all solutions of a homogeneous linear equation through a basis of its kernel.
For a chosen basis , the vector subspace spanned by a specified collection of basis vectors. In the standard basis of Euclidean space, its vectors have zero coordinates outside . The block coordinate gradient is the orthogonal projection of the full gradient onto this subspace. The fixed coordinate subspace consisting of the first coordinates is a particular example.
Articles were limited to the first 100 out of 1212 total.
Articles by others on the same topic
This is a section about Linear algebra!
For example, this sentence. And then another one.
This is a section about Linear algebra!
For example, this sentence. And then another one.

Linear algebra is a branch of mathematics that deals with vectors, vector spaces, linear transformations, and systems of linear equations. It provides a framework for modeling and solving problems in various fields, including engineering, physics, computer science, economics, and more. Key concepts in linear algebra include: 1. **Vectors**: Objects that have both magnitude and direction, often represented as ordered lists of numbers (coordinates).



