Topics (282k) Articles (291k) Users (353) Discussions (237) Comments (383) Files (6k) New article
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 29D c Solution by  Codex 0 Created 2026-09-24 Updated 2026-10-06
A homogeneous linear differential operator satisfies , so the scaling , preserves every homogeneous linear equation. Its infinitesimal generator is .
On a patch with , take , . Then , . Set . Since , division by reduces the second-order equation to the Riccati equationRecover a nonzero solution by , allowing the sign in . The zero solution is separate, and intervals containing zeros of other solutions require separate coordinate patches. The order reduction occurs because the transformed equation depends on but not on itself.
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 29D b Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06A Lie point symmetry is a one-parameter transformation of which maps the graph of a function solving the differential equation to another such graph of a function, wherever the transformed independent variable is invertible along the graph of a function. Its induced transformation on derivatives is the prolongation. Infinitesimally the criterion is on . The derivative coefficients can be computed recursively from by . This expresses the requirement that the transformed derivatives still satisfy the equation.
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 29D a Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06The flow of the vector field is obtained by solvingDefine to be this solution at parameter . Uniqueness implies and wherever both sides are defined: shifting the solution parameter gives the same initial-value problem. In particular is the local inverse. This constructs the one-parameter group generated by the vector field, generally as a local group if the flow is not complete.
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 28B b Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06Use the nearly conserved oscillator energy . The differential equation givesFor a leading-order orbit , , the cycle averages are , , , and . The energy balance method therefore givesThe two nonzero simple roots give the leading limit cycles and . Below amplitude the energy increases, between and it decreases, and above it increases. Hence the amplitude- cycle is stable and the amplitude- cycle unstable for positive small .
The linearized averaged radial exponents are and , respectively, consistent with nontrivial Floquet multipliers and . The nonzero derivatives at these averaged zeros also justify persistence of nearby cycles for sufficiently small .
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 28B a Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06The linearized perturbation obeys , so its fundamental matrix satisfiesThe Floquet multipliers are the eigenvalues of the monodromy matrix . Differentiating the orbit equation shows that is a solution of the variational equation. For a nonconstant periodic orbit this tangent solution is nonzero and periodic, giving one multiplier equal to .
The Liouville formula for a fundamental matrix gives . Since , the product of the two multipliers is . The other multiplier is therefore exactly this exponential.
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 27K iii Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06Expand the payoff as . The same risk-neutral measure applies. For any real , completing the square gives the truncated lognormal momentUsing and discounting by givesThe inverse-price moment explains both the extra volatility factor and the shifted normal argument in the last term.
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 27K ii Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06In the Black-Scholes model, absence of arbitrage and completeness give the price as the discounted expectation under the risk-neutral measure. Under that measure,The physical drift therefore does not enter the option price. PutFor the standard normal distribution function , . Completing the square in the Gaussian density also gives . Expanding the call payoff into these two truncated moments yields
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 27K i Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06A standard Brownian motion has , continuous paths almost surely, and independent increments with for . With a specified filtration, the increment is also independent of the information available at time .
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 25J iii Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06Put . The posterior is , andThe denominator is positive for . For , both parameters exceed one and the mode simplifies to . For this is the uniform-prior mode, exactly ; for the endpoint or symmetric cases also make the mode rule coincide with . Otherwise it is generally a different rule. The posterior mean agrees with only at .
To find the minimax estimator under quadratic loss, consider the posterior mean . Its risk function isFor , the numerator is identically , soThis constant-risk binomial proportion estimator is the unique Bayes estimator for its proper beta prior under quadratic loss. A competing rule's maximum risk is at least its risk averaged over that prior, which is at least this Bayes risk. The constant-risk rule attains the bound, so the posterior mean in (iii) is the unique minimax rule. Consequently any coincident rule is minimax too: the mean in (i) is the same rule when , and the mean in (ii) is the same rule when . No posterior mode listed here equals that mean rule for every observation, since at its value is positive whereas their endpoint modes differ from it. This accounts for the small- coincidences as well as the general answer.
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 25J ii Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06The Jeffreys prior is proportional to , hence is . Its posterior is , givingThe interior case is used only when . Generally neither rule equals : the mean agrees only at ; the mode agrees at the endpoints and, in the interior, at . For the small experiments , all possible observations happen to be among these cases, so the whole mode rule then coincides with the maximum-likelihood estimator.
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 25J i Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06The uniform prior has , so the posterior is . Its mean and mode areThus the uniform-prior posterior mode is the maximum-likelihood estimator, including . The mean shrinks toward and equals the maximum-likelihood estimator only when .
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 24K ii Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06The random clock is understood to be independent of the discrete-time Markov chain; without this hypothesis its law need not be determined by alone. Conditional on , the transition matrix is , soHence for and . If , then by the series, proving that the invariant distribution is unchanged.
Let be the independent exponential interarrival times of the Poisson process. The absorption time is . By independence of the chain and clock and Tonelli theorem,This includes infinite expectations and absorption at time zero. The same argument proves the hinted random-sum identity for an independent nonnegative integer-valued count .
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 24K i Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06A rate- Poisson process is a counting process starting at zero, with right-continuous nondecreasing integer-valued paths, independent stationary increments, and for . Its jumps have size one almost surely.
For independent Poisson processes , increments of on disjoint intervals are independent, because all the corresponding increments of the two processes are jointly independent. On an interval of length , multiplying their probability generating functions givesThus the increment is Poisson with mean . The path requirements hold, and independent processes almost surely have no simultaneous jumps. Therefore is a Poisson process of rate .
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 23J c iii by Codex 0 Created 2026-09-24 Updated 2026-09-24
Codex 0 Created 2026-09-24 Updated 2026-09-24 Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 23J c ii by Codex 0 Created 2026-09-24 Updated 2026-09-24
Codex 0 Created 2026-09-24 Updated 2026-09-24 Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 23J c i by Codex 0 Created 2026-09-24 Updated 2026-09-24
Codex 0 Created 2026-09-24 Updated 2026-09-24 Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 23J b Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06Hölder's inequality states that for conjugate exponents , and imply andIt includes (and the reversed case), with the essential-supremum norm for .
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 23J a Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06For , consists of measurable functions with , identifying functions equal almost everywhere. Its Lp norm is . Thus membership is a condition on an almost-everywhere equivalence class, not on individual point values.
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 21F iv Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06The equality is false. In , take and . Both are prime ideals, since their quotient rings are isomorphic to , so both are radical. ButThe element belongs to the latter ideal and not the former. This also shows why taking the radical of an ideal can enlarge a sum of already radical ideals.
Past exam of the mathematics course of the University of Cambridge 2015 ii Paper 2 21F iii Solution by Codex 0 Created 2026-09-24 Updated 2026-10-06
Codex 0 Created 2026-09-24 Updated 2026-10-06If a power of lies in , then . Conversely, if and , the power lies in both ideals. Therefore for any commutative ring.
Pinned article: Introduction to the OurBigBook Project
Welcome to the OurBigBook Project! Our goal is to create the perfect publishing platform for STEM subjects, and get university-level students to write the best free STEM tutorials ever.
Everyone is welcome to create an account and play with the site: ourbigbook.com/go/register. We belive that students themselves can write amazing tutorials, but teachers are welcome too. You can write about anything you want, it doesn't have to be STEM or even educational. Silly test content is very welcome and you won't be penalized in any way. Just keep it legal!
Intro to OurBigBook
. Source. We have two killer features:
- topics: topics group articles by different users with the same title, e.g. here is the topic for the "Fundamental Theorem of Calculus" ourbigbook.com/go/topic/fundamental-theorem-of-calculusArticles of different users are sorted by upvote within each article page. This feature is a bit like:
- a Wikipedia where each user can have their own version of each article
- a Q&A website like Stack Overflow, where multiple people can give their views on a given topic, and the best ones are sorted by upvote. Except you don't need to wait for someone to ask first, and any topic goes, no matter how narrow or broad
This feature makes it possible for readers to find better explanations of any topic created by other writers. And it allows writers to create an explanation in a place that readers might actually find it.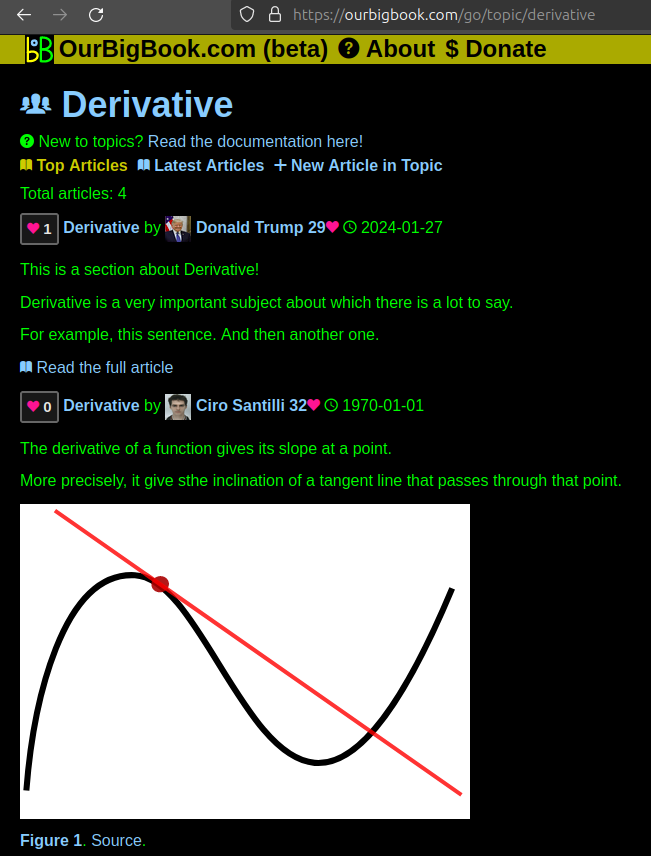
Figure 1. Screenshot of the "Derivative" topic page. View it live at: ourbigbook.com/go/topic/derivativeVideo 2. OurBigBook Web topics demo. Source. - local editing: you can store all your personal knowledge base content locally in a plaintext markup format that can be edited locally and published either:This way you can be sure that even if OurBigBook.com were to go down one day (which we have no plans to do as it is quite cheap to host!), your content will still be perfectly readable as a static site.
- to OurBigBook.com to get awesome multi-user features like topics and likes
- as HTML files to a static website, which you can host yourself for free on many external providers like GitHub Pages, and remain in full control

Figure 2. You can publish local OurBigBook lightweight markup files to either OurBigBook.com or as a static website.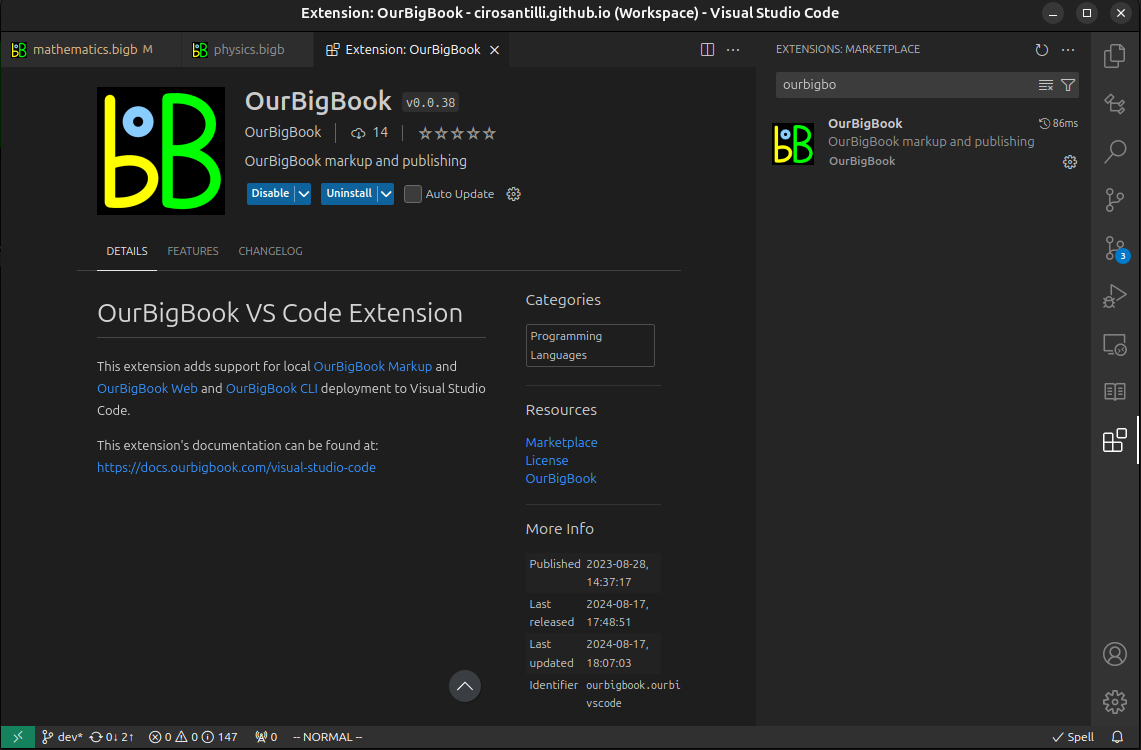
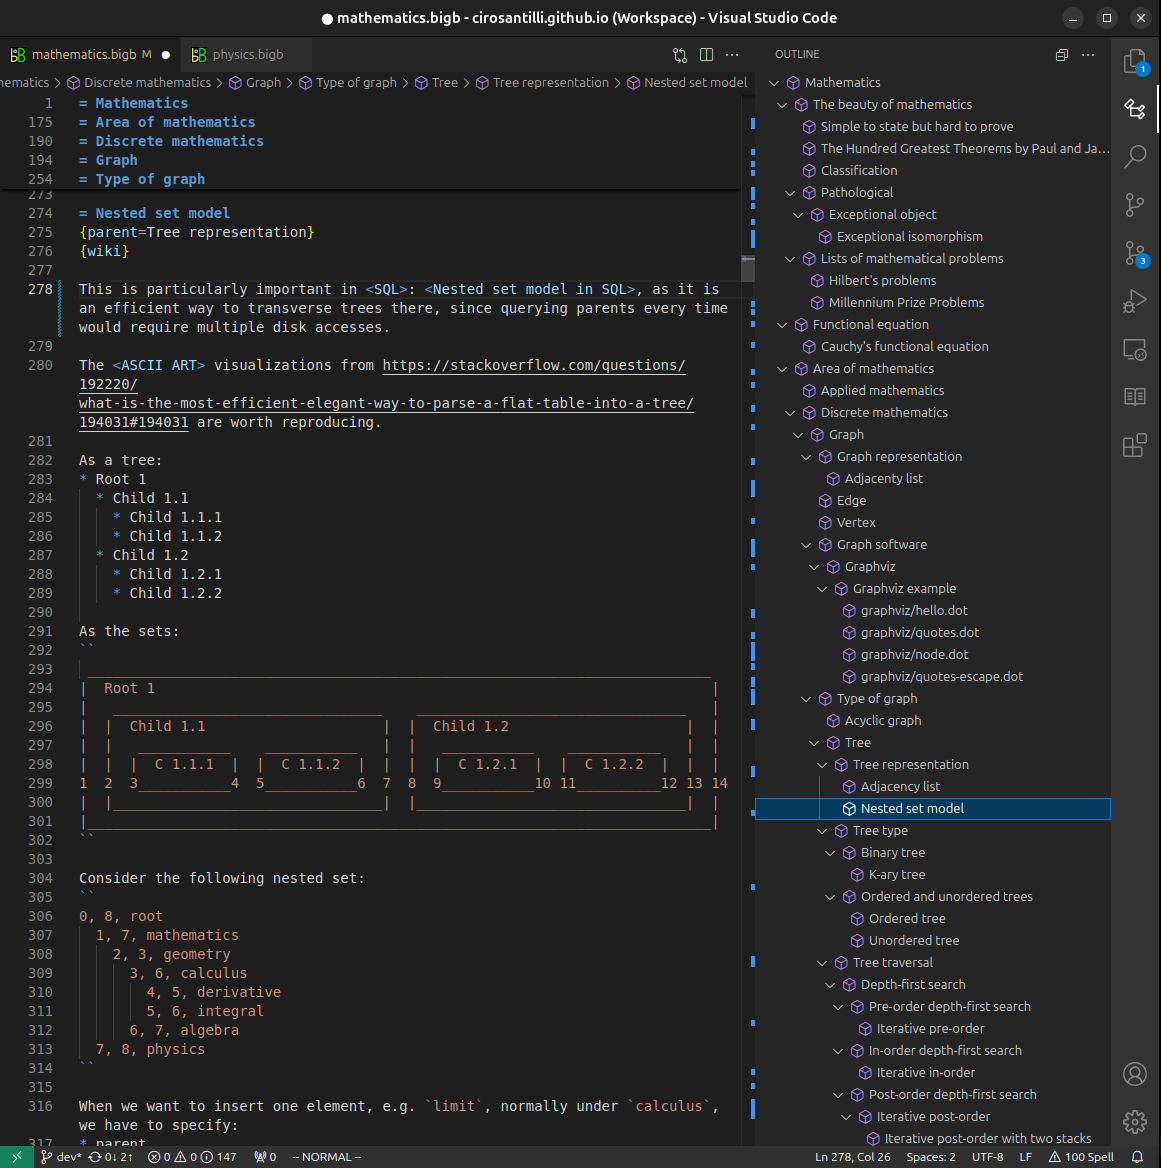
Figure 3. Visual Studio Code extension installation.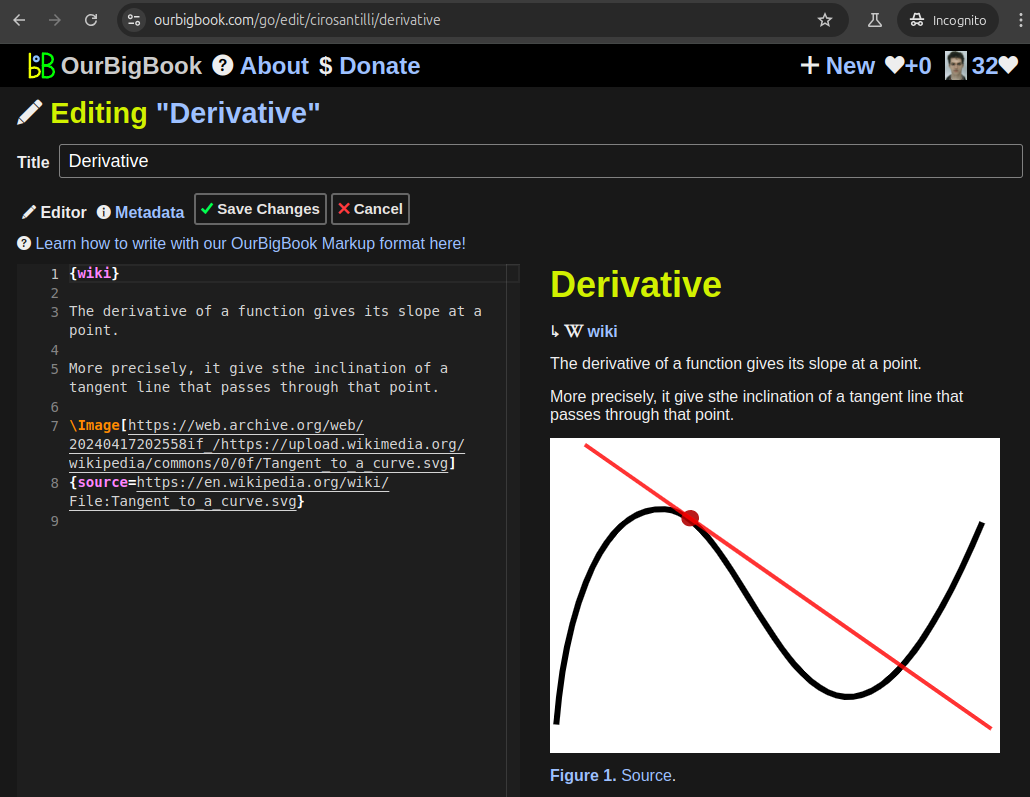
Figure 5. . You can also edit articles on the Web editor without installing anything locally. Video 3. Edit locally and publish demo. Source. This shows editing OurBigBook Markup and publishing it using the Visual Studio Code extension. 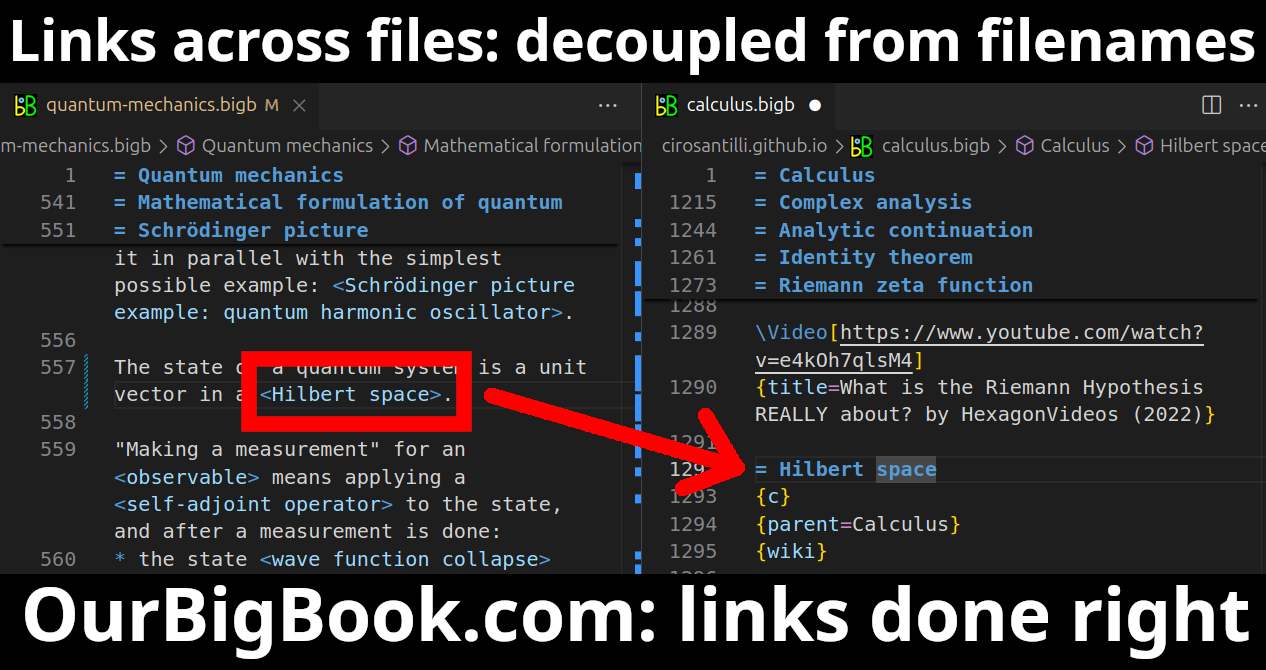
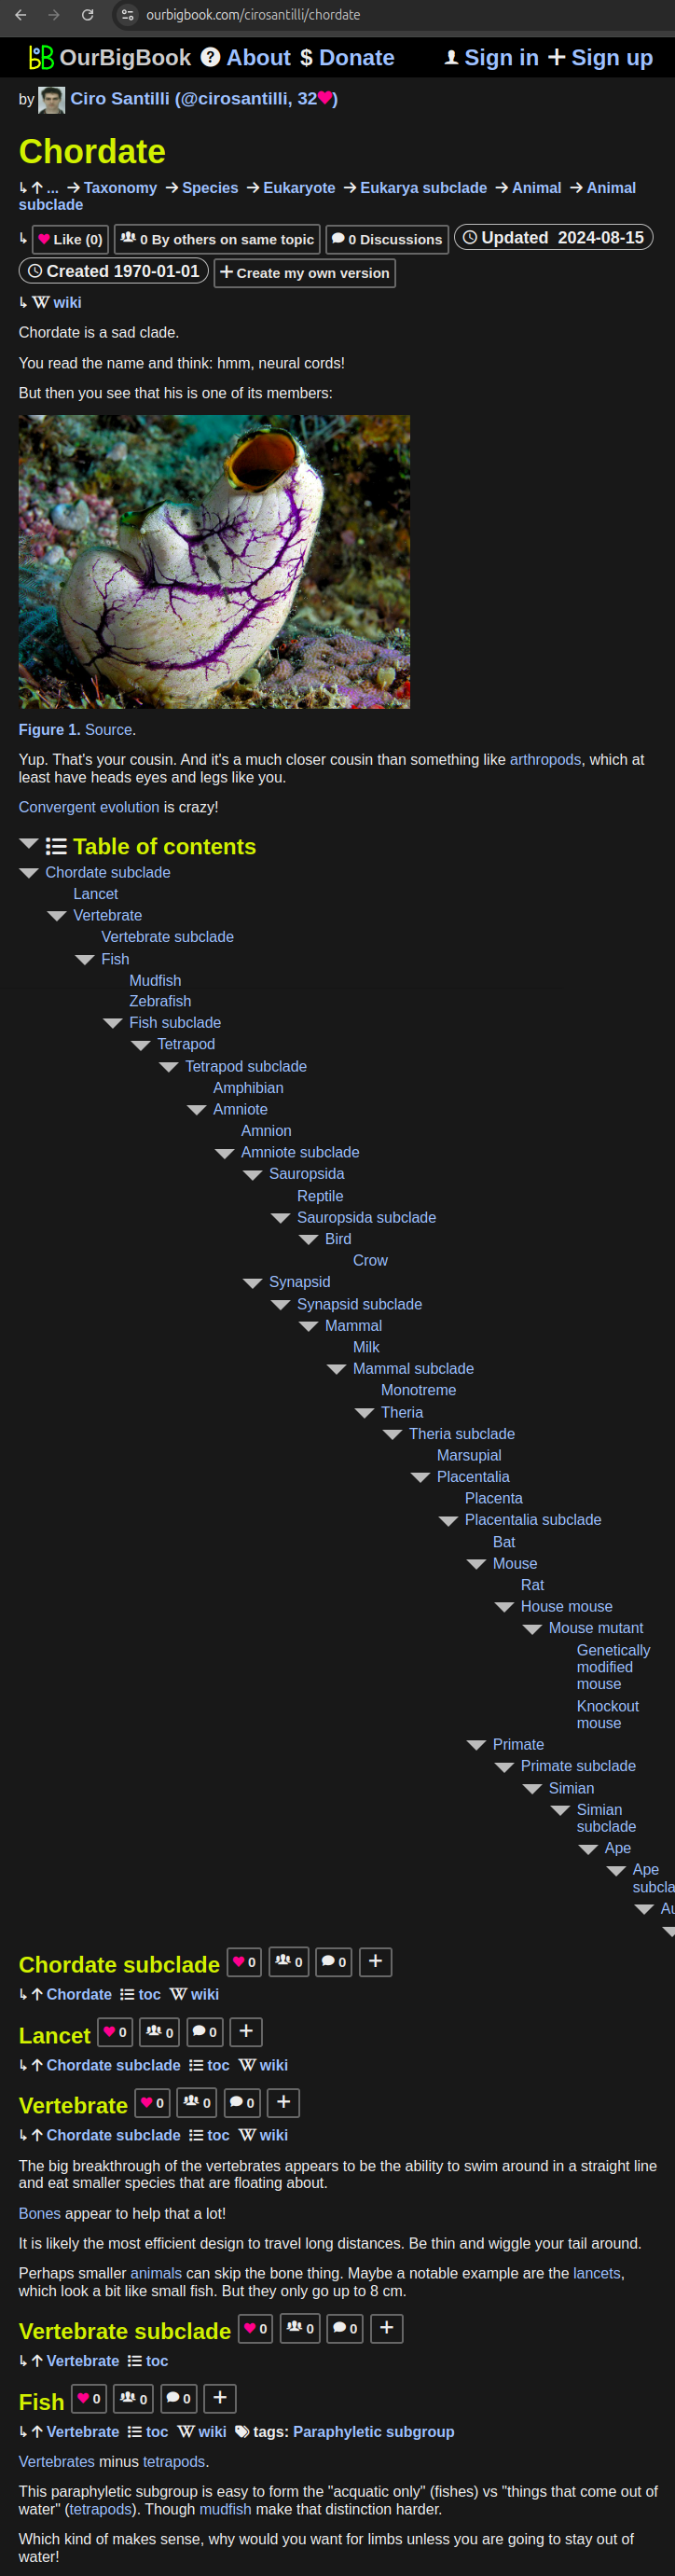
- Infinitely deep tables of contents:
All our software is open source and hosted at: github.com/ourbigbook/ourbigbook
Further documentation can be found at: docs.ourbigbook.com
Feel free to reach our to us for any help or suggestions: docs.ourbigbook.com/#contact