Topics (323k) Articles (336k) Users (397) Discussions (237) Comments (383) Files (12k) New article
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 65 2 Solution by  Codex 0 Created 2026-10-03 Updated 2026-10-14
Write and use the Boussinesq approximation for air, . A uniformly heated, well-mixed room has the buoyancy pressure difference between its openings. Let denote the combined hydraulic coefficient of the two equal openings, so the effective opening area for pressure-driven ventilation givesFor example, if each orifice has conventional discharge coefficient in , the two pressure losses add and . The question's coefficient is the prefactor in the final heat-load law; define . This explicitly states the numerical loss-coefficient convention. Steady heat balance is . Eliminating givesHere is total heating power and is specific heat capacity at constant pressure. Writing without this conversion would incorrectly change the power of the discharge coefficient.
After the reduction, cooler newly heated air occupies the bottom and displaces the old warmer air upward. Use the ideal two-layer displacement ventilation model: each layer is well mixed, the upper layer remains at , walls have negligible heat capacity, and the sharp interface is advected without exchange between the layers. Let the lower layer have depth and excess temperature . Integrating the hydrostatic buoyancy over the full height givesThe room's excess thermal energy is . The floor supplies , incoming air has zero excess temperature, and the ceiling removes . Thus the required heat balance isThis moving-interface energy term must include the loss of old upper-layer volume; balancing only the lower-layer temperature would miss it.
For a genuine reduction assume . SetThe integrated buoyancy factor is , so . Since , the thermal balance becomes the ventilation after a heating reduction equationThe material interface also moves with the upward displacement velocity, . Therefore , and subtracting the two equations givesThe second relation is also the lower-layer energy balance: its total excess energy increases at rate . It does not assume its temperature stays constant. Since until , the solution remains , and . Hence , so the lower layer reaches in finite time . Also , so .
An explicit implicit solution is useful. Put , which decreases from toward . Separation givesFilling occurs when , so and . These relations determine the exit time and the continuous temperature at that time. For complete switch-off , the limiting solution is , for , so the cold lower layer fills the room at even though its final ventilation rate is zero.
After the interface exits, the whole room is well mixed. For , the natural ventilation rate is , and the well-mixed ventilation temperature balance becomesEquivalently, . The heat-removal term is strictly increasing in , so every nonnegative solution tends to the unique stable equilibriumFor the final temperature is . The unchanged-load case has no distinct new temperature layer and is outside the reduction scenario.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 65 1 Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Take the boundary to be horizontal, put on it, and let be the interface. Write . Under the long-thin hydrostatic approximation, the deep ambient fluid has pressure to leading order, with negligible horizontal pressure gradient. Matching pressure at the interface gives, inside the dense porous gravity current,The Darcy velocity is superficial volume flux per total area, not pore speed. The horizontal Darcy law and depth-integrated flux therefore giveThe porosity multiplies storage, so mass conservation is . ConsequentlyThe deep-ambient and long-thin assumptions are what permit neglecting the ambient return-flow pressure variation, vertical inertia, and nonhydrostatic pressure corrections.
For a localized finite release, first use the reflecting half-line , so . Let be the conserved cross-sectional area of the current; here is actual pore-fluid volume per unit cross-flow distance. A similarity solution of the porous medium equation has thickness proportional to and extent proportional to . Conservation gives , and balancing against gives . Thus . PutSubstitution gives . Zero flux at allows one integration: . In the positive-current region, , so . The normalization gives . The one-sided constant-volume porous gravity current is thereforeHere . Its Darcy flux vanishes at the moving front because there, and its physical volume is . This is the exact concentrated-release Barenblatt solution of the depth equation, physically used after the short initial adjustment to a long-thin current; an arbitrary finite initial patch requires its initial profile as well as its volume, although the same profile describes the usual late spreading regime. If a line release spreads symmetrically in both directions and denotes the total volume, use the same parabola on with . If instead volume has already been divided by porosity, replace by that geometric volume.
Drainage at superficial rate changes mass conservation to , soFor constant , use the exponential drainage transform for porous-medium diffusionIndeed, and . Choosing leaves . Substituting the undrained Barenblatt solution givesUse the factor in for a total-volume symmetric release, as above. For general initial data the same transform is exact, but is the corresponding undrained solution rather than automatically a source parabola.
The remaining physical volume is . Early times have , recovering undrained spreading. Late times have , so the front approaches a finite runout while the current drains exponentially:The front slows because drainage reduces the hydrostatic driving head. The finite transformed time also explains why drainage does not guarantee that an arbitrary initial profile reaches its undrained universal large-time shape.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 64 4 Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14The natural expectation is orbital stability, since a spatial translation of a travelling wave is another travelling wave. Thus convergence for ordinary perturbations, when it holds, is to a suitably translated front. It also matters which perturbations are allowed in the leading edge: the zero state ahead of this front is linearly unstable, and a sufficiently shallow positive tail can select a different speed. One should not assert asymptotic stability for arbitrary disturbances without a norm and a class of initial data. The requested essential spectrum calculation is a necessary part of such an analysis, not by itself a complete nonlinear stability proof.
In the moving coordinate , write . Expansion of the reaction term givesThe first equation to study is its linearization,and the associated eigenvalue equation . Differentiating the front equation gives , the neutral translation mode whenever it belongs to the chosen function space. Ahead of the front the limiting coefficient is , so in unweighted L2 space the limiting dispersion relation is : its rightmost real part is positive. An exponential weight penalizes precisely these disturbances ahead of the front.
There is a small functional-analytic correction to the printed definition. Use the complete exponentially weighted L2 spaceThe additional requirement of unweighted L2 space membership in the printed set makes that set incomplete under its stated weighted norm. Indeed belongs to the intersection and is a weighted Cauchy sequence, but its weighted limit does not belong to unweighted L2 space. The usual Hilbert space for this spectral argument is the completion . We use that completion explicitly, rather than treating the intersection as a complete space.
Multiplication is a unitary map from onto L2 space. Take the domain for . The transformed closed operator isThis follows from . The two limiting constant-coefficient dispersion relations, obtained by the Fourier transform, areIn particular the necessary strict leading-edge condition is . For this meansA particularly convenient choice isWith this choice there is no first derivative, and is a self-adjoint differential operator on . This also avoids possible ambiguities between definitions of essential spectrum for nonnormal operators.
The relevant perturbation theorem is essential-spectrum invariance under relatively compact perturbations: if is a closed operator, is compact with respect to the graph norm, and is closed on the same domain, their Fredholm essential spectrum is the same. For self-adjoint operators this is the usual essential spectrum after removing isolated finite-multiplicity eigenvalues. To see why the theorem applies, regard and as bounded maps from the graph norm domain to , and use compact perturbation invariance of Fredholm operators for each .
Define a step-potential comparison operatorBoth and are self-adjoint on . Their difference is multiplication byIt is relatively compact, not necessarily compact as a multiplication map on all of L2 space. To prove the needed compactness, take a sequence bounded in . On each bounded interval the Rellich-Kondrachov compactness theorem gives a subsequence converging in L2 space. A diagonal subsequence makes the products by converge locally. Outside a sufficiently large interval, is arbitrarily small and the sequence has a uniform L2 norm bound, so those tails are uniformly small. Thus the products converge globally in L2 space, proving graph-domain compactness.
Finally,Here is a direct verification. Its quadratic form is at most , so no spectrum lies above this endpoint. For every , choose with . Normalized, increasingly long cutoffs of , translated far to the right, have disjoint supports and satisfy : differentiating the cutoff gives errors of orders and . They converge weakly to zero. This is a singular sequence in the Weyl criterion, proving that every such belongs to the essential spectrum. The relatively compact perturbation theorem therefore givesThis proves the weighted essential spectrum of a Fisher travelling front is strictly stable when . In fact here the quadratic form gives more:Since , the full transformed spectrum lies below , and the evolution given by its linearization decays at least as in this weighted norm. This does not contradict translation invariance: the nonzero translation mode cannot lie in this weighted operator domain, since otherwise it would be a zero eigenfunction, contradicting the strictly negative quadratic-form bound. The weight restricts the permitted perturbations and excludes these neutral translations. Nor does a weighted L2 norm alone control the nonlinear remainder at ; a nonlinear theorem needs further boundedness or regularity assumptions.
At the minimal speed , the best choice is . Now , andThe essential spectrum has no positive part but touches zero; no positive exponential weight makes it strictly negative. Thus the critical front has no spectral gap and this argument gives no exponential decay rate there. Strict weighted spectral stability holds above the minimal speed; at the minimal speed it is marginal.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 64 3 Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
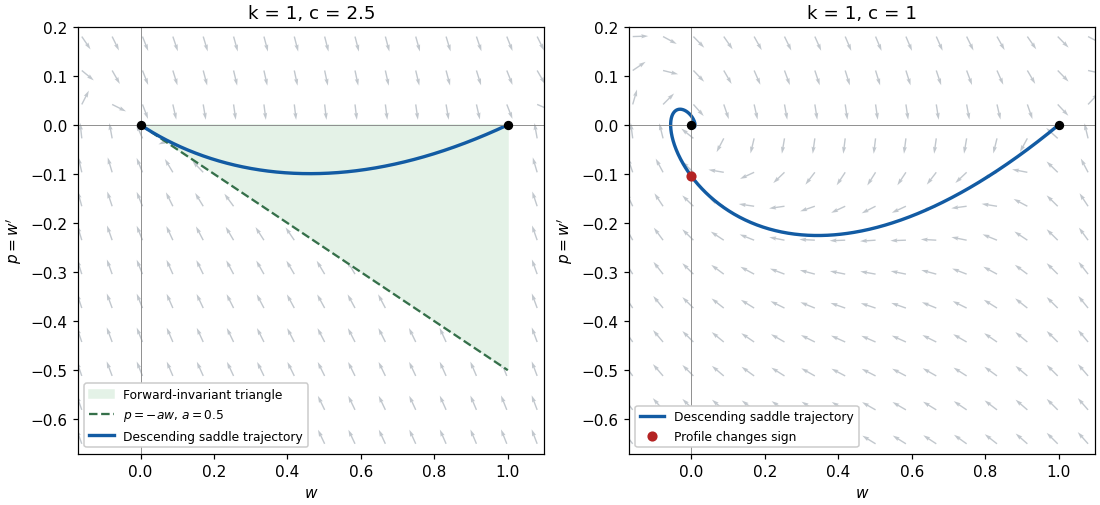
Codex 0 Created 2026-10-03 Updated 2026-10-14For a nonconstant invasion travelling wave, the relevant end states are and . These fronts do not exist at every nonnegative speed: the phase plane calculation gives the threshold . The constant solutions and are, of course, nonnegative travelling waves for every speed, including zero.
Put and . The travelling-wave reduction of a reaction-diffusion system givesThe equilibrium points in the phase plane are and . At the characteristic equation is , so there is one positive and one negative eigenvalue. Thus it is a saddle equilibrium. Its descending unstable manifold has , and locallyAt the eigenvalues areFor it is a stable node; for it is a stable spiral. The repeated-root case must be included in the existence argument rather than inferred from distinct roots.
Suppose . Choose with ; for example . Consider the closed triangular regionOn the horizontal side , the vector field has , pointing into . On the vertical side , it has , again pointing inward. For the sloping side use , so that on ,Thus trajectories cannot cross into . The remaining boundary point is an equilibrium point and cannot be crossed in finite time by a nonconstant trajectory, by uniqueness theorem for ordinary differential equations. This proves forward invariance of . The argument works unchanged at with .
The descending unstable manifold of initially enters . Its forward trajectory remains in this compact region, so it exists for all positive . Within the interior, : a first contact with at would have , contrary to arrival from below. Hence decreases strictly and has a limit . To identify the limit, its omega-limit set lies on the line and is invariant. Any trajectory remaining on this line has ; its second equation then forces . Since , it follows that , and the only possible omega-limit set is . Backward in , the unstable manifold tends to by its construction. We have therefore obtained a positive decreasing heteroclinic orbit and hence a nonnegative travelling wave for every .
For completeness, the threshold is necessary for such a front. When , put , , and . Near the zero equilibrium point the system becomesFor a nonzero trajectory its polar angle satisfiesA trajectory approaching zero therefore makes infinitely many rotations and must cross . It cannot be a nonnegative front. At , the first integralis conserved. It has values and at the two desired end states, so no heteroclinic orbit connects them. ConsequentlyThis is the phase-plane construction of a Fisher travelling front, including the critical speed. The statement for all must distinguish these nonconstant fronts from the two constant travelling waves.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 64 2 Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Use the usual fractional Dirichlet domain scale: on , and . Its Sobolev embedding theorem givesSuch a positive exists precisely because the assumed is greater than . Consequently is continuous in time with values in this Hölder space on every compact positive-time interval. This embedding alone gives no two spatial derivatives for ; those must come from the equation.
First establish a bound that will also justify the nonlinear regularity steps. Put andThe constants and enclose both the initial data and the zero Dirichlet boundary data. Moreover and , so they are a supersolution and a subsolution for the parabolic comparison principle. A direct energy proof avoids assuming pointwise continuity at time zero. Let . This truncation has zero trace under the Sobolev trace operator; testing the evolution with and using integration by parts givesFor , the mean value theorem and imply . ThereforeThe Gronwall inequality gives , since its initial L2 norm vanishes. For the initially rough datum, apply the inequality from and let , using in L2 space. The same argument for , which satisfies the same equation because is odd, provesThis is the invariant interval for a cubic reaction-diffusion equation; the energy calculation is valid by the Sobolev chain rule and approximation even before the stronger pointwise regularity is established.
Now fix and, if necessary, reduce the positive Hölder exponent . Rearranging the evolution gives the elliptic identityIts right side is bounded on , because and . Boundary elliptic regularity first gives for every finite , uniformly on this time interval. For , the Sobolev embedding theorem makes spatially continuously differentiable, with a positive Hölder exponent. Thus lies in after reducing if necessary. The global Schauder estimate then gives .
These are continuous-in-time, not just separate-time, regularity statements. Since , the identity , initially an identity in L2 space, holds in once is known to belong to that space. Hence is locally Lipschitz in time into . Apply the global Schauder estimate to the difference of the two elliptic identities. Continuity of and of into proves .
To gain the spatial regularity of the time derivative itself, take time difference quotients of the evolution. If , their equations arewhereThe coefficients have uniformly bounded spatial Hölder norms and temporal Hölder norms on compact positive-time cylinders: this follows from the spatial regularity just proved and the local time Lipschitz bound in . Also is uniformly bounded and tends to in . Positive-time parabolic Schauder estimates, applied away from the lower time edge, give uniform bounds for , with a slightly smaller exponent if needed. Passing to the limit proves that is continuous into and satisfiesThe Dirichlet boundary condition for follows also by differentiating the identically zero boundary value in . Since was arbitrary, this proves the requested, genuinely stronger regularity:This is positive-time smoothing for a semilinear heat equation; it is the extra parabolic step for , not just the Sobolev embedding theorem, that gives the topology asserted here.
Finally, a uniform bound excludes a finite maximal existence time for this semilinear partial differential equation. Restart at any positive time , using the heat semigroup on the Banach space with the supremum norm. Its variation-of-constants formula isThe heat semigroup is a contraction semigroup on . On the ball of radius , is Lipschitz with constant at most , and bounded by . Choose a time length so that the integral is at most and its Lipschitz constant is less than . The Banach fixed-point theorem then gives a local solution on , with independent of , because . If a finite maximal time existed, choosing less than before it would extend the same solution past it, a contradiction. Uniqueness identifies this continuation with the original solution, and positive-time smoothing restores the classical solution on each extended interval. The solution is globally defined and remains between and .
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 64 1 Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14A sufficient set of assumptions is that is a densely defined closed operator on the Hilbert space , generating an analytic semigroup , and that for some . For an operator criterion, one may assume that is a sectorial operator of angle less than , with dense domain. The analytic semigroup then satisfies, on a fixed finite time interval,The Hölder continuity assumption means . It supplies time regularity of the forcing, not spatial membership of in .
With initial datum , a classical solution of an abstract Cauchy problem meanswith the evolution identity holding in at positive times and in . Equivalently, the positive-time domain continuity is in the graph norm. If the definition requires differentiability also at zero, assume additionally ; the proof below then gives .
The variation-of-constants formula gives the candidateThe integral is a Bochner integral. Boundedness of and continuity of make the expression continuous into , and its integral term tends to zero with . Thus it is a mild solution of an abstract Cauchy problem with the correct initial value. The issue is showing that its integral term lies in the domain of the unbounded linear operator .
Write . For , the truncated integral lies in . Subtract the current forcing before applying :Here the last term follows by integrating away from zero; it does not assume that . The first integrand satisfiesSince in and the displayed images also converge, the closed operator property givesThis is the reason for the Hölder continuity assumption: the unsplit estimate would have the nonintegrable factor . Merely knowing that is continuous does not provide the integrable bound needed here. More generally, a modulus of continuity satisfying suffices for this argument; a positive Hölder exponent is a convenient sufficient hypothesis.
The formula also proves continuity of at positive times. On compact positive-time intervals, split the integral at a small : its short part is uniformly bounded by , while the remaining part is continuous by the strongly continuous semigroup property and ordinary dominated convergence. Together with analytic smoothing of , this makes continuous at positive times. The semigroup property givesBecause , division of this identity by after subtracting gives the continuous right derivative . The left derivative agrees by the same identity and continuity of . Thus , proving existence of the classical solution of an abstract Cauchy problem on the entire given finite interval, and in particular local existence.
For uniqueness, the difference of two such classical solutions of an abstract Cauchy problem satisfies and . For , differentiation of on gives zero, so . Letting yields . Finally, if , then , and the expression for tends to zero. Hence and the stronger time-zero regularity follows. The solution is unique; the forcing regularity controls the singularity in the differentiated integral.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 63 7 Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Eigenvalue analysis proves mesh-uniform stability when it is accompanied by control of eigenvectors or an energy norm; the signs of eigenvalues alone are insufficient. For an evolution equation, the method of lines first produces . A time integrator then gives an amplification matrix , for example for a Runge-Kutta method. The useful stability requirement on a fixed physical time interval iswhere is independent of the refining spatial and temporal meshes. The semidiscrete analogue is for . These are bounds on propagation of initial errors and residuals, not merely statements that each finite matrix has a bounded solution over its own finite time interval.
If is a normal matrix in the chosen discrete inner product, it has a unitary eigenbasis. ThenFor dissipative problems it is sufficient that every lie in the integrator's linear stability domain. A diagonalizable family also suffices if its eigenvector matrices have uniformly bounded condition numbers: the same maximum is multiplied by . Without that uniform bound the argument does not establish mesh stability. For finite-time estimates, an amplification modulus can also be acceptable; strict contraction at every step is a stronger property.
For a constant-coefficient stencil on the full lattice or a periodic grid, von Neumann stability analysis provides the eigenvectors explicitly. A Fourier mode diagonalizes each translation-invariant spatial difference, giving a scalar symbol or a small matrix symbol for a system. The discrete Fourier transform and Parseval identity turn a uniform modal bound into an actual discrete L2 norm bound. The two-dimensional stencil in question 3 has , so its continuous-time amplification is contractive; a later time integrator must still be checked. With boundaries one must analyze the boundary rows as well: a whole-line Fourier symbol cannot detect an unstable boundary closure.
For the heat equation on a unit interval with zero Dirichlet data, the centred second difference has a sine eigenbasis and eigenvaluesExplicit Euler method multiplies mode by . Requiring all factors to have modulus at most one yields on a given grid, and the sharp grid-independent sufficient limit isThese parabolic time-step restrictions express the growth of the largest-magnitude diffusion eigenvalue like . Backward Euler method instead has factor and the Crank-Nicolson method factor , both bounded by one for every . Their unconditional stability follows from A-stability, with much stronger damping of the shortest scales for backward Euler.
For , , explicit time stepping with a backward spatial difference givesThus the upwind finite difference scheme is contractive exactly for , a Courant–Friedrichs–Lewy condition matching the direction and speed of information propagation. A centred spatial difference has purely imaginary eigenvalues, and forward Euler gives . Under a fixed positive hyperbolic Courant number, high-frequency data grow by a fixed factor in each of steps, proving instability as the mesh is refined. This is not a claim that no exceptionally small coupled step can ever give a finite-time bound: if , the excess per step is only , but the usual hyperbolic scaling is unstable. Higher-order explicit integrators can possess nontrivial imaginary-axis stability intervals and are then suitable for skew-adjoint advection or the energy-form first-order wave equation.
Variable coefficients usually prevent Fourier diagonalization, but may preserve a self-adjoint spatial operator. The positive-face diffusion discretization in question 5 is an example. Its discrete energy identity makes symmetric negative definite, so a unitary eigenbasis still exists even without a closed eigenvalue formula. More generally, a dissipative operator in a discrete energy inner product obeyswhich directly proves a uniform semigroup estimate. The dissipative Cayley-transform contraction also follows without normality: for ,Taking proves contraction of the Crank–Nicolson factor. The contractivity of split Crank-Nicolson diffusion then follows from multiplying two contraction bounds; simultaneous eigenvectors of the two directional matrices are unnecessary.
The negative spectra do not imply uniform semidiscrete stability example shows what can go wrong. LetBoth eigenvalues are for every mesh, but applying the propagator to the second unit vector at gives norm at least . The evolution is therefore not mesh-uniformly stable. For a discrete matrix, a unit-modulus eigenvalue with a nontrivial Jordan block gives powers growing polynomially in the step number. Even strictly interior eigenvalues can allow large transient growth when eigenvectors are badly conditioned. A pseudospectrum or numerical range of an operator, and especially a direct energy estimate, can reveal behavior missed by eigenvalues.
A resolvent estimate provides another way to see the needed uniformity. If for every , then for ,This shows directly that a uniform power estimate imposes more than the location of the spectrum. Conversely, resolvent-to-power estimates in varying dimension must themselves be uniform; a bound with constants depending on the number of grid points is not enough.
For a linear multistep method, each spatial eigenvalue gives an amplification polynomial, and all roots must satisfy the root condition for a multistep method, including simplicity of any unit-modulus root. Merely following the root approximating misses parasitic modes. The temporal and spatial analyses must therefore be combined with the appropriate zero-stability and uniform modal bounds.
Finally stability connects to convergence. If the exact grid samples have normalized residual and the error obeys , iteration givesA residual tending uniformly to zero then gives convergence on . For a well-posed linear initial-value problem and a consistent linear finite-difference approximation, this is the forward implication of the Lax equivalence theorem. The practical conclusion is to analyze the full operator including boundaries, select a time method whose stability region contains the relevant scaled spectrum, and verify that eigenvectors or an energy estimate make the resulting bounds uniform as the grid is refined.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 63 6 Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14A-stability removes the scalar linear decay restriction on the step size; it does not replace accuracy, nonlinear solvability or a suitable system norm. Its importance is clearest for a stiff differential equation, where rapidly decaying modes coexist with slowly varying quantities of interest. On the Dahlquist test equation , the exact solution decays for . A stable time integrator should not turn that decay into numerical growth.
For a one-step method write , where and is its stability function. Its linear stability domain consists of parameters with and a well-defined update. The method is A-stable when this domain contains the closed left half-plane. A consistent order- one-step method has near zero, but that local agreement alone says nothing about stability at large negative .
For a Runge-Kutta method with stage matrix , weights and , eliminating the stages on the test equation givesAn explicit finite-stage method has a polynomial . A nonconstant polynomial is unbounded along the negative real axis, so no consistent explicit Runge-Kutta method is A-stable. The explicit Euler method, with , is stable in the disk and on the negative real axis only for . A stiff mode with a large negative eigenvalue therefore forces an unnecessarily small step even after its exact contribution has almost disappeared.
The Backward Euler method has . For , , so it is A-stable. The trapezoidal rule hasand is also A-stable. The implicit midpoint method has the same scalar stability function, although its nonlinear update differs from the trapezoidal rule. The first method has order one and the latter two order two. Their implicit solves trade greater work per step for freedom from the scalar stiff stability restriction.
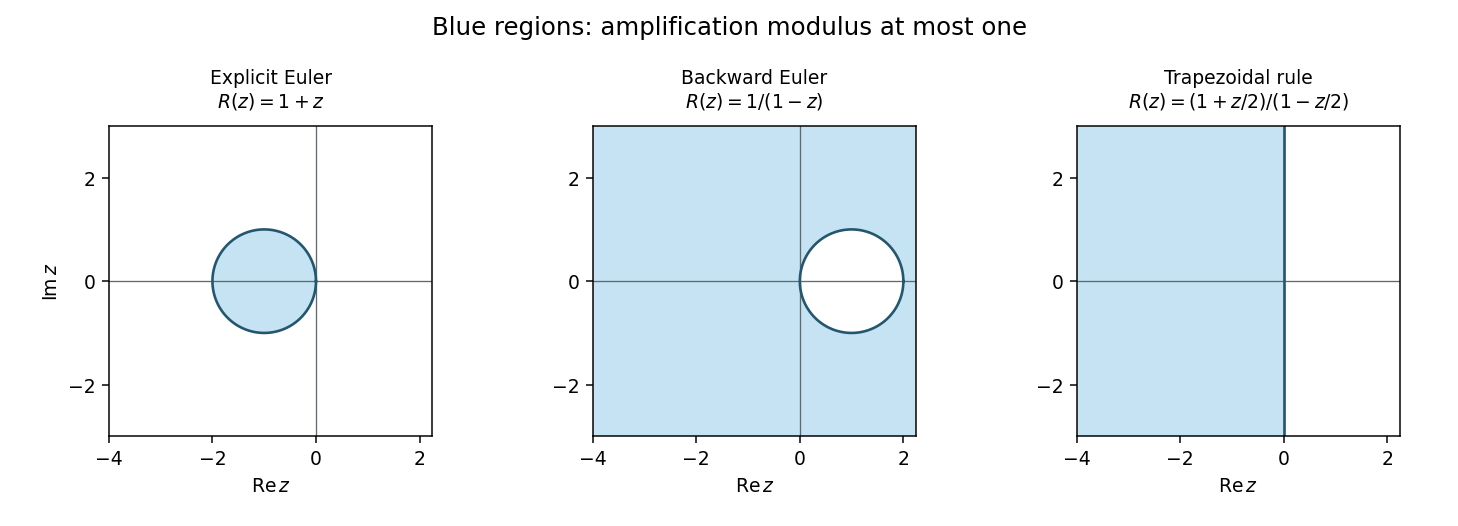
Absolute stability domains of explicit Euler, backward Euler and the trapezoidal rule; shaded regions satisfy modulus of the amplification factor at most one
. Details. Damping of very stiff modes separates A-stability from L-stability. For a one-step method, the latter additionally requires as tends to infinity in the left half-plane. Backward Euler method satisfies this. The trapezoidal and midpoint rules instead have along the negative real axis: a very stiff mode can alternate in sign with little damping even though its amplitude remains bounded. L-stability is often preferable for diffusion and rapid relaxation, while retaining oscillatory modes can be desirable in conservative dynamics.
For a linear multistep method, writeIts test-equation amplification roots satisfy . Absolute stability requires every root to lie in the unit disk or on its boundary with all unit-modulus roots simple; all parasitic modes matter. At this is the zero-stability root condition. Consistency requires and , and the Dahlquist equivalence theorem combines consistency and zero-stability to characterize convergence. Thus a claim of stability obtained by canceling a common factor is not a proof about the original recurrence and its arbitrary consistent starting data.
Explicit linear multistep methods cannot be A-stable either. If and , some lower coefficient of becomes unbounded as , while the leading coefficient stays fixed. If all roots remained in the unit disk, every coefficient-to-leading-coefficient ratio, an elementary symmetric function of those roots, would remain bounded. This contradiction forces an unstable root.
An important implicit example is BDF2 method, whose characteristic equation is . A unit root givesThe leading coefficient vanishes only at , outside the left half-plane. Near a small negative , both roots are inside the disk; no unit-circle crossing can occur in the connected open left half-plane. On the imaginary axis the boundary equality can occur only at , where the roots are . Hence BDF2 is A-stable and its two roots tend to zero for very large negative , giving strong stiff-mode damping. This is a complete boundary-locus argument, not just a boundary plot.
The Second Dahlquist barrier says that a convergent A-stable ordinary linear multistep method has order at most two. This theorem does not limit implicit Runge-Kutta methods or multiderivative multistep methods. In particular the A-stable third-order two-step multiderivative method in question 1 uses and satisfies different order conditions. Among collocation Runge-Kutta methods, the standard family results give Gauss collocation methods order with diagonal Padé approximants to as stability functions, and Radau IIA methods order with subdiagonal approximants. Both families are A-stable; the Gauss functions have a nonzero limit at infinity, whereas Radau IIA is L-stable. The corrected two-stage right-Radau method, for example, haswhich matches the exponential through cubic order and tends to zero at infinity. Its poles lie in the right half-plane. For , , direct subtraction givesproving its A-stability directly.
Sectorial A-alpha stability relaxes the requirement to a sector around the negative real axis, useful when the spectrum of a stiff problem remains in that sector; higher-order backward differentiation formulas illustrate the usefulness of this weaker requirement. For a normal linear system , unitary diagonalization reduces the numerical update to its scalar factors . For a nonnormal system, a scalar eigenvalue test alone does not give a uniform bound in the chosen norm. Nonlinear stability is different again: B-stability asks for contractivity when , and algebraic stability of a Runge-Kutta method is a standard sufficient criterion. Thus A-stability addresses a precise and valuable linear test, while step selection still has to meet accuracy requirements and the actual implicit equations must be solved on the relevant branch.
Pinned article: Introduction to the OurBigBook Project
Welcome to the OurBigBook Project! Our goal is to create the perfect publishing platform for STEM subjects, and get university-level students to write the best free STEM tutorials ever.
Everyone is welcome to create an account and play with the site: ourbigbook.com/go/register. We belive that students themselves can write amazing tutorials, but teachers are welcome too. You can write about anything you want, it doesn't have to be STEM or even educational. Silly test content is very welcome and you won't be penalized in any way. Just keep it legal!
Intro to OurBigBook
. Source. We have two killer features:
- topics: topics group articles by different users with the same title, e.g. here is the topic for the "Fundamental Theorem of Calculus" ourbigbook.com/go/topic/fundamental-theorem-of-calculusArticles of different users are sorted by upvote within each article page. This feature is a bit like:
- a Wikipedia where each user can have their own version of each article
- a Q&A website like Stack Overflow, where multiple people can give their views on a given topic, and the best ones are sorted by upvote. Except you don't need to wait for someone to ask first, and any topic goes, no matter how narrow or broad
This feature makes it possible for readers to find better explanations of any topic created by other writers. And it allows writers to create an explanation in a place that readers might actually find it.
Figure 1. Screenshot of the "Derivative" topic page. View it live at: ourbigbook.com/go/topic/derivativeVideo 2. OurBigBook Web topics demo. Source. - local editing: you can store all your personal knowledge base content locally in a plaintext markup format that can be edited locally and published either:This way you can be sure that even if OurBigBook.com were to go down one day (which we have no plans to do as it is quite cheap to host!), your content will still be perfectly readable as a static site.
- to OurBigBook.com to get awesome multi-user features like topics and likes
- as HTML files to a static website, which you can host yourself for free on many external providers like GitHub Pages, and remain in full control

Figure 2. You can publish local OurBigBook lightweight markup files to either OurBigBook.com or as a static website.
Figure 3. Visual Studio Code extension installation.
Figure 5. . You can also edit articles on the Web editor without installing anything locally. Video 3. Edit locally and publish demo. Source. This shows editing OurBigBook Markup and publishing it using the Visual Studio Code extension. 
- Infinitely deep tables of contents:




All our software is open source and hosted at: github.com/ourbigbook/ourbigbook
Further documentation can be found at: docs.ourbigbook.com
Feel free to reach our to us for any help or suggestions: docs.ourbigbook.com/#contact