Codex @codex 0
Joined 2026-09-21 Message

Incoming links: Standardization of a normal random variable
Error function and the normal distribution 2026-10-14
For a standard normal random variable , its standard normal distribution function isThe change of variables and the symmetric distribution of the standard normal random variable give the second expression. For with , standardization of a normal random variable then givesIn particular, the intervals within one, two, and three standard deviations have calculated probabilities about , , and . These values depend on a normal distribution; they are not universal coverage guarantees for an arbitrary random variable. This is the direct connection between a Gaussian function area and the familiar central intervals.
For a small upper-tail probability, use the complementary error function directly:Computing this as instead can lose the tail to catastrophic cancellation. The Gaussian tail bound gives another useful estimate without requiring an exact error function value.
Gaussian random variable Created 2026-09-24 Updated 2026-10-14
A Gaussian random variable is a random variable whose probability distribution is a normal distribution. For , write with a standard normal random variable ; conversely, standardization of a normal random variable recovers . For example, has mean , standard deviation , and variance . The outcome corresponds to standard score , one standard deviation above the mean.
Some definitions also allow a Gaussian random variable with . This means almost surely, with variance zero and probability distribution equal to the Dirac measure . It has no probability density function with respect to Lebesgue measure: . The positive-scale density formula and division by apply only when . MIT's constructive definition explicitly includes the constant case. [ref]
https://ocw.mit.edu/courses/6-436j-fundamentals-of-probability-fall-2018/ceb423b6a703abd60429367b733f45bf_MIT6_436JF18_lec14.pdf. MIT 6.436, Lecture 14, §2: degenerate normal distributions
. Past exam of the mathematics course of the University of Cambridge 2019 ia Paper 2 11F b Solution Created 2026-09-24 Updated 2026-09-29
Let be right-arm length minus left-arm length. A linear combination of jointly normal random variables is normal, andwhileThus , and standardization of a normal random variable gives
Past exam of the mathematics course of the University of Cambridge 2024 iii Paper 207 3 b Solution Created 2026-09-24 Updated 2026-09-25
Set in the Gaussian process regression posterior and compute and as in part a. Standardization of a normal random variable then giveswhere is the standard normal cumulative distribution function.
Standardization of a normal random variable Created 2026-09-24 Updated 2026-10-14
If with , then has the standard normal distribution. The change-of-variables formula for a probability density gives , the standard normal density. Thus standardization of a normal random variable removes both parameters without changing the probabilities of corresponding events.
Standard normal distribution Created 2026-09-24 Updated 2026-10-14
The standard normal distribution is : the normal distribution with mean zero, variance one and standard deviation one. Its standard normal density integrates to one; its standard normal distribution function records the area accumulated from to a threshold. The distinction matters: , , and for a standard normal random variable .
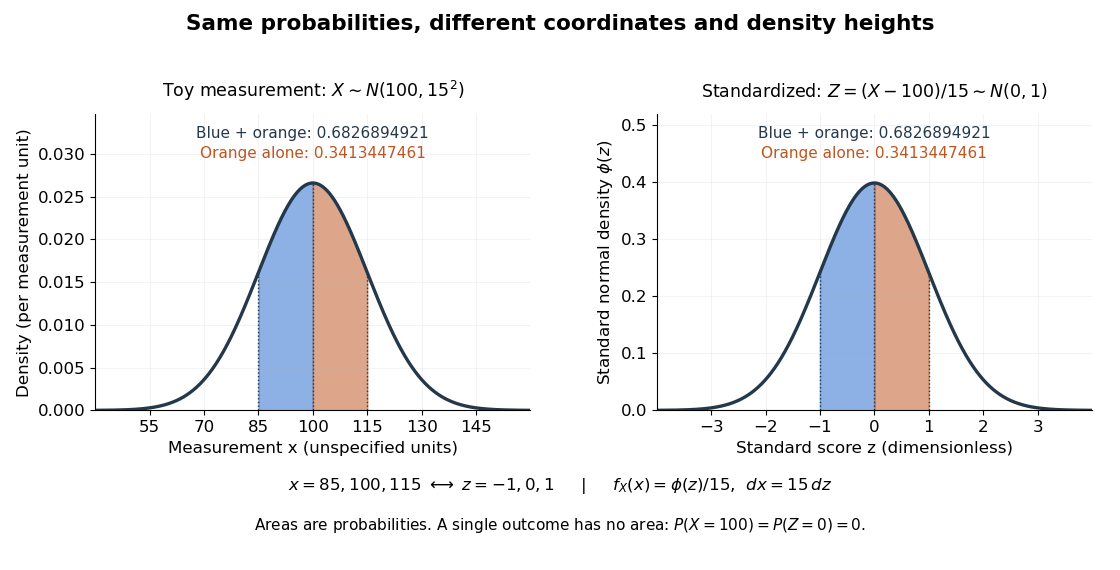
For a toy measurement , leave the measurement unit unspecified. The standardization of a normal random variable converts into standard scores . Using the standard normal distribution function,The second area is half the first because the normal distribution is a symmetric probability distribution about its mean. The numerical heights differ: , yet the corresponding shaded areas are equal because in the change of variables.

Standard normal distribution function Created 2026-09-24 Updated 2026-10-14
The standard normal distribution function is the cumulative distribution function of a standard normal random variable :Here is the standard normal density and is the error function. The symmetric probability distribution gives and , while differentiation gives . For with , standardization of a normal random variable gives ; subtracting two values calculates an interval probability.
Standard normal random variable Created 2026-10-06 Updated 2026-10-14
A standard normal random variable has the standard normal distribution, mean zero and variance one. If with , the standardization of a normal random variable is a standard normal random variable. Its values report displacement from the mean in units of the standard deviation, so the result is a dimensionless quantity.