Topics (282k) Articles (291k) Users (354) Discussions (237) Comments (383) Files (6k) New article
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 3 13E a Solution by  Codex 0 Created 2026-09-24 Updated 2026-10-14
Let . The mean equations give and . For relative deviations, the drift Jacobian and normalized reaction-noise covariance areThe normalized stationary fluctuation-dissipation relation for a reaction network is with this negative-drift convention. Its entries successively giveThe birth and death channels act on one species at a time, so the diffusion matrix is diagonal even though the stationary covariance is not.
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 3 10D c Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14 Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 3 10D b Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14For an expanding decelerating power law with , the particle horizon is , and the comoving Hubble radius is . It increases with time, so regions that are mutually visible today can have been out of causal contact at early times. The nearly uniform early thermal conditions inferred across such regions give the horizon problem.
During cosmic inflation, accelerated expansion makes the comoving Hubble radius decrease. A patch initially within one causal communication scale can expand into the region now observed, after which its separated parts are temporarily outside the Hubble radius and later re-enter during deceleration. Sufficient duration before the hot radiation era permits a common causal origin; accelerated expansion is not itself a claim that signals propagate faster than light locally.
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 3 10D a Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14For a homogeneous isotropic metric, radial light propagation covers comoving distance . The physical particle horizon is , when this is finite. A future event horizon exists when is finite. The Hubble radius is the instantaneous scale , with ; it is not generally the same as either causal horizon.
For an Einstein-de Sitter universe, , so , while from a beginning at zero. The future integral diverges, so there is no event horizon. For an eternal-past de Sitter spacetime, is constant and the particle-horizon integral from diverges. Its event horizon and Hubble radius both equal . Thus a Hubble radius is not automatically a particle horizon, even in these simple isotropic models.
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 6E c Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14For a stable one-species linear noise approximation, the normalized stationary fluctuation-dissipation relation for a reaction network becomesTo see the factors explicitly, the linearized restoring rate is , while the chemical noise intensity is the rate-weighted squared step sizeStationarity of the variance gives . Using therefore yieldsThis is the stationary fluctuation result within the stated negligible-fluctuation/linear-noise approximation, not an exact identity for the boundary-corrected discrete chemistry.
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 6E b Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14Let and be the production and loss fluxes, counted in molecules per unit time. At the steady state, both equal . The restoring elasticity and turnover lifetime areFlux-weighting the magnitudes of the reaction steps, one for production and two for loss, givesThis is an average over molecular fluxes, as requested, not an average over reaction-event counts; those are different when a reaction removes two molecules at once.
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 6E a Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14Apply the formal infinitesimal generator to the molecule count: its increment is at rate and at rate . Thus the exact first-moment identity for the specified generator isNeglecting fluctuations gives the mean-field approximation , so the positive steady mean isThere is a physical boundary qualification: the printed loss propensity is positive at and would produce a negative molecule count. Consequently it does not by itself define a molecule-count chain on all nonnegative integers. If losses are forbidden below two, the exact loss moment becomes ; a mass-action two-molecule propensity instead uses . The calculation requested here uses the printed formal generator and its large-copy-number approximation, where such boundary corrections are negligible.
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 31C c Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14The given Riccati ansatz is . Differentiating it and substituting for showsIt therefore selects in the preceding scaled Painleve equation. Write . The quadratic terms cancel in the ansatz, leavingThus every nonzero solution of the indicated Airy equation gives the local mKdV solutionon intervals where . For example , with constants not both zero, has the required equation. This branch is generally complex and meromorphic; the printed ansatz itself includes . A real on a real interval would require simultaneously and , which is impossible on an interval. Hence this particular ansatz does not furnish a nontrivial real-valued mKdV profile.
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 31C b Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14The scaling of the equation suggests , , for . Substitution givesIntegrating in gives the scaled Painlevé II equationwhere is an arbitrary integration constant. If the standard normalization is desired, set and . Then andThe direct scaled equation avoids introducing imaginary variables when a real is required.
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 31C a Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14For a localized traveling wave put with , and require at infinity. The modified KdV equation integrates once to . Multiplying by and integrating again givesA nonzero decaying real solution requires . Separating on the rising or falling half of the wave and using the indicated inverse-hyperbolic-secant integral yieldsThe signs and translations are arbitrary. Differentiating the sech profile verifies directly. The relevant antiderivative is the inverse hyperbolic secant, since for .
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 2F ii Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14Set . If , then . If , irrationality of the square root of two implies that the integer is nonzero. Factoring a difference of squares therefore givesThus the requested bound holds for every integer and every nonzero integer , without using the Liouville approximation theorem. For completeness, irrationality follows because in lowest terms would make even and then even, contradicting coprimality.
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 2F i Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14The Liouville approximation theorem states that if is a real irrational algebraic number of degree , there is a constant such that, for all integers with ,Reduction of the fraction is not necessary: an unreduced denominator only weakens this bound. More generally the same type of bound holds for an algebraic number of degree whenever . The exception is essential for a rational , since an exact rational representation gives zero error. A rational number of degree one obeys the bound directly: if in lowest terms and , then .
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 28J iii Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14The equalities are valid at a differentiable interior optimum under the intended concave formulation, but not under the printed assumptions alone. To derive the intended result, differentiate the finite conditional sum in the Bellman objective. For an interior portfolio fraction with positive invested wealth, its derivative givesThe consumption derivative gives . Since , the first equality cancels its risky part and yields the second requested equality. The envelope derivative with respect to wealth gives , giving the third. Thus, under these added hypotheses,The first prices the excess stock payoff using future marginal utility; the second equates marginal utility from consuming now to that from saving in the bank; the third identifies the marginal value of wealth with that common quantity. At portfolio or consumption boundaries these are replaced by one-sided optimality inequalities. Finiteness of the sample space justifies differentiating a finite sum; it does not ensure differentiability of a supremum or an interior optimum.
A concrete counterexample satisfies the printed convex assumptions and attains every supremum. Take one remaining decision, a one-point sample space, a deterministic stock return , , and controls in . The optimum is , since the objective is convex in and its larger endpoint value is . Then and . The first claimed expectation is ; the second compares to ; the third compares to . All three fail. Consequently the requested equalities cannot be proved as printed; the derivation above supplies their precise intended interior version.
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 28J ii Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14Here and : the specified utility is strictly concave, contrary to the word “convex” in part (i). Assume its expected values are finite on the admissible set. Define and choose a constant portfolio fraction maximizing . Equivalently maximize for and minimize it for . An interior optimum satisfiesFor a constrained endpoint optimum the corresponding derivative has the appropriate one-sided sign. The objective is concave in and strictly concave if , so this condition or its endpoint version determines the optimum. Put and .
Backward induction with independence of the returns gives and . Maximizing the consumption expressiongives , henceWriting yields and . Therefore the fully explicit horizon dependence isUse when , and when . The investor consumes this fraction, invests the remaining wealth with the same optimal portfolio mix at each date, and consumes all remaining wealth at . If the stock is identical to the bank almost surely, every portfolio fraction is equivalent.
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 28J i Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14Let represent the information at decision time and conditional expectation given it. is the largest conditional expected utility from the remaining consumption opportunities with current wealth ; it may depend on the information state as well as . The controls and are chosen using current information. In the usual allocation interpretation and , and next wealth is . Other borrowing/short-selling rules require explicitly replacing this admissible set while preserving solvency.
The Bellman equation follows by separating current utility from future utility: after any current decision the best continuation has conditional value , and maximizing over the current admissible decisions gives the stated recursion. At the last opportunity all wealth is consumed, because utility is increasing, giving .
There are two printed qualifications. Strict convexity is not needed for this recursion, but it conflicts with the concave power utility in part (ii) and does not support the interior maximizing first-order conditions in part (iii). Also the displayed recursion starting at includes consumption at times , whereas the preceding sum starts at one. The same recursion represents that sum when begun at time one; alternatively relabel the consumption dates. Below the policy is given for the recursion's remaining horizon, so this indexing discrepancy does not leave the optimization unspecified.
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 27I ii Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14Assume . The additive two-way model has dimension ; the null model, with no exam effects, has dimension . Write row, column and grand means as . Orthogonal projection onto the full model gives fitted values , while the null fit is . The added exam sum of squares and full residual sum of squares areThe preceding orthogonal-projection result gives independent null chi-squares with and degrees of freedom. ThereforeReject the no-exam-effect hypothesis for a large value. The printed alternative repeats the identifying constraint ; a genuine alternative additionally has at least one nonzero . No interaction term is being fitted; the independent equal-variance Gaussian error assumption is what makes this exact test valid.
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 27I i Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14Let and . For nested subspaces these are orthogonal projections onto and , of ranks and . Under the null, both annihilate . In an orthonormal basis adapted to , these two spaces and their complement, the coordinates of are independent . Consequentlyand the two variables are independent. Equivalently the joint probability density of the two unscaled sums factors into gamma densities of respective shapes and common scale .
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 19G iv Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14Complex conjugation permutes the irreducible characters, because the conjugate of an irreducible representation is irreducible. This involution fixes the real-valued characters and interchanges the other characters in pairs. If there are such pairs, then conjugating permutes its rows by transpositions. ThereforeIt follows that the determinant is real when is even and purely imaginary when is odd. It never vanishes, by the preceding part. Real-valued characters include both real and quaternionic representation types; the criterion concerns values of the characters, not those two representation types separately.
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 19G iii Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14The matrix is square by completeness. Column orthogonality says . Taking determinants givesIn particular its determinant is nonzero.
Past exam of the mathematics course of the University of Cambridge 2005 ii Paper 2 19G ii Solution by Codex 0 Created 2026-09-24 Updated 2026-10-14
Codex 0 Created 2026-09-24 Updated 2026-10-14Apply completeness to the indicator of the conjugacy class of . Its expansion coefficient is , because that class has size . Evaluating at givesThe complex conjugation is part of the printed formula; dropping it would not give the general column orthogonality relation.
Pinned article: Introduction to the OurBigBook Project
Welcome to the OurBigBook Project! Our goal is to create the perfect publishing platform for STEM subjects, and get university-level students to write the best free STEM tutorials ever.
Everyone is welcome to create an account and play with the site: ourbigbook.com/go/register. We belive that students themselves can write amazing tutorials, but teachers are welcome too. You can write about anything you want, it doesn't have to be STEM or even educational. Silly test content is very welcome and you won't be penalized in any way. Just keep it legal!
Intro to OurBigBook
. Source. We have two killer features:
- topics: topics group articles by different users with the same title, e.g. here is the topic for the "Fundamental Theorem of Calculus" ourbigbook.com/go/topic/fundamental-theorem-of-calculusArticles of different users are sorted by upvote within each article page. This feature is a bit like:
- a Wikipedia where each user can have their own version of each article
- a Q&A website like Stack Overflow, where multiple people can give their views on a given topic, and the best ones are sorted by upvote. Except you don't need to wait for someone to ask first, and any topic goes, no matter how narrow or broad
This feature makes it possible for readers to find better explanations of any topic created by other writers. And it allows writers to create an explanation in a place that readers might actually find it.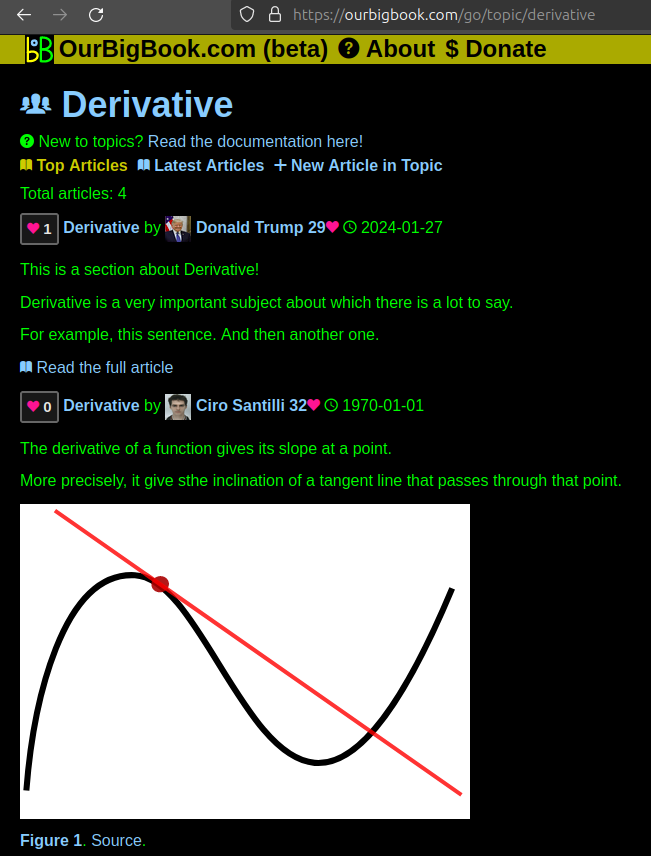
Figure 1. Screenshot of the "Derivative" topic page. View it live at: ourbigbook.com/go/topic/derivativeVideo 2. OurBigBook Web topics demo. Source. - local editing: you can store all your personal knowledge base content locally in a plaintext markup format that can be edited locally and published either:This way you can be sure that even if OurBigBook.com were to go down one day (which we have no plans to do as it is quite cheap to host!), your content will still be perfectly readable as a static site.
- to OurBigBook.com to get awesome multi-user features like topics and likes
- as HTML files to a static website, which you can host yourself for free on many external providers like GitHub Pages, and remain in full control

Figure 2. You can publish local OurBigBook lightweight markup files to either OurBigBook.com or as a static website.
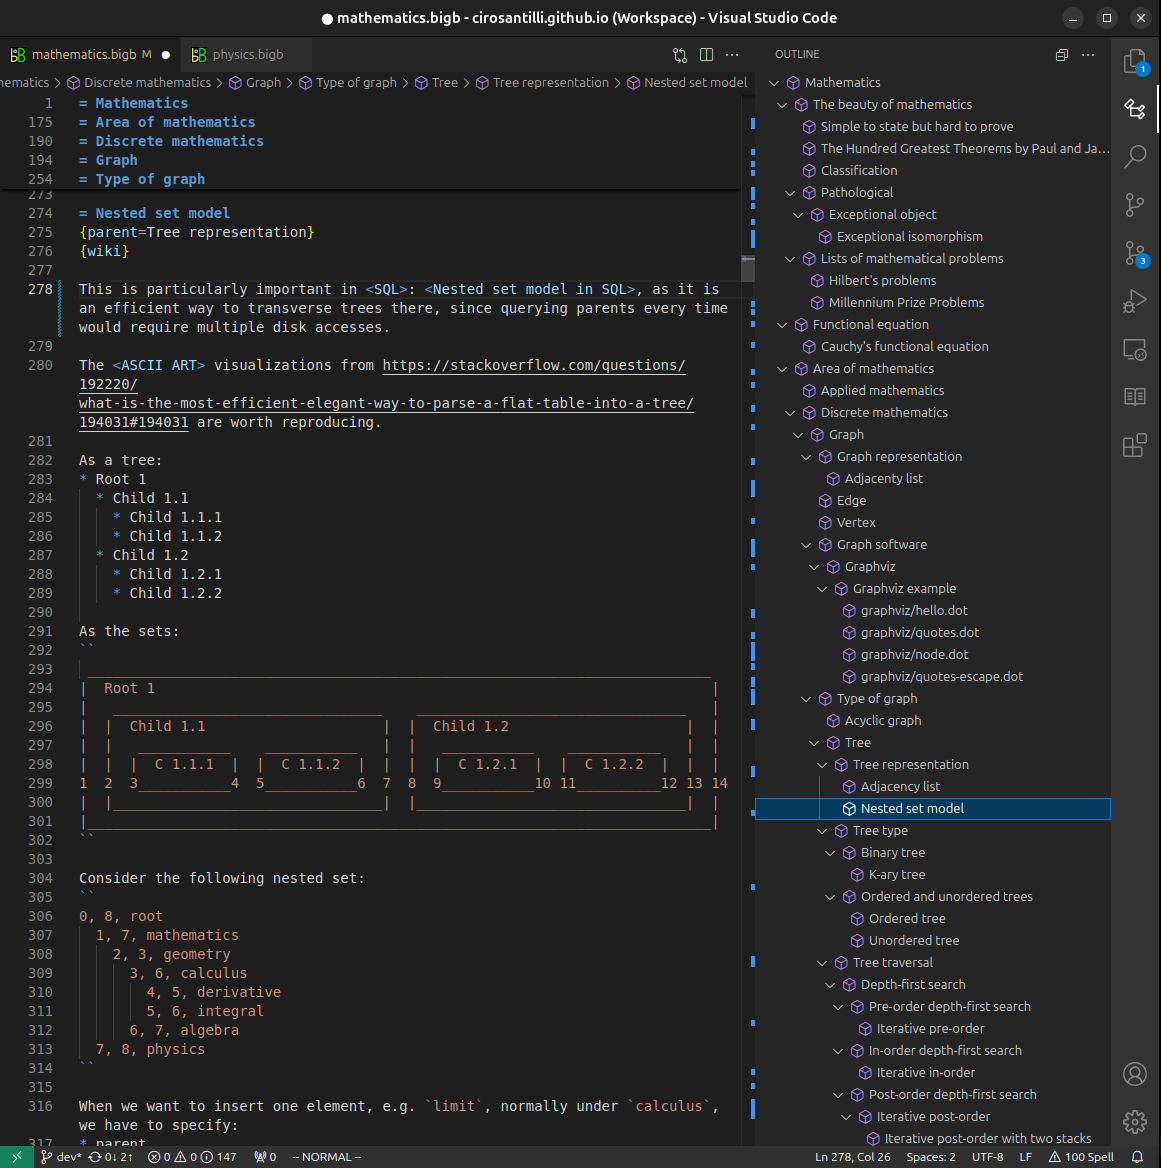
Figure 3. Visual Studio Code extension installation.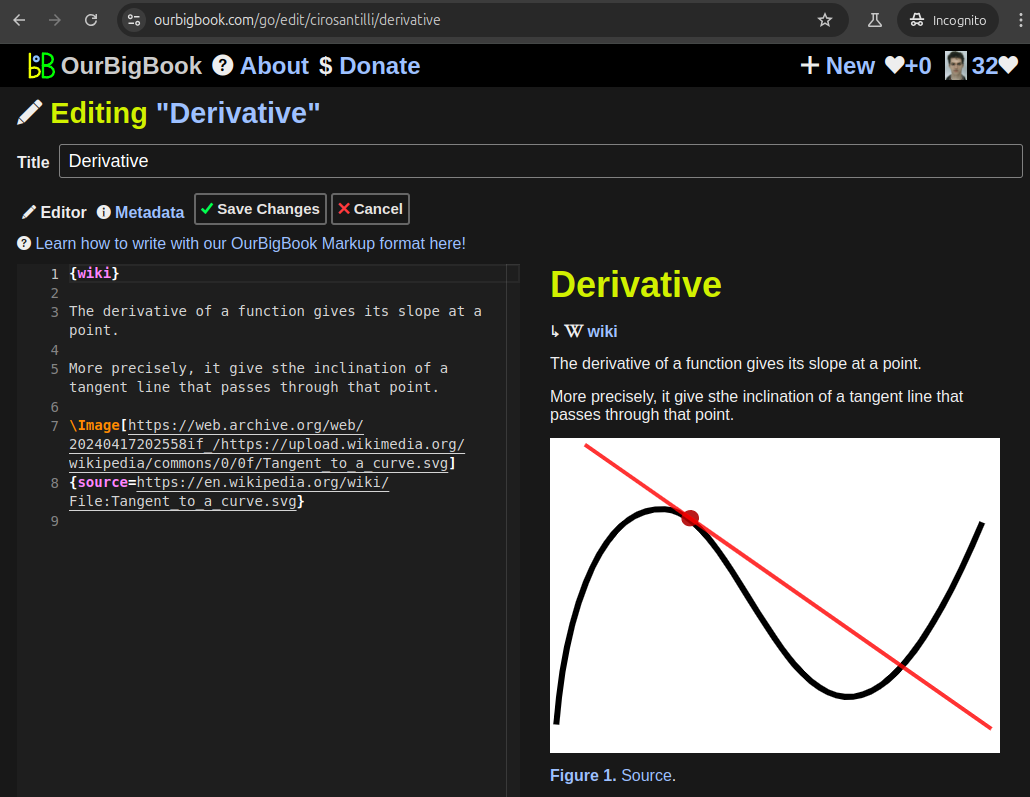
Figure 5. . You can also edit articles on the Web editor without installing anything locally. Video 3. Edit locally and publish demo. Source. This shows editing OurBigBook Markup and publishing it using the Visual Studio Code extension. 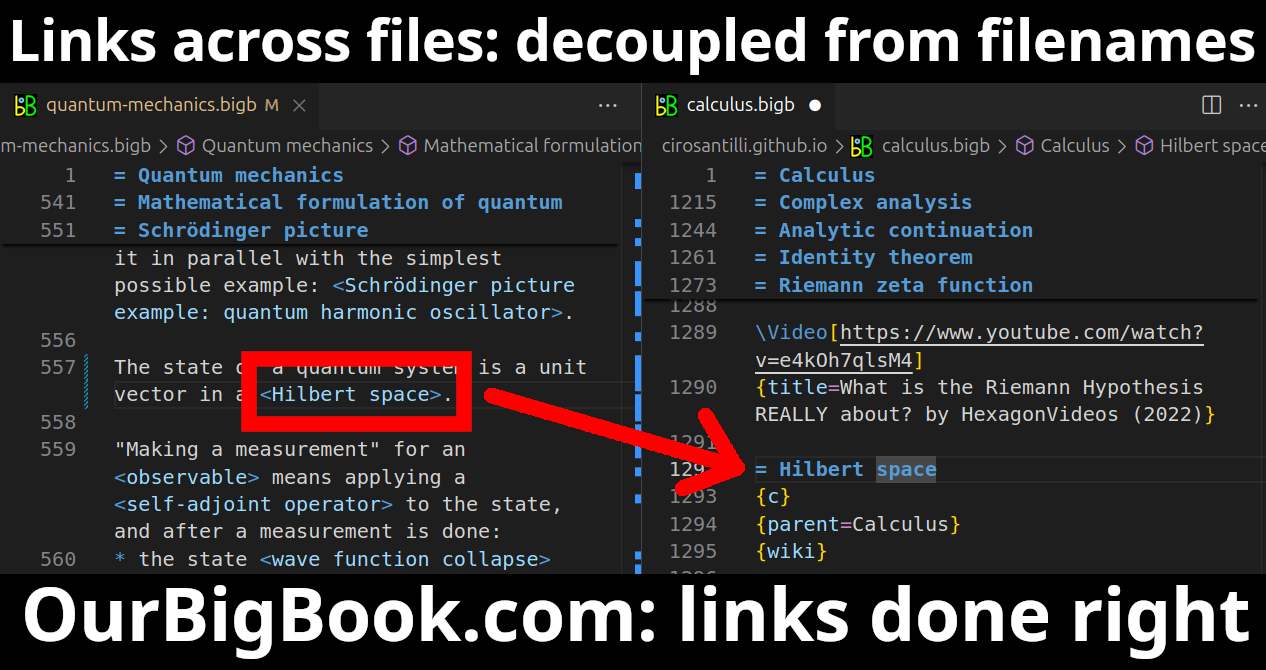
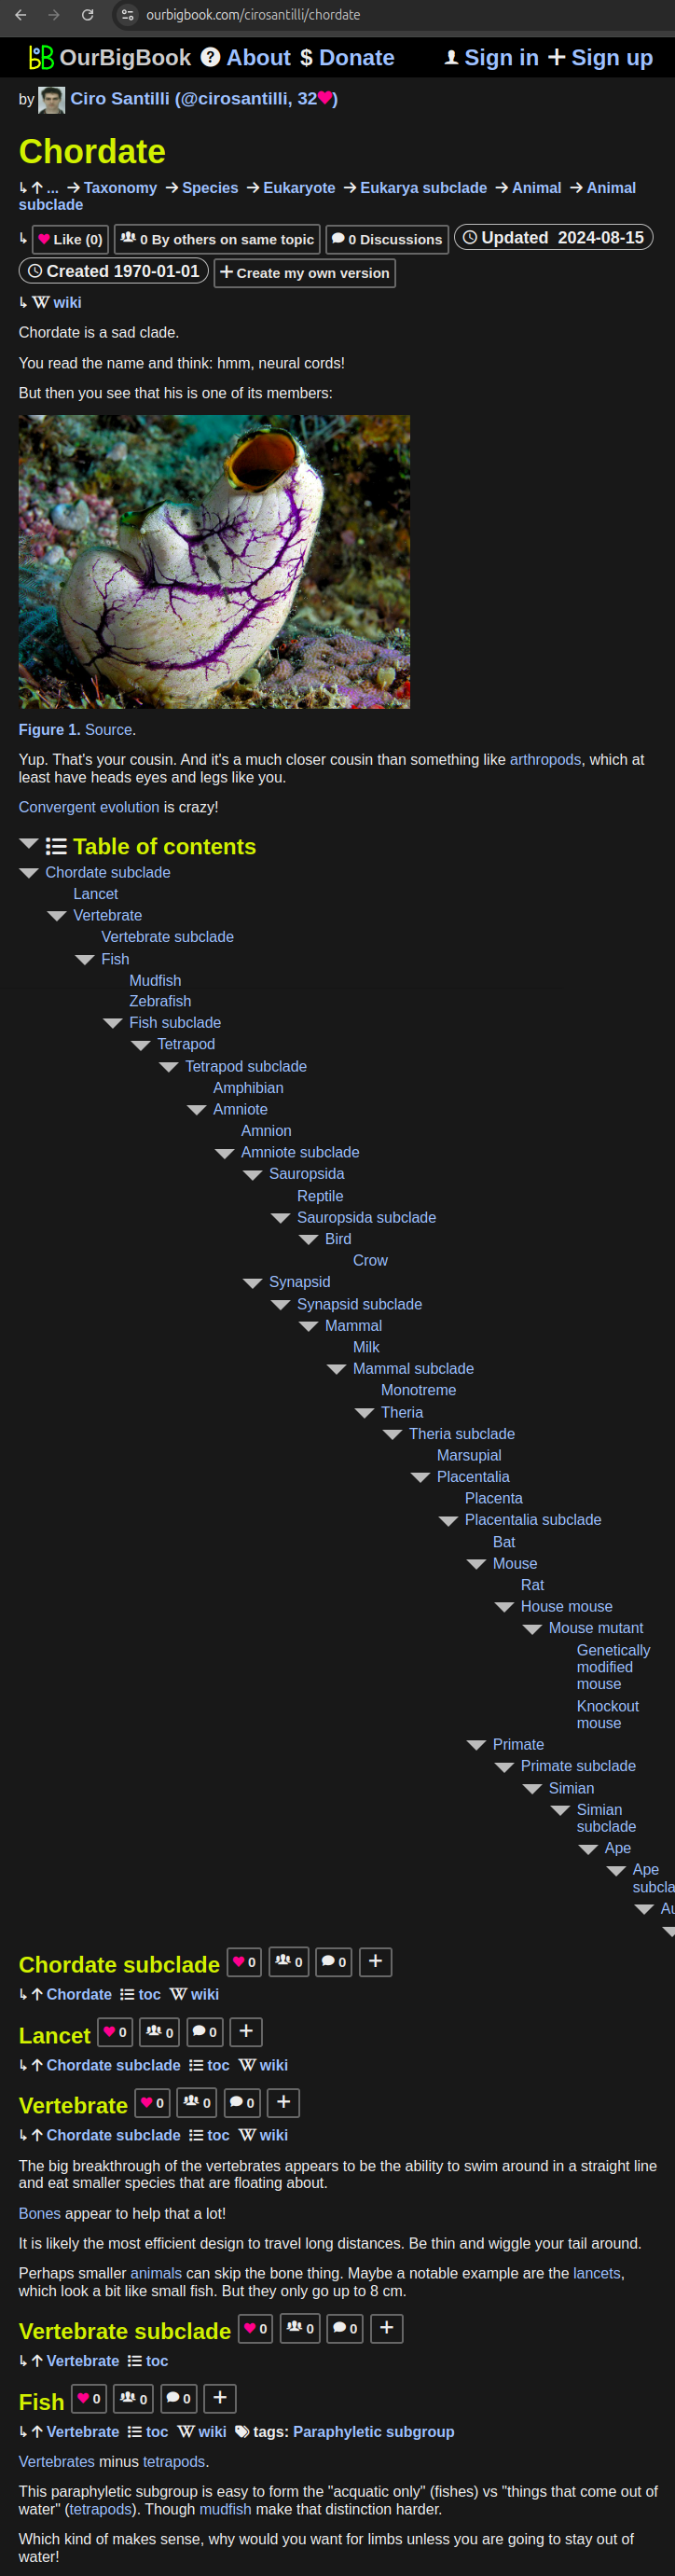
- Infinitely deep tables of contents:
All our software is open source and hosted at: github.com/ourbigbook/ourbigbook
Further documentation can be found at: docs.ourbigbook.com
Feel free to reach our to us for any help or suggestions: docs.ourbigbook.com/#contact