Topics (318k) Articles (329k) Users (382) Discussions (237) Comments (383) Files (10k) New article
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 39 3 Solution by  Codex 0 Created 2026-10-03 Updated 2026-10-14
Represent the raindrops by a Poisson random measure on the space of location, impact time and volume. Physical volume is nonnegative, so take the intensity density to vanish for , or equivalently work on and extend it by zero to . Assume the radius function is measurable and nonnegative for elapsed times at least zero. Its stated monotonicity means patches grow rather than dry away.
A drop contributes to wetting at time precisely if its impact time is no later than and its current patch contains . Thus define the deterministic measurable setThe number of covering drops is . Its intensity measure of a point process isSince the point is dry if and only if that count is zero, the Poisson count definition gives the void probability for growing Poisson rain patchesHere : when the intensity is infinite, exhaust the covering set by increasing finite-intensity sets; their decreasing zero-count events have probabilities tending to zero. This also covers storms with infinitely many drops that can reach the point. The formula is valid for spatially inhomogeneous intensity. Only if the intensity is spatially constant may the spatial integral be replaced by times that intensity. Whether the circular boundary is included makes no difference for a density with respect to Lebesgue measure, since each such boundary has zero spatial area. This construction is a time-dependent Poisson germ-grain model.
For total rainfall, the required general result is the Campbell first-moment formula: if is a Poisson random measure with intensity and is any nonnegative measurable function, thenwith infinite values permitted. For a signed , it holds with finite absolute expectation whenever . No square-integrability hypothesis is required for this first-moment identity. The result is stated rather than proved, as allowed here.
The total rainfall volume is , counting every drop once, independently of overlaps between its patch and other patches. Apply the stated formula with on the physical mark space. Extending by zero to negative volume givesIf the displayed nonnegative integral is finite, the total volume is integrable and finite almost surely. If it is infinite, its expectation is infinite; this alone does not imply that the random total is infinite almost surely. The radius affects wet-area coverage but does not change this total-volume expectation.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 39 2 Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14The first limit in the PDF has a reciprocal error when denotes point density. The correct strong law for Poisson arrival times isTo prove it, put . The unit-interval increments are independent and identically distributed random variables with the Poisson distribution of mean . The strong law of large numbers gives along integers. For ,so for all real . The continuous intensity gives distinct points almost surely, and local finiteness and infinitely many points give . Since , the same pathwise limit along implies , proving the reciprocal limit. For instance at density the limit is , not . The printed limit would instead describe a parameter interpreted as mean interarrival time, but not the stated density.
For the Non-homogeneous Poisson point process on , every closed subinterval strictly inside has finite intensity. The intensity is non-atomic, so the process is simple and has no point at almost surely. Both half-intervals have infinite intensity: the density behaves as at zero and as at one. More explicitly, exhaust either half by finite-intensity intervals of means . For any fixed integer ,Thus there are infinitely many points on each side.
Local finiteness around gives a last point on its left and a first point on its right. To see the former directly, choose any left point; between it and there are only finitely many points, so there is a largest one. Repeat below each chosen point to label the left sequence by , and similarly label the right sequence by . No infinite sequence of points can accumulate in the interior, because a compact neighbourhood there has finite count. ConsequentlyThis constructs the required two-sided order statistics of a boundary-singular Poisson process.
Use its integrated intensity to find the rates. Partial fractions giveThe left cumulative-intensity coordinate isIt maps the left half bijectively onto , reversing its order. The image points form a unit-rate Poisson process directly from the count definition: inverse images of disjoint parameter intervals are disjoint, and their intensity equals their parameter lengths. In particular is its th arrival, so the result just proved gives . Also as , because . HenceThis is exactly the requested negative-index limit.
For the right side, the increasing coordinate isIts image is another unit-rate Poisson process; is the st arrival because the first right point has index zero. Thus . As ,Combining these facts gives the positive-index asymptoticsEquivalently almost surely. In particular for every fixed , unlike the inverse-linear scale at the left endpoint.
There is also an exact distributional description, if desired. For , means that at most right-hand points precede , soThus has the gamma distribution with shape and rate one. This makes the indexing shift explicit and describes the fluctuations left unspecified by the logarithmic limit.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 39 1 Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Equip with a sigma-algebra . A Poisson random measure with intensity measure of a point process is a random counting measure such that, for every measurable with ,and the counts on every finite collection of pairwise disjoint measurable sets are independent. Thus . For a sigma-finite measure , sets of infinite intensity contain infinitely many points almost surely: exhaust such a set by increasing finite-intensity sets and use the Poisson count tails as their means tend to infinity. The count is a measurable random variable for every measurable , which is part of saying that is a random measure.
Under the usual point representation write , counting multiplicities. If is a non-atomic measure, this is a simple Poisson point process; if has atoms, several point occurrences can have the same location, and each occurrence is counted separately. In a topological setting, local finiteness requires that the intensity be finite on compact sets.
Sufficient existence conditions are that is a standard Borel space and is a sigma-finite measure. This gives existence of a Poisson random measure on a standard Borel space. If a simple locally finite configuration is desired, additionally take a non-atomic, locally finite intensity on a locally compact second-countable Hausdorff space. These conditions are sufficient, not claimed necessary. In particular sigma-finiteness suffices for a countable family of occurrences that can each be independently coloured.
Let and be the red and green counting measures. The marking assumption means that, conditional on , the colours of all point occurrences are independent, with the same red probability . For a measurable set of finite intensity , condition on its total count. To obtain red and green points the total must be , so direct multiplication gives the joint red and green Poisson count formulaThus the two counts are independent Poisson variables with respective means and . This computation includes zero intensity with the usual convention for the probability of zero counts.
For disjoint finite-intensity sets , the original counts are independent. Conditional marking in different sets uses disjoint collections of independent colours. Repeating the preceding calculation therefore givesThis proves the disjoint-count definition for each coloured Poisson point process and independence of their two count vectors.
To obtain independence of the whole processes, take any finite list of red test sets and any finite list of green test sets, initially all of finite intensity. Refine their union into the disjoint cells given by their membership patterns. Every test-set count is the sum of the counts of its cells. The entire red cell vector is independent of the entire green cell vector by the product formula, hence so are the corresponding test-set count vectors. For arbitrary measurable test sets, intersect first with a finite-intensity exhaustion of and pass to the increasing count limits. The count cylinder events generate the two evaluation sigma-algebras, and independence extended from generating pi-systems gives independence of those sigma-algebras. ConsequentlyThis is a direct count proof of the Poisson thinning theorem; no general marking or thinning result has been used to deduce it.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 38 6 Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14At the unscaled state , write the Lévy kernel of a Markov jump process on jump displacements asThe destination-kernel convention translates each Dirac mass by . The total holding rate is the mass of this kernel. At either zero population the corresponding death rates vanish, so no negative states are reached. Births in the total population are bounded by a Yule process with per-individual rate , while deaths only decrease it; this also gives nonexplosion.
Put . This is a density-dependent Markov jump process, with jumps of size and rates of order . Its drift gives the deterministic approximationUniqueness preserves the diagonal . For positive , the resulting logistic differential equation has solutionIf , it decreases from one to ; if , it increases to that same equilibrium; equality gives the constant solution one. In particular positive rates do not give extinction on this exactly symmetric deterministic trajectory. Transverse perturbations behave differently: subtracting the equations gives , so the positive symmetric equilibrium has an unstable difference direction. The symmetric competition model distinguishes diagonal logistic relaxation from this symmetry-breaking instability.
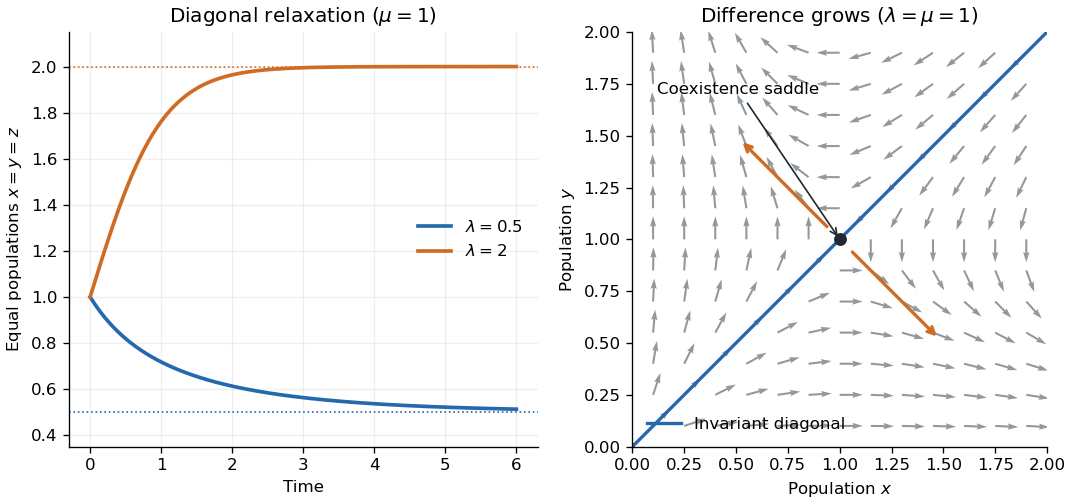
Symmetric population relaxation and transverse instability
. Details. For an explicit error estimate, use the martingale decomposition of a density-dependent jump process:Fix and choose . Stop at the first exit from the box . On that box, has Lipschitz constant in the supremum norm. Each coordinate of has jumps bounded by and predictable quadratic variation at mostIndeed a coordinate's positive and negative jump rates are and , and the squared jump size is . Independent jump clocks give zero cross-bracket.
The Bernstein bound for bounded-jump martingales gives, for each coordinate,The Gronwall inequality applied up to givesAn exit from the box already entails an error larger than , by the choice of , so the stopped estimate controls the event of any error on the full interval. Take and use the union bound on the two coordinates:For fixed time horizon and tolerance this is exponentially small in , proving a fluid limit. The transverse instability explains why this finite-horizon estimate should not be extrapolated to arbitrarily long times without changing its constants.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 38 5 Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Write the diffusion process as , with . Its diffusion generator isThe Itô formula says that is a local martingale, and is a true martingale when the stopped terms are integrable. Taking expectations gives Dynkin formula for a diffusion. This is the bridge from infinitesimal stochastic dynamics to differential equations.
For the transition semigroup , the Markov property gives . On a smooth generator domain where differentiation is valid, differentiating the semigroup identity yields the Kolmogorov backward equation , with initial value . If a transition density exists, integration against smooth compactly supported tests and integration by parts give the Fokker-Planck equationThe backward equation acts on the starting point, while this forward equation describes the evolving probability density.
Here is a full representation proof with a source and potential. Suppose is nonexplosive, is bounded, are bounded, and is a bounded classical solution on a finite slab ofFor a process started from at time , put . The Itô product rule givesTherefore is a local martingale. It is bounded in absolute value by , so it is a true martingale, without requiring a global derivative bound. Its endpoint expectations give the parabolic Feynman-Kac formula with a sourceThis proves uniqueness in the bounded classical class. Setting recovers the backward heat or diffusion representation; the minus sign in the killing term produces the negative exponential.
For an elliptic problem, stop at the first exit from a bounded regular domain . Suppose , is bounded and solves with boundary data . The same calculation, stopped at , gives a martingale dominated by . Continuity puts on the boundary. Taking the limit and using dominated convergence gives the elliptic Feynman-Kac formulaFor , harmonic functions for give stopped martingales and are averages of their exit-boundary values. For Brownian motion , this is the probabilistic solution of the Dirichlet problem. Suitable smooth coefficients and uniform ellipticity give familiar settings where the required diffusion, exit-time integrability and classical solutions exist. The representation itself follows from the stated regularity and integrability conditions, rather than claiming classical solvability for arbitrary coefficients.
Pinned article: Introduction to the OurBigBook Project
Welcome to the OurBigBook Project! Our goal is to create the perfect publishing platform for STEM subjects, and get university-level students to write the best free STEM tutorials ever.
Everyone is welcome to create an account and play with the site: ourbigbook.com/go/register. We belive that students themselves can write amazing tutorials, but teachers are welcome too. You can write about anything you want, it doesn't have to be STEM or even educational. Silly test content is very welcome and you won't be penalized in any way. Just keep it legal!
Intro to OurBigBook
. Source. We have two killer features:
- topics: topics group articles by different users with the same title, e.g. here is the topic for the "Fundamental Theorem of Calculus" ourbigbook.com/go/topic/fundamental-theorem-of-calculusArticles of different users are sorted by upvote within each article page. This feature is a bit like:
- a Wikipedia where each user can have their own version of each article
- a Q&A website like Stack Overflow, where multiple people can give their views on a given topic, and the best ones are sorted by upvote. Except you don't need to wait for someone to ask first, and any topic goes, no matter how narrow or broad
This feature makes it possible for readers to find better explanations of any topic created by other writers. And it allows writers to create an explanation in a place that readers might actually find it.
Figure 1. Screenshot of the "Derivative" topic page. View it live at: ourbigbook.com/go/topic/derivativeVideo 2. OurBigBook Web topics demo. Source. - local editing: you can store all your personal knowledge base content locally in a plaintext markup format that can be edited locally and published either:This way you can be sure that even if OurBigBook.com were to go down one day (which we have no plans to do as it is quite cheap to host!), your content will still be perfectly readable as a static site.
- to OurBigBook.com to get awesome multi-user features like topics and likes
- as HTML files to a static website, which you can host yourself for free on many external providers like GitHub Pages, and remain in full control

Figure 2. You can publish local OurBigBook lightweight markup files to either OurBigBook.com or as a static website.
Figure 3. Visual Studio Code extension installation.
Figure 5. . You can also edit articles on the Web editor without installing anything locally. Video 3. Edit locally and publish demo. Source. This shows editing OurBigBook Markup and publishing it using the Visual Studio Code extension. 
- Infinitely deep tables of contents:



All our software is open source and hosted at: github.com/ourbigbook/ourbigbook
Further documentation can be found at: docs.ourbigbook.com
Feel free to reach our to us for any help or suggestions: docs.ourbigbook.com/#contact