Suppose has an absolutely continuous probability distribution, with survival function . On an interval where , its cumulative hazard isHere is the hazard function; its integral is dimensionless because the units of rate and time cancel. The identity follows by integrating the derivative of , so mere continuity of the survival function is not enough: the absolute continuity assumption supplies a probability density function. If reaches zero, interpret as . The normalization also matters; an initial probability mass at zero would require an initial term .
Accumulating hazard functions adds on the scale and multiplies survival factors on the scale. For and ,For instance, a cumulative hazard increment of gives event probability , rather than a probability of . With per year, and . With the increasing hazard function per year when is expressed in years, , so gives . Its coefficient has units of inverse years squared.
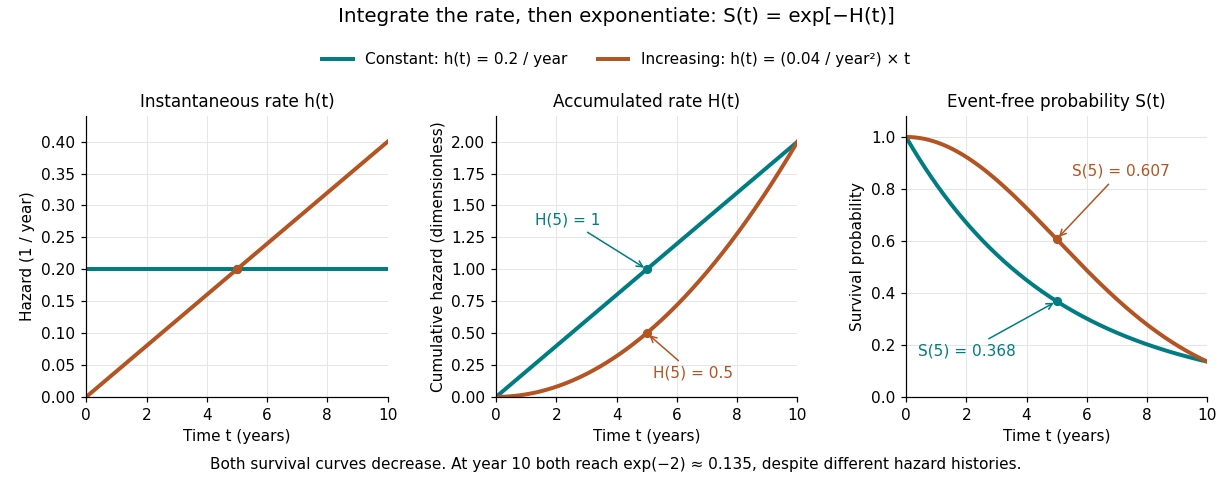

The constant hazard function produces an exponential distribution; the increasing example is a Weibull distribution. Their survival functions both decrease, although one hazard function stays constant and the other increases. At year ten both have and despite different earlier histories. The accumulation identity is described in Lu Tian's Stanford notes, Section 1.1.
For a discrete hazard at each possible event time , the exact counterpart is . Taking its negative logarithm sums , rather than . Therefore exponentiating a Nelson–Aalen estimator does not give exactly the Kaplan–Meier estimator; small-jump comparison of cumulative hazard estimators quantifies the difference.
Let , , and suppose and are independent, with continuous failure density . Then the Tonelli theorem givesThus has mean zero. The identity also holds conditionally on covariates when censoring is independent conditionally on them. For an estimated hazard, the mean error is controlled by , not by pointwise fit alone.
// Target: survival-analysis.bigb
For a nonnegative continuous event time with survival function S, hazard function h and H the cumulative hazard, split the expectation at c. The censored contribution is S(c)H(c). The event contribution is by integration by parts, since and . Adding gives the displayed identity. Linearity extends it to the expected observed event count in a cohort, without requiring independence between subjects.
For a proper continuous event time and invertible cumulative hazard function , the survivor function identity gives .
Articles by others on the same topic
There are currently no matching articles.