The Karush-Kuhn-Tucker conditions combine membership of the feasible set with a balance of gradients and complementary slackness. For a minimization problem with differentiable functions on an open subset of , writeand use the optimization LagrangianA candidate satisfies the KKT conditions exactly when all four requirements hold:
- Primal feasibility: and , so is a feasible point.
- Dual sign feasibility: . The equality Lagrange multipliers are unrestricted real numbers.
- Stationarity: the gradient of the optimization Lagrangian in the decision variables vanishes,
- Complementary slackness: for every inequality optimization constraint.[ref]Lecture 7: Lagrange Multipliers and KKT Conditions. Lecture 7, §L7.1.1, Definition L7.1, printed p. 3: the four KKT requirements
The sign of each inequality Lagrange multiplier follows the chosen convention : on the feasible set, makes the optimization Lagrangian a lower bound on the objective function. An equality contributes zero on the feasible set for either sign of its Lagrange multiplier. Complementary slackness says an inequality with must have , while implies an active constraint. An active constraint can still have zero Lagrange multiplier; the quadratic minimization with a moving upper bound below gives an explicit example.
The name records William Karush's 1939 master's thesis and the 1951 work of Harold W. Kuhn and Albert W. Tucker.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. Chapter 5 bibliography, printed p. 272, and bibliography entries KT51 and Kuh76
A KKT point is a feasible point admitting Lagrange multipliers that satisfy the Karush-Kuhn-Tucker conditions. Some authors use the name for the full primal and multiplier pair; specify the multipliers when this distinction matters. For a convex optimization problem with a differentiable convex function as its objective function, convex inequality functions and affine equality constraints, the KKT conditions certify a global minimizer. Their necessity requires an appropriate constraint qualification.
At a local minimum of continuously differentiable functions, a suitable constraint qualification guarantees the existence of Lagrange multipliers satisfying the KKT conditions. One sufficient local regularity assumption is that the gradients of the equality optimization constraints and the active constraints are jointly linearly independent. This assumption concerns the description of the feasible set, not just the smoothness of the objective function.[ref]
Lecture 7: Lagrange Multipliers and KKT Conditions. Lecture 7, §L7.1.3, Theorem L7.3, printed p. 4: continuous differentiability and independent active gradients
To see why a hypothesis is needed, minimize subject to . The feasible set is the singleton , so is a global minimum. Yet for every finite Lagrange multiplier . Thus this convex optimization problem has an attained optimum without a KKT multiplier. The zero gradient of the active constraint has hidden the actual restriction from its first-order equation. Rewriting it as the equality yields the unrestricted Lagrange multiplier .
For convex optimization, Slater's condition requires strict inequalities and affine equalities at a point in the relative interior of the common domain of a function. A finite optimum value then gives strong duality and dual attainment. Primal attainment and differentiability yield KKT multipliers. Affine inequalities may be nonstrict in the refined version.[ref]
Slater's condition is sufficient, and need not hold for an optimum to exist. The singular example above also shows that mere primal attainment is not a substitute for a constraint qualification.
For differentiable functions that are convex functions on an open convex set and affine functions , the KKT conditions certify a global minimum. Once Lagrange multipliers satisfy them, no extra Slater condition is needed.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. §5.5.3, printed p. 244: sufficiency under convexity and affine equalities
The certificate is a short chain of inequalities. Nonnegative Lagrange multipliers and affine equalities make a convex function. Its zero gradient gives a global minimum at by the first-order optimality condition. For every feasible point ,The first equality uses feasibility and complementary slackness; the last inequality uses and . Equivalently, the Lagrange dual function attains the same value as the primal objective function, proving strong duality. A strictly convex function makes the primal optimum unique, although the Lagrange multipliers need not be unique.
Affine equality optimization constraints matter: an arbitrary signed multiple of a nonlinear equality can destroy convexity of the optimization Lagrangian. For example, minimizing subject to the affine equality gives and for . This equality Lagrange multiplier is positive for , zero at , and negative for . Completing the square gives the certificate for every real number .
Outside convex optimization, KKT stationarity alone does not certify an optimum: minimizing with no optimization constraints gives the stationary candidate , which is a global maximum. The Lagrangian sufficiency theorem remains applicable whenever a global minimum of the optimization Lagrangian can be proved directly.
Consider the minimization problemThe objective function is a strictly convex function with its unconstrained optimization minimum at . If , it decreases throughout the feasible set until the bound is reached. If , the feasible set already contains . HenceWith , the optimization Lagrangian and KKT conditions areSubstituting gives the unique inequality Lagrange multiplierFor , the active constraint has . For , there is strict slack and . At , the active constraint has zero Lagrange multiplier: the boundary happens to pass through the unconstrained optimum. Feasibility and complementary slackness must both be checked; solving only would allow infeasible candidates.
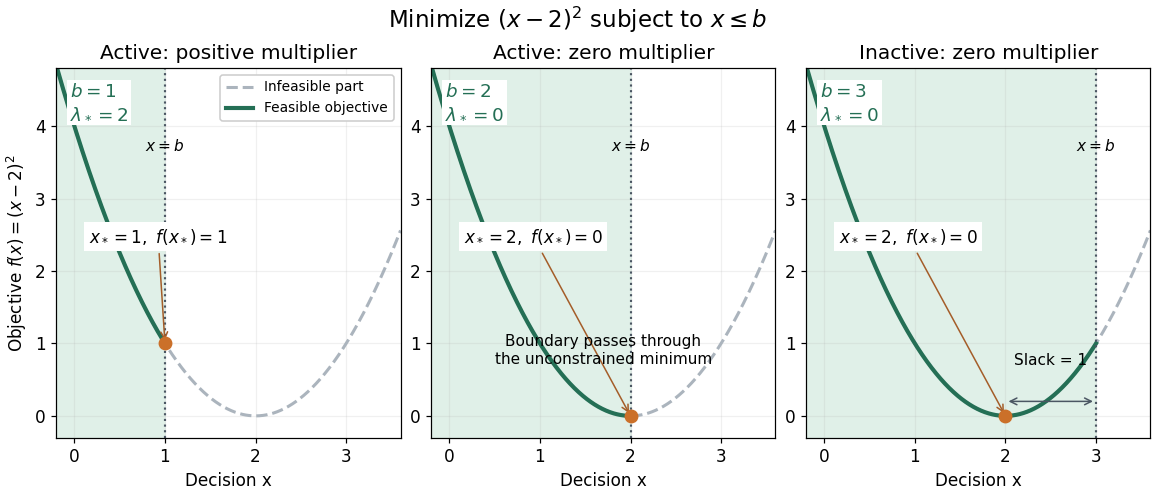
The same quadratic objective with active, just-touching and inactive upper bounds
. Details. An independent certificate follows by completing the square:The Lagrange dual function is a concave function of . Its maximum over occurs at and equals . Thus every case has an explicit lower bound attained by a feasible point; the KKT conditions provide a certificate that can be checked without searching all real numbers.
A shadow price measures the marginal improvement from relaxing an inequality optimization constraint. Use for in a minimization problem. With strong duality and a differentiable optimal value function, .[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. §5.6.3, printed pp. 251–252, equation (5.58): local sensitivity
In the quadratic minimization with a moving upper bound, direct differentiation givesThe derivative at is zero from both sides, although has different one-sided derivatives there. The value of additional room has faded continuously to zero just as the active constraint stops restricting the optimizer.
At , , and . Raising the bound to lowers the value to : the first-order prediction is a change of , while the exact change is . At , the same relaxation leaves and . At , tightening by costs , a second-order effect despite the zero Lagrange multiplier.
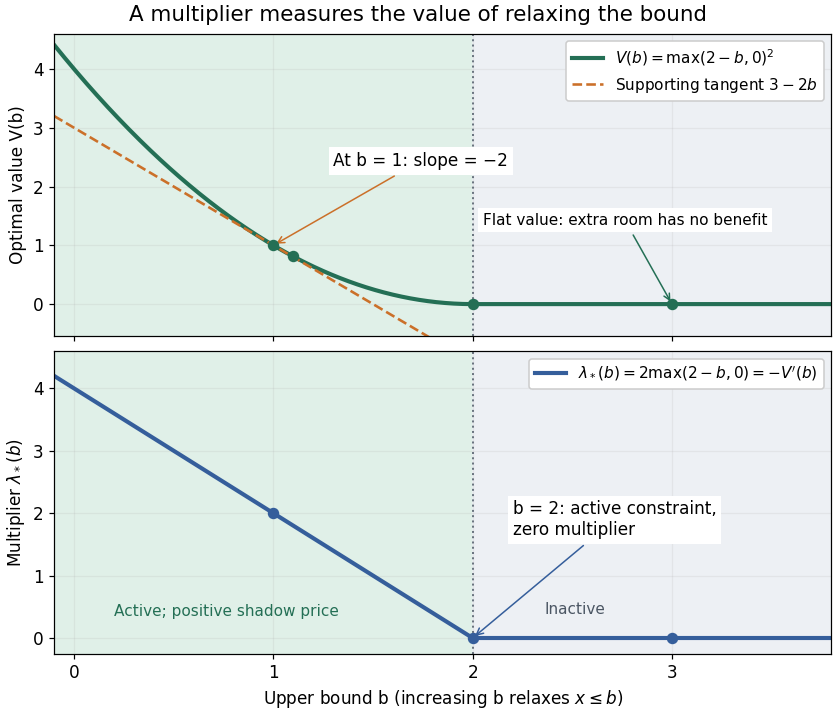
The derivative of the optimal value is the negative inequality multiplier
. Details. There is also a global statement in this example. Keeping the Lagrange multiplier at the value associated with , the Lagrange dual function changes by . Weak duality therefore givesAt this is , the supporting tangent shown in the diagram. This bound remains valid for large changes, whereas the derivative predicts only the first-order effect. If the value function is not differentiable, an optimal Lagrange multiplier can instead supply a supporting subgradient, rather than a unique marginal rate. This is the same idea used in sensitivity analysis in convex perturbation duality.
Articles by others on the same topic



The Karush–Kuhn–Tucker (KKT) conditions are a set of necessary conditions for a solution to be optimal for a constrained optimization problem. They are widely used in mathematical optimization, particularly in nonlinear programming. The KKT conditions generalize the method of Lagrange multipliers to handle problems with inequality constraints.