A convex set permits every intermediate mixture of two of its points. If two choices meet its constraints, continuously averaging them also meets those constraints. This geometric property makes many feasible regions easier to explore: there is no forbidden gap along a straight move between feasible choices.
Formally, a subset of a real vector space is convex whenThe parameter traverses the entire line segment, including both endpoints. The definition does not require a closed subset, a bounded set, or a nonempty interior. The empty set, the whole vector space, and every affine subspace are convex; an open unit disk and a closed unit disk are both convex.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. §2.1.4, pp. 23–25: convex sets and finite convex combinations
The triangle inequality verifies the disk example directly: if , then . For the open disk, the last inequality is strict. The unit circle fails the same test: and belong to it, but their midpoint does not. A curved route along the unit circle connects the endpoints, so being path-connected is weaker than being a convex set.
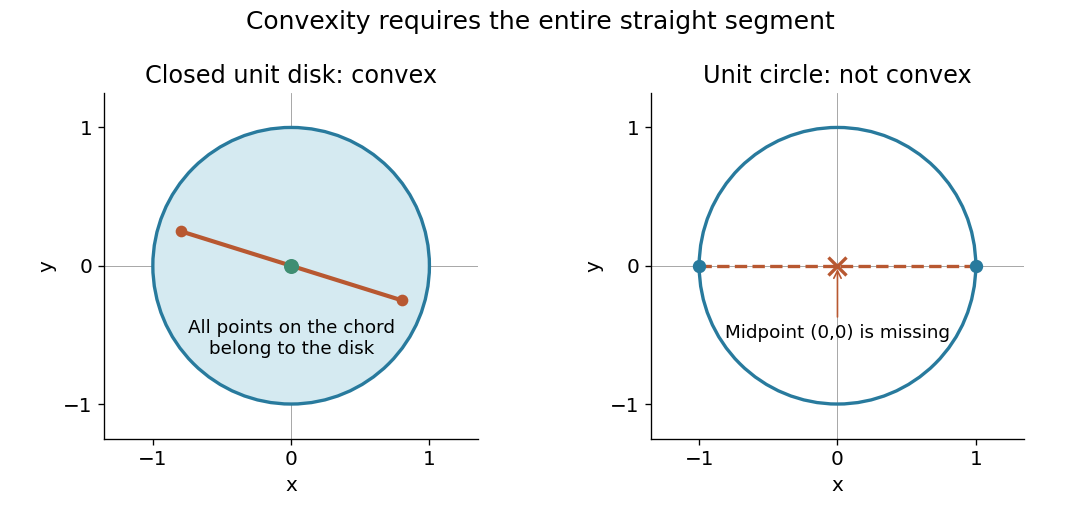
The distinction between a convex set and a convex function matters. The former concerns where one may choose a point; the latter concerns how a value changes along line segments. Convex optimization combines both: averaging preserves feasibility, and a convex function obeys an upper bound by the corresponding average of endpoint values. A convex set alone does not make an arbitrary objective a convex function or eliminate its inferior local minima.
Consider a stipulated continuous-allocation problem. Amounts of two activities use units of a common resource, with budget six. The feasible regionis a triangle with extreme points , and . It is the intersection of three closed half-spaces, hence a closed convex set. The general intersection argument is short: a line segment between two points in every constraint set belongs to every constraint set, so it belongs to their intersection.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. §2.2.1, p. 27: half-spaces; §2.3.1, p. 36: intersections preserve convexity
For an original numerical check, take and . Their resource totals are and . Every convex combination is nonnegative and has resource totalIn particular the midpoint is , using units. This verifies the full line segment, rather than just a plotted sample of it.
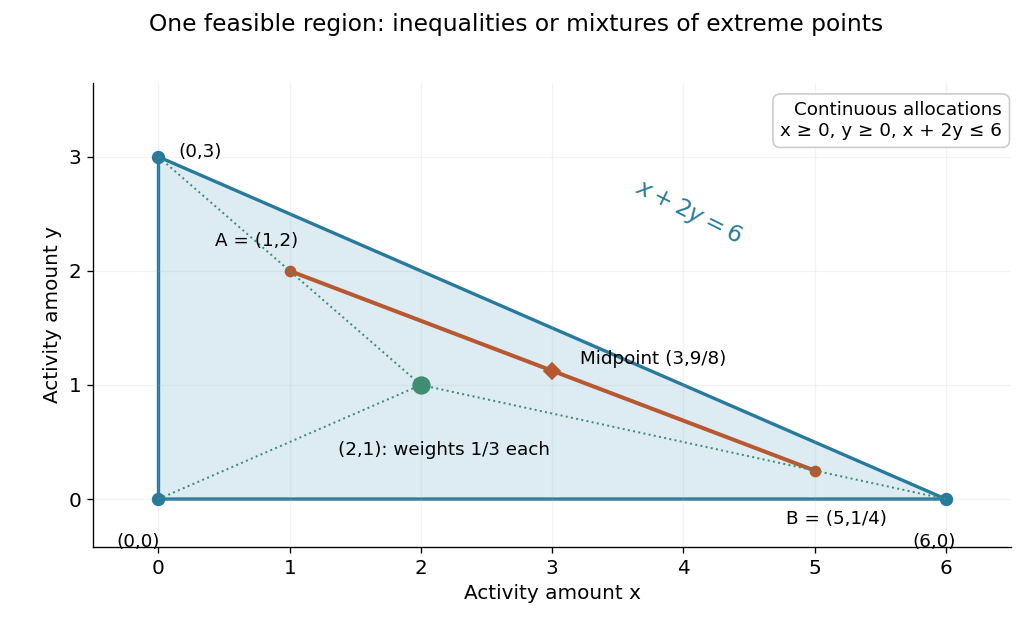
This is useful whenever divisible quantities share linear limits: the feasible choices remain compatible under averaging. A new linear equation also preserves this property, because averaging two identical constraint values gives the same value. The affine subspace and closed half-space viewpoints explain this without requiring a separate argument for every budget.
If the amounts in the budget example must be integers, the actual feasible region is . Both and are feasible, but their midpoint is not. Thus the continuous feasible region is a convex set while the integer-restricted choices are not. Averaging two manufacturing plans may specify half an indivisible item. Integer programming must respect that restriction; using the surrounding convex set is a relaxation, not a proof that its averages are admissible integer plans.
Checking only midpoints is not enough for an arbitrary subset of a real vector space. The rational numbers contain the midpoint of every pair of rational numbers, but the line segment from to also contains irrational numbers. For instance lies on that line segment and is not rational. This shows why the definition quantifies over every real .
There is a useful additional hypothesis: a closed subset containing the midpoint of every pair of its points is a convex set. Repeated bisection includes all points with dyadic rational . These coefficients approach every real ; being a closed subset then includes each limit. This is a short proof outline, and the rational numbers example identifies precisely why a closed subset was required.
A convex set that is also a closed subset in the specified topology. In a Hilbert space with its norm topology, every nonempty closed convex set has a unique nearest point to every ambient vector, by the Hilbert projection theorem.
Two nonempty disjoint convex sets in a finite-dimensional real vector space admit a separating nonzero linear functional: for an appropriate and , on the respective sets. Strict separation requires additional assumptions, such as one set being compact and the other closed. For an open convex cone excluding zero, separation from gives for all ; scaling cone elements forces the separating level to be zero. This finite-dimensional result is related to the supporting hyperplane theorem.
A convex set in a finite-dimensional space has a nonzero supporting linear functional at each boundary point. If zero lies outside a nonempty convex set , weak separation gives with for all , even when zero belongs to its closure. Strict separation needs stronger hypotheses.
The relative interior of a convex set is its interior in its affine span. A polyhedral cone has nonempty relative interior in its linear span, even when its ordinary interior in the ambient vector space is empty.
// Target: geometry-and-topology.bigb
A subset of a real vector space is radially open when, for each and each vector , the points remain in for all sufficiently small real . No ambient topology is required. If is also convex and contains zero, it is absorbing and its Minkowski functional is finite and sublinear, with . Convexity gives subadditivity; radial openness permits a slight dilation of any point of , giving the strict inequality.
A closed convex set in a finite-dimensional Euclidean space is the intersection of all containing closed half-spaces. For a point outside a nonempty set, its Euclidean projection onto a convex set gives a separating normal. Applied to an epigraph, this turns geometric separation into affine lower bounds and is a key step in the Fenchel-Moreau theorem.
The recession cone of a nonempty convex set consists of directions for which for every and . For a linear polyhedron it is exactly . A nonzero recession direction gives an unbounded ray, so a bounded nonempty polyhedron has recession cone . This excludes spurious zero-scale feasible points in the Charnes-Cooper transformation.
A convex set is a face of if , with and , implies . A singleton face is an extreme point. A face of a face is a face of the original convex set.
Let be a nonempty norm-closed face of a convex set in a unital C-star algebra, with . Every has norm one: otherwise is a nontrivial convex decomposition forcing zero into the face. If is continuous and nondecreasing with , then .
To prove this, for replace near the endpoints by a function which is zero on , one on , agrees with on , and interpolates linearly in between. Monotonicity and endpoint continuity give uniformly. With , the function takes values in : check the two constant regions and use elsewhere. The continuous functional calculus gives with both summands positive contractions. The face property gives , and closedness gives .
An exposed face of a convex set is the nonempty set on which a supporting real linear functional attains its maximum. It is a face of a convex set: if with attains the maximum and , each of is at most that maximum, so both equal it. On a complex vector space, take the real part of a complex linear functional. An exposed point is an exposed face consisting of one point.
A compact convex set is a compact set that is also a convex set. If is nonempty, its support function is finite in every direction. For such a nonempty , every exterior point admits a strictly separating hyperplane: minimize over , and put . Convexity and differentiation along the segment from to any give , while . This is the separation used to recover spatial support from Fourier growth.
The nonnegative orthant consists of vectors whose coordinates are all nonnegative. Its interior is the positive orthant, where every coordinate is positive.
A convex combination is a finite weighted average of points in a real vector space. For , it has the formThe nonnegative coefficients forbid subtracting a component, and their unit sum keeps the result on the same affine scale as the inputs. With two points it parametrizes their line segment; equal coefficients give their centroid. A convex set contains every finite convex combination of its points. Conversely, the two-point case already gives the defining property of a convex set.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. §2.1.4, p. 24: finite combinations, weighted-average interpretation and convex hull
The distinction from a linear combination is concrete. Combining and with coefficients and gives , outside their line segment, despite the unit coefficient sum. Using two coefficients both equal to one gives here, but their sum is two, so it is not a convex combination with those coefficients. A numerical output may happen to coincide with a point admitting a different convex representation; the definition applies to the specified coefficients.
Every allocation in the convex feasible region for a resource budget is a convex combination of its three extreme points:The condition is exactly ; nonnegative give the other two nonnegative coefficients. Thus the half-space description and the convex hull description encode the same triangle. At all three coefficients are , and at they are , , . The green and orange points in the budget diagram therefore have two complementary interpretations: direct resource constraints and mixtures of extreme choices.
The three extreme points alone are not a convex set, because their midpoints are absent. Their convex hull fills the whole triangle. More generally, Caratheodory theorem bounds how many generating points are needed for one convex combination in a finite-dimensional real vector space; its geometric content is that a complicated collection can describe each attainable average with a short representation.
If a convex subset of is invariant under cyclic coordinate permutation, averaging the cyclic images of shows thatalso belongs to the set.
This is the non-strict version of a half-space; replacing the inequality by a strict one gives the open version.
The midpoint of the line segment joining two points with position vectors is the point . Its displacements from the endpoints are and , so it lies on the segment and is equidistant from its endpoints. It is also the centroid of the two endpoints.
For line segments and , , the squared Euclidean distance is a convex quadratic function on a square. Its minimum is either an admissible stationary point or a minimum on one of the four edges. Each edge minimum is a point-to-segment orthogonal projection, restricted to the interval. Testing these five candidates gives a complete algorithm; when the directions are parallel, the edge candidates suffice. Independently restricting both coordinates of the unconstrained stationary point is generally incorrect because the variables are coupled by .
For segments with initial direction vectors , initial endpoint displacement , and translation velocities , contact is feasibility of the displayed linear equation with and . Minimizing is a small linear programming problem. A nonsingular three-column coefficient matrix gives at most one candidate; singular, parallel and degenerate cases require the constrained feasibility problem rather than division by a vanishing determinant.
The earliest approach within distance is a convex optimization problem with a norm constraint and the same segment and time bounds as contact. An elementary alternative enumerates whether each segment parameter is free or at an endpoint. In each nonsingular active case the free closest-point parameters are affine functions of time, leaving a quadratic distance inequality on a valid time interval. Rank-deficient cases need their null-space constraints retained. Unlike contact, the two segment parameters and time are no longer determined by a vector equality.
A convex polytope is a bounded intersection of finitely many closed half-spaces, equivalently the convex hull of finitely many points.
A zonotope is a Minkowski sum of finitely many line segments, equivalently an affine map image of a cube. For vectors , the set is the support of the associated box spline. A centred version uses instead. In two dimensions, sums of differently directed segments give centrally symmetric polygons; repeated directions lengthen their corresponding edges without adding new edge directions.
A lattice polytope is the convex hull of finitely many points of a Euclidean lattice. It need not contain the origin. Integral translation changes its associated homogeneous semigroup ring by a grading-preserving isomorphism.
// Target: geometry-and-topology.bigb
A convex polygon is a two-dimensional convex polytope, equivalently the convex hull of a finite planar set with nonempty interior. Its vertices are the extreme points of that hull. Saying that given points form a convex polygon means every specified point is a vertex; points inside the hull or in the interior of a straight boundary segment do not count as vertices.
A strictly convex polygon is a convex polygon whose interior angles are all strictly less than degrees.
For a finite point set in the plane, a convex polygon whose vertices of a polygon belong to the set and whose interior contains no point of the set. The convention must specify whether additional points on the boundary are allowed. A fan triangulation reduces emptiness to tests on constituent triangles, together with checks that internal diagonals contain no forbidden points.
A triangulation of a convex polygon divides a convex polygon into triangles using diagonals between its existing vertices of a polytope, with no diagonal crossings in the interior. For vertices it uses diagonals and produces triangles. Fixing one boundary edge, its adjacent triangle separates two smaller polygon regions; summing over the possible third vertices of a polytope gives the Catalan recurrence. Thus the number of triangulations of a convex polygon is , with the Catalan number. A quadrilateral has two choices and a pentagon has five.
A convex chain between two fixed points inside a triangle is a finite point set whose union with the endpoints forms the vertices of a convex polygon, with the endpoint segment as one boundary edge. In the triangle , with endpoints and , its ordered lower boundary has strictly increasing segment slopes. Every subset of its intermediate vertices remains a convex chain. This hereditary property lets selected point coordinates certify the existence of a long chain.
For independent uniform points in with the two diagonal endpoints, the displayed formula is exact. Order the intermediate points so that both coordinates increase, and write the positive coordinate spacings as and , with each sum equal to one. The two spacing vectors have uniform simplex measure, independently, and the full ordered-coordinate region has volume . Simultaneous permutation of the spacing pairs preserves that measure, so all orders of the ratios have equal volume. Strictly increasing ratios characterize a convex chain and automatically place the intermediate points below the diagonal. Thus its ordered volume is . There are ways to assign labels, and uniform triangle density is , giving the formula. Consequently the first moment method bounds the probability of any length- chain among points by .
For points in a triangle and two fixed endpoint vertices, the longest convex chain length is the largest number of sampled points in a convex chain joining those endpoints. It is a certifiable function: a chain of length supplies a certificate of exactly point coordinates. Changing one point changes the maximum by at most one, since deleting that point from any optimal chain loses at most one vertex. For independent uniform points, its median is and its fluctuation scale about the median is at most , as proved by convex-chain probability in a triangle and convex-chain median concentration.
Let be an integer median for the longest convex chain length of independent uniform points in a triangle. If , fix a certificate of coordinates. Every configuration with must disagree with at least of those coordinates; equal weights prove Talagrand convex distance separation at least . Talagrand's convex distance inequality then gives . Set , then , in the two respective applications to obtain the displayed tails for positive integer . The exact chain-counting bound gives . Hence any interval centred at with length , where , contains with high probability. No upper restriction on the growth of is required.
A vertex of a convex polytope is an extreme point: it cannot be expressed as a nontrivial convex combination of two distinct points in that polytope. In a full-dimensional simple polytope of dimension , a vertex lies on exactly incident facets.
A facet of a full-dimensional convex polytope in is a face of dimension . Each irredundant supporting closed half-space defines one facet.
If and a convex polytope satisfies , then it has at least facets. Its outward facet normals define spherical caps covering the unit sphere; the spherical cap area upper bound supplies the estimate.
The convex hull of the positive and negative coordinate unit vectors. Its boundary triangulates a sphere, and each face contains at most one member of each antipodal pair of coordinate unit vectors. This makes its barycentric subdivision useful for triangulating Real projective space.
An extreme point of a convex set is a point that cannot be made by genuinely mixing two different points of the set. For a convex set in a real vector space, the condition on isThus lies on no open line segment between two distinct points of . It is enough to exclude midpoint representations: if lies inside a line segment, two nearby points on opposite sides have midpoint .[ref]
Convex geometry (BME course BMETE94AM22). §6, Definition 6.6, printed p. 37: extremal points of closed convex sets
The square has just four extreme points, at . In a convex combination giving a corner, each coordinate is already at its largest or smallest allowed value, forcing both input points to agree with that corner. In contrast, the boundary point is not extreme:It is the midpoint of two other points on the same edge. An interior point also admits a small line segment through it.
The unit disk has a different shape: every point on its unit circle is extreme. For a unit vector , the Cauchy-Schwarz inequality givesand equality is possible only at . If a convex combination equals , applying this linear functional forces both ingredients to attain that equality. Both must therefore be . Extremality need not look like a sharp corner.
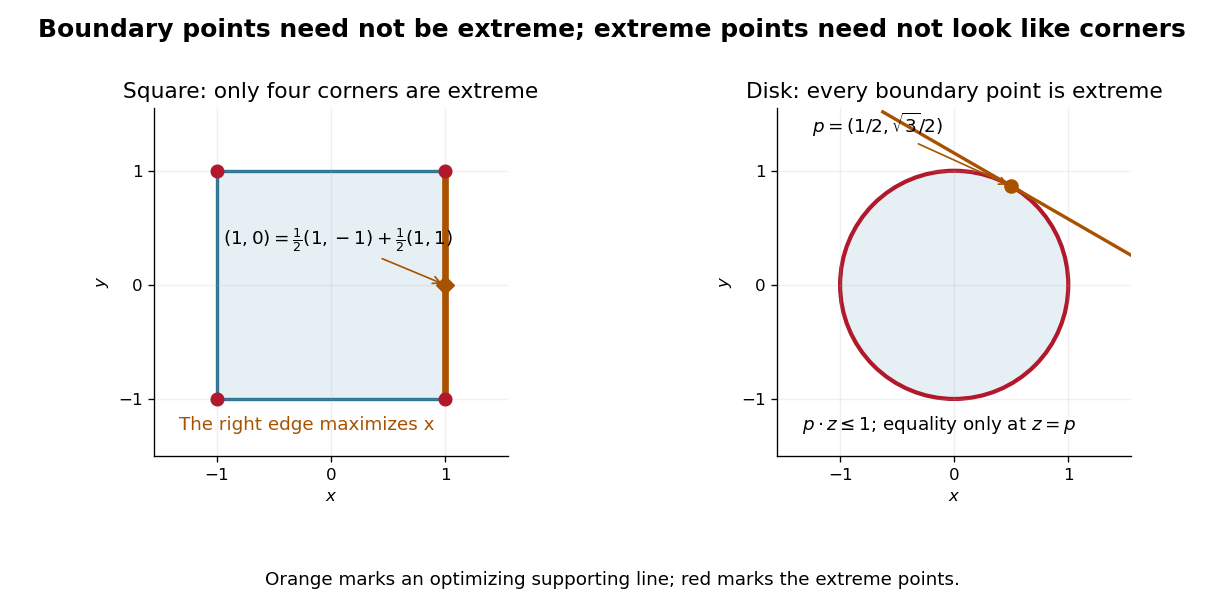
These points help describe all allowable mixtures. Every is a convex combination of its four corners, with the weight on equal to . For the unit disk, write , with and a unit vector; at zero choose any . ThenTwo extreme points suffice for that mixture. The Krein-Milman theorem gives a much broader reconstruction: a nonempty compact convex set in a locally convex space whose topology is Hausdorff is the closed convex hull of its extreme points.
Mark Krein and David Milman published their reconstruction theorem in 1940. Milman's colleagues describe that result and its subsequent use as a method of representing convex sets through their extreme points.[ref]
David Milman (1912–1982) by Israel Gohberg and others. David Milman (1912–1982), printed p. 4: 1940 collaboration with M. G. Krein, the reconstruction theorem and subsequent method; citation 3 refers to their original paper
An exposed point is a point uniquely selected by maximizing a linear functional. In , a point of a convex set is exposed if some vector satisfiesGeometrically, a supporting hyperplane touches the convex set only at . Every exposed point is an extreme point: a convex combination that attains the maximum can put positive weight only on maximizers, and there is only one.[ref]
Convex geometry (BME course BMETE94AM22). §6, Definition 6.2 and Proposition 6.7, printed pp. 36–37: exposed points and their inclusion among extremal points
The unit disk calculation in extreme point exposes every point of the unit circle. For a corner of the square, exposes it: attains two only at . However, maximizing exposes no single point on the right edge, since all of them have the same objective value. A linear functional may have several optimal points, even when some of them are extreme.
The distinction appears at a smooth join between a straight segment and a curved boundary. Consider the convex hullThe upper tangent from meets the unit circle at . The supporting line isEvery point of the unit disk has , with equality only at . Hence the convex face of where equality holds is exactly the line segment .
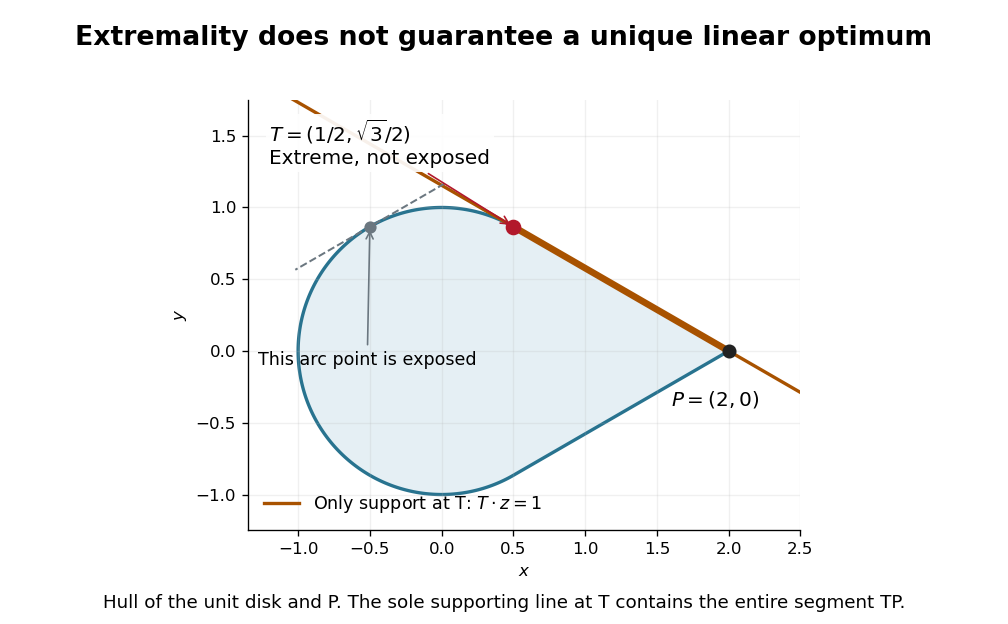
An extreme point can fail to be an exposed point
. Original analytic convex hull of the unit disk and . The tangent contact is extreme, but its only supporting line contains the entire line segment . A different marked point on the curved arc is exposed by its own tangent line. Details.The point is extreme. If a nontrivial convex combination of two points of equals , both must belong to the convex face . Since is an endpoint of that line segment, both must equal .
Yet is not exposed. A nonzero linear functional maximizing at on must also maximize there on the included unit disk. Its vector must be a positive multiple of , by the equality condition in the Cauchy-Schwarz inequality. It then gives the same value as . No linear functional can select alone. Being an extreme point is a property of possible mixtures; being an exposed point adds the ability to distinguish it by one linear objective.
For the real l-infinity sequence space, every coordinate of an extreme point must be an endpoint of ; any slack coordinate permits opposite perturbations. For the real absolutely summable sequence space, a unit vector with two nonzero coordinates permits a transfer of mass between them, so only signed coordinate vectors are extreme. For the real l2 sequence space, the parallelogram law makes every unit vector extreme. In all three cases interior points of the unit ball are nonextreme.
For compact Hausdorff , the extreme points of the real unit ball in the space of continuous functions on a compact space are precisely its continuous sign-valued functions. A point with permits a nonzero continuous bump perturbation supported where there is uniform slack, while pointwise equality at an endpoint of forces both functions in a midpoint decomposition to agree. For the Cantor set, clopen indicators give the perturbations directly.
Every real continuous function of supremum norm at most one on the Cantor set is a uniform limit of convex combinations of continuous sign functions. Approximate on a finite Cantor cylinder partition by values . The sign vector has weight , whose coordinate means are . This proves a closed convex hull identity without weak compactness.
For real scalars the extremes are the almost-everywhere sign-valued functions. A positive-measure region uniformly inside permits opposite nontrivial bounded perturbations, proving necessity. Equality at either endpoint forces both members of a convex decomposition to agree, proving sufficiency. For complex scalars the same criterion uses unit-modulus functions and the strict convexity of the complex unit disk.
Projections onto convex sets is an iterative feasibility method that successively applies a Euclidean projection onto a convex set to each closed convex constraint set. With two sets it uses . It seeks a point in the intersection; a single projection onto one set is a different operation, and the method does not generally compute the closest intersection point to the initial iterate.
For a nonempty closed convex subset of a finite-dimensional inner-product space, is the unique point of minimizing .
This closest-point map is the metric projection onto a closed convex set. Repeated projections onto several sets form the separate projections onto convex sets method.
For ,
For , the projection of has coordinates , where the scalar multiplier is chosen so that . Thus the projection reduces to a continuous one-dimensional root-finding problem.
The support function of a nonempty set is . It is convex and positively homogeneous, and for a closed convex set its convex conjugate is the indicator function of .
For a nonempty closed convex set , the finite-valued support function has subgradients exactly at the maximizing points of . This follows from Fenchel–Young inequality and the conjugacy between the support function and the indicator functional of a constraint set. For compact , the exposed maximizing set is nonempty.
If , the support function is infinite along a kernel line. Otherwise linear programming duality gives the displayed minimum, attained because the corresponding linear programs are feasible with finite values. Splitting into nonnegative parts yields the equivalent minimum of . Thus worst-case revenue over a polyhedral uncertainty set is , with value off the row space.
For , linear programming duality giveswhere is the positive part of a real-valued function. To see equality directly, order the coordinates and choose for , or for . The threshold expression then equals the sum of the largest components. Introducing the variables turns this convex piecewise-linear objective into a linear program.
For a real symmetric matrix with eigenvalues , the sum of its largest eigenvalues is the support function of the fantope:Here is the Loewner order. In an orthonormal eigenbasis for , the objective depends only on the diagonal entries of , which lie in the capped simplex. Thus the identity reduces to the sum of the largest components of the eigenvalues.
For a real symmetric matrix and ,Indeed is a rank- orthogonal projection matrix in the fantope, and projecting onto the eigenvectors of the largest eigenvalues attains the support function maximum. Equivalently, the largest matrix trace of a compression to a -dimensional vector subspace is the sum of the largest eigenvalues.
For a finite-dimensional Hermitian operator with decreasing eigenvalues and integer , maximizing over positive contractions with trace gives the sum of its leading eigenvalues. In an orthonormal eigenbasis, the diagonal entries of lie in and sum to . Moving their weight to the largest eigenvalues can only increase the objective. An orthogonal projection onto their eigenvectors attains the maximum.
The sum of the largest eigenvalues has the semidefinite program representationFor every feasible in the fantope, positive semidefinite trace nonnegativity gives . To attain equality, use an orthonormal eigenbasis of and choose in that basis, with the same threshold choice as in the threshold formula for the sum of the largest components. This argument also covers , without requiring strict feasibility of the maximization program.
For an integer , the capped simplexis the convex hull of the zero-one vectors having exactly entries equal to one. It is a convex polytope whose extreme points are precisely these vectors.
If a feasible vector has a fractional coordinate, the integer coordinate sum forces at least two fractional coordinates. Perturbing one upward and the other downward by a sufficiently small amount gives two distinct feasible vectors whose midpoint is the original vector. It is therefore not an extreme point. Conversely, a zero-one vector cannot be a nontrivial convex combination of points of , since each coordinate is already at a bound.
For in the second-order cone, the Cauchy-Schwarz inequality gives . Thus the cone is contained in its dual cone. Conversely, if and , pairing with is negative. If and , use . Every point outside the cone therefore lies outside its dual, proving that it is a self-dual cone.
A second-order cone program has a linear objective and affine constraints taking values in products of second-order cones and nonnegative orthants. Norm epigraphs have the form ; quadratic epigraphs admit the affine lift , equivalent to . Product-cone self-concordant barriers give interior-point methods.
The objective has the exact lift with , , and . Every lifted feasible value bounds the original objective, and choosing tight epigraph variables proves equality. The product-cone barrier parameter is : two for each Lorentz block and one for each orthant slack. The fidelity norm remains unsquared, and negative derivatives remain unpenalized.
The convex hull of a set consists of every finite convex combination of its points. It collects all choices obtainable by mixing the original choices with nonnegative weights summing to one. For in a real vector space,Equivalently this is the smallest convex set containing . Mixing two already mixed points produces another finite convex combination, so the displayed set is convex; every convex set containing must contain all these mixtures.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. §2.1.4, printed p. 24: convex hull and smallest containing convex set
In an original planar example, take four points , , , and four additional samples , , , . Their convex hull is the filled convex polygon , including its boundary. None of the samples is , butThe coefficients are nonnegative and sum to one, providing an explicit membership certificate. Geometrically, first form on the line segment , then mix . The additional interior samples do not enlarge the convex hull.
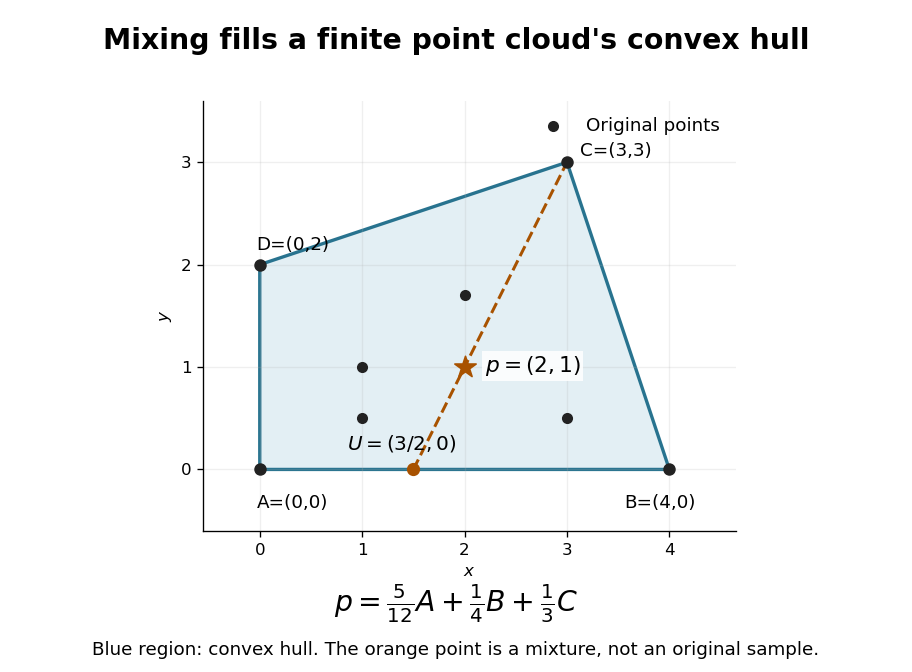
For a finite nonempty , the convex hull is the image of a probability simplex of weights under the linear map . The probability simplex is a compact set, and the map is continuous, so this convex hull is compact and closed. A one-point input stays one point; a collinear input stays in a line segment. Filling the convex hull does not necessarily produce a full-dimensional region.
The construction is useful whenever mixtures preserve the intended meaning of a choice. Mixing resource-allocation vectors, for example, interpolates their coordinate requirements. The convex hull describes the resulting feasible region. A coordinate-wise box can admit combinations that no mixture produces, as the outside-point certificate in linear optimization on a convex hull shows.
Start from a nondegenerate tetrahedron and insert remaining points one at a time. Discard a point inside the current convex polyhedron; otherwise replace faces visible from it by the cone from that point to the horizon of a convex polyhedron. Scanning every current face gives worst-case time complexity and current-hull storage in three dimensions. Coplanar input requires a separate degeneracy policy.
Every set of at least points in can be partitioned into two nonempty parts with intersecting convex hulls. To see this, take a nonzero affine dependence on of its points. Its positive and negative coefficient sums have the same magnitude . Dividing by expresses one point as a convex combination of the positive-coefficient points and also as a convex combination of the negative-coefficient points. Distribute zero-coefficient and remaining points arbitrarily between the parts. This theorem obstructs arbitrary labels for affine linear classifiers.
In a Banach space, the closed convex hull of a compact set is compact in the norm topology. Given , choose a finite -net for . Every convex combination of points of is within in norm of , by replacing its terms by their approximating . This finite-dimensional compact convex set has a finite -net, giving a finite -net for . Its closure is therefore totally bounded and complete, hence compact. Completeness of the ambient space is used at this last step.
The lower boundary of the convex hull of points in the plane: the portion visible from points sufficiently far in the negative vertical direction. Sorting its vertices by horizontal coordinate gives a chain with nondecreasing edge slopes; collinear interior vertices can be omitted.
A linear functional cannot exceed its best original value by mixing. For a finite nonempty set and in its convex hull,Every original point is itself in the convex hull, so equality between the two maxima follows. Moreover, a mixture attains the maximum exactly when all its positive weights are assigned to maximizing original points. Multiple maximizers can therefore produce a whole line segment or a higher-dimensional region of equally good choices.
For the eight samples above, use the linear functional . Its largest sample value is , and is the only maximizing sample. Thus the unique maximum over the whole convex polygon is also at . The line is a supporting line: every point of the convex hull lies in the half-space , and touches its boundary.
The point passes the coordinate-wise bounds , , but . This single inequality certifies that is outside the convex hull. A weighted mixture could not have a larger linear functional value than all its ingredients.
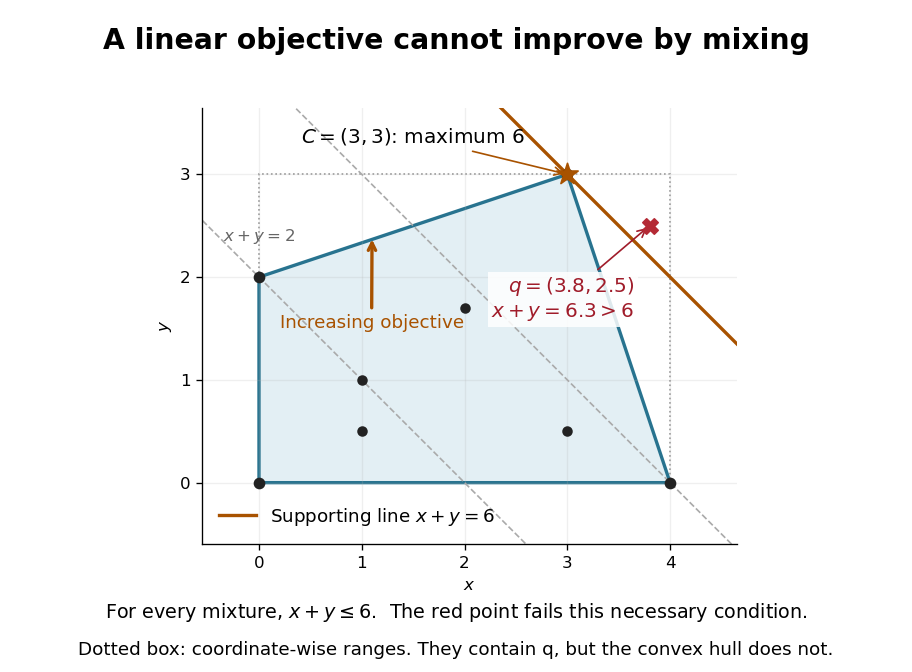
This explains a basic feature of linear programming: searching all mixtures of finitely many candidate vectors cannot improve the objective beyond the best candidate, though mixing equally good candidates can give more optimal choices. The conclusion depends on linearity. For the concave function , the new point instead attains zero, strictly above its value at every original sample. A nonlinear objective can favor a mixture.
The smallest closed convex set containing a set , equivalently the closure of its convex hull in the specified topology. The topology must be stated: the norm topology, weak topology and weak-star topology need not give the same closure for an arbitrary set.
Even a bounded infinite input need not have a closed convex hull. In the real line, let . Every finite convex combination of these positive points is positive, so zero is absent. Conversely, any lies between some and , and is their convex combination. HenceThe closed convex hull adds the missing limit point zero. For the finite eight-point example in convex hull, the convex hull is already closed, so taking the closed convex hull adds nothing.
Every point in the convex hull of a subset of is a convex combination of at most points of that subset. Thus in the plane three ingredients always suffice, however many samples were supplied. The representation of in convex hull illustrates this bound. Two ingredients need not suffice: the centroid of a triangle with only its three vertices as input is on none of their three pairwise line segments.
A short proof outline removes redundant ingredients. With more than points, the augmented vectors are linearly dependent. A dependence lets the weights vary while preserving both their sum and the represented point. Move along it until one positive weight first becomes zero; all weights stay nonnegative. Repeating leaves at most positive weights.
In his 1911 paper, Constantin Carathéodory used convex geometry to investigate the possible Fourier coefficients of positive harmonic functions. Its introduction interprets convex mixtures through the center of mass, connecting finite-dimensional geometry to constraints on a function's coefficients.[ref]
Über den Variabilitätsbereich der Fourier’schen Konstanten von positiven harmonischen Funktionen by Constantin Carathéodory. English translation by Nicholas J. Williams, Introduction §4, original printed p. 195; §I concerns the smallest containing convex domain
In an -dimensional real vector space, each member of a conic hull has a representation using at most generators. To prove it, take a finite positive-coefficient representation with more than terms. Its generators are linearly dependent, say , with some after reversing the relation if necessary. Subtract from each coefficient, taking . All coefficients stay nonnegative and at least one vanishes. Iterate. The bound differs from the bound for a convex hull because the coefficient sum is unrestricted.
A convex cone is a subset of a real vector space closed under nonnegative linear combinations: whenever and . The positive semidefinite cone and the copositive cone are examples, ordered by inclusion through the positive-semidefinite-plus-nonnegative cone.
A closed coordinate-sign region of Euclidean space. The orthants cover the space. An orthant contains no nontrivial affine line: for a nonzero direction, some coordinate eventually violates its sign restriction in one direction. Adding orthant inequalities to a nonempty linear polyhedron therefore permits construction of a basic feasible solution even when the original polyhedron has no vertex.
For a finite-dimensional random vector , let be the closed cone generated by the support of a probability distribution of . Every integrable strictly positively weighted barycentre lies in the relative interior of : every nonzero supporting functional on its span is positive on a set of positive probability. Conversely, put and . Its dual cone equals that of , so and . For , subtract a sufficiently small positive multiple of and represent the remainder using ; adding the constant positive weight back gives .
For an integrable finite-dimensional random vector , let . The displayed convex cone is open relative to . Given a bounded strictly positive , the perturbation , , changes its weighted expectation by , whereFor , : otherwise almost surely. Thus is invertible on , and these perturbations give a neighborhood of every point of the cone. The hyperplane separation theorem consequently gives the alternative: either zero is a strictly positively weighted expectation, or a nonzero direction in has a nonnegative dot product with almost surely and a positive dot product with positive probability. To obtain the latter assertion, test the separating direction with and let .
Every nonzero vector of is a nonnegative combination of at most as many support-minimal vectors as it has nonzero coordinates. Choose a nonnegative kernel vector of minimal nonempty support inside the support of ; subtract , where . The remainder is nonnegative, remains in the kernel, and has strictly smaller support. Induction proves the decomposition. On a minimal support, the kernel is one-dimensional: an independent kernel direction could perturb a strictly positive vector to the boundary of that support without making it zero, contradicting minimality. For an integer matrix with entries bounded by , cofactor determinants give an integer generator with coordinates bounded by , where is the ambient number of coordinates.
The lineality space of a convex cone is its largest linear subspace, equal to . Every nonempty face contains it. A cone is pointed exactly when this space is zero.
// Target: mathematical-optimization.bigb
A self-dual cone equals its dual cone under the specified inner product. The nonnegative orthant, second-order cone and positive semidefinite cone are standard examples. Self-duality of a set alone does not establish primal or dual feasibility.
In conic optimization, a proper cone is a closed convex cone that is a pointed cone and has nonempty interior in its ambient finite-dimensional space. These conditions permit strict cone feasibility and nondegenerate barrier geometry.
The convex cone of completely positive matrices:It is a closed convex cone and the dual cone of the copositive cone under the Frobenius inner product. The finite-sum definition imposes no closure by fiat; closedness of the completely positive cone supplies that fact.
Use the conic Carathéodory theorem in the real space of symmetric matrices, of dimension . A convergent sequence in the completely positive cone has padded factorizations with nonnegative factors. Their total squared norms equal and are uniformly bounded. A simultaneous convergent subsequence of the finite factor tuple gives with . Thus the limit remains in the cone. The argument also bounds the required number of factors by .
A convex cone containing no nonzero line through the origin, equivalently . The copositive cone is pointed: a matrix in both it and its negative has zero quadratic form on the nonnegative orthant; testing and kills all entries.
A convex cone that is a closed set in its ambient topology. In a finite-dimensional normed vector space, this means it contains every limit of its convergent sequences. For example, the positive semidefinite cone is closed because each test is continuous.
For a closed convex cone in a finite-dimensional real inner product space and , there exists with and for all . Here is a direct proof. A nearest point exists by compactness after restricting to a sufficiently large ball. Differentiating squared distance along the segment towards gives . Using and shows . Set : then and . This is a conic form of the Hahn-Banach separation theorem.
The set of all finite conic combinations of elements of , including zero. It is the smallest convex cone containing . It need not be closed even when is closed: the closed set generates vectors converging to via , but no nonzero generated vector has second coordinate zero.
A finitely generated cone is a conic hull of a finite set of vectors. Every point admits a representation using linearly independent active generators, by eliminating dependence while keeping coefficients nonnegative.
A finitely generated cone is a closed convex cone. For a convergent sequence of represented vectors, use linearly independent active generators and pass to a subsequence with the same active set. Its coefficients converge through a fixed left inverse and retain nonnegativity. General linear images of closed cones need not be closed; finiteness of the generators supplies the missing argument.
A finite sum with . Unlike a convex combination, the coefficients need not sum to one. Zero coefficients and the empty sum are allowed.
The real symmetric matrices that are copositive matrices form a closed convex cone:Each fixed gives a closed linear inequality in . Their intersection is therefore closed and convex, and it is preserved by nonnegative scaling.
Under the nonnegative-pairing convention for the dual cone, follows from . Conversely, if , separation from a closed convex cone gives a separating nonnegative on all generators and negative on . That is a copositive matrix, so . This proves the displayed equality using closedness of the completely positive cone.
The interior consists exactly of strictly copositive matrices. If has positive minimum on the compact nonnegative unit sphere, perturbations of operator norm less than preserve this positive lower bound there. Conversely, if a unit nonnegative vector has zero quadratic form, leaves the copositive cone for every . Thus such a matrix is not interior. The identity matrix is a convenient interior point.
The sums of a real positive semidefinite matrix and a symmetric nonnegative matrix form a convex cone inside the copositive cone. Both terms have nonnegative quadratic forms on the nonnegative orthant. The Horn copositive matrix shows that the inclusion is strict in dimension five; the sum of squares criterion for a biquadratic form explains this cone's relation to semidefinite programming.
The positive semidefinite matrices form a convex cone because nonnegative combinations preserve nonnegative quadratic forms.
Articles were limited to the first 100 out of 107 total.
Articles by others on the same topic



In mathematics, particularly in the field of convex analysis, a **convex set** is defined as a subset \( C \) of a vector space such that, for any two points \( x \) and \( y \) in \( C \), the line segment connecting \( x \) and \( y \) is also entirely contained within \( C \).