The joint probability density of the two independent standard normal random variables is . The polar coordinates map has absolute Jacobian determinant , so the change of variables for probability densities givesAt the origin the angle may be assigned arbitrarily: that point has probability zero. The joint probability density factorizes as a Rayleigh distribution density and a continuous uniform distribution density . Hence and are independent.
For , substitute to findTherefore , equivalently , and applying a measurable function to preserves its independence from . Explicitly, with ,Thus and independently. This polar decomposition of a planar standard normal vector separates the uniformly distributed direction from its random squared distance.
Set . In polar coordinates, the event is , the angular sectorBecause has the continuous uniform distribution on an interval of length , the probability is the sector's angular length divided by :The symmetry of the standard normal distribution in makes the lower sector equally likely. Their disjoint union is , apart from , an event of probability zero. Therefore the requested cumulative distribution function isThis is the unit-scale half-Cauchy distribution. At there is no atom, and as the cumulative distribution function tends to one.
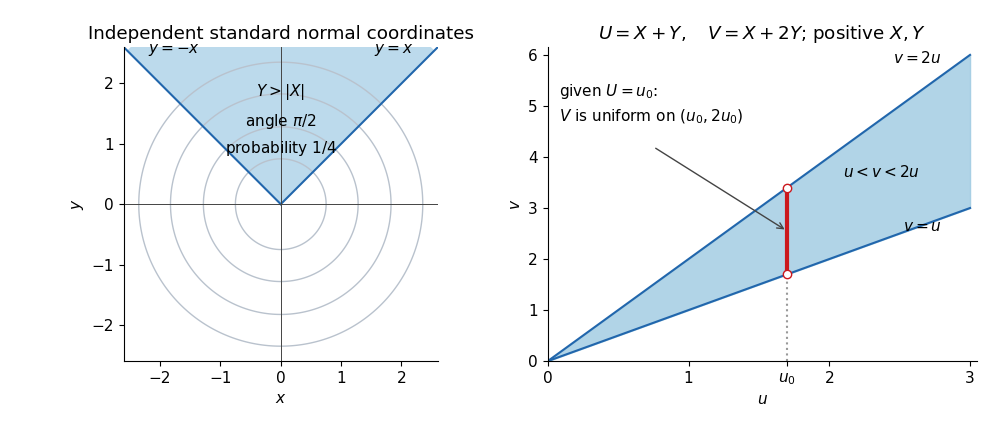

The left panel uses , giving a sector of angle and probability . The right panel displays the domain for the next change of variables for probability densities; a vertical section through it determines the conditional range.
The inverse linear transformation isThe positive support is exactly and . The independence and rate-one exponential distributions give there. Since , the change of variables for probability densities yieldsAlthough the density's value depends only on , its support does not factor as a product of fixed intervals. Thus this expression does not imply independence of and .
Integrating the joint probability density across gives the marginal densityFor every , the conditional probability density is consequentlyHenceThis also follows from two independent exponential variables conditioned on their sum: given , the variable is uniform on , and . Conditioning on here is defined through the conditional probability density, rather than division by , which is zero. The endpoint lies outside the positive marginal support and needs no specified conditional law.
For fixed , the support inequalities become . The marginal density is thereforeIt is nonnegative and integrates to . Another interpretation is that sums independent exponential random variables of rates and , so it has a hypoexponential distribution. The mean is , which agrees with .
Articles by others on the same topic
There are currently no matching articles.